Does donating a sports collection in pieces avoid the appraisal requirement?
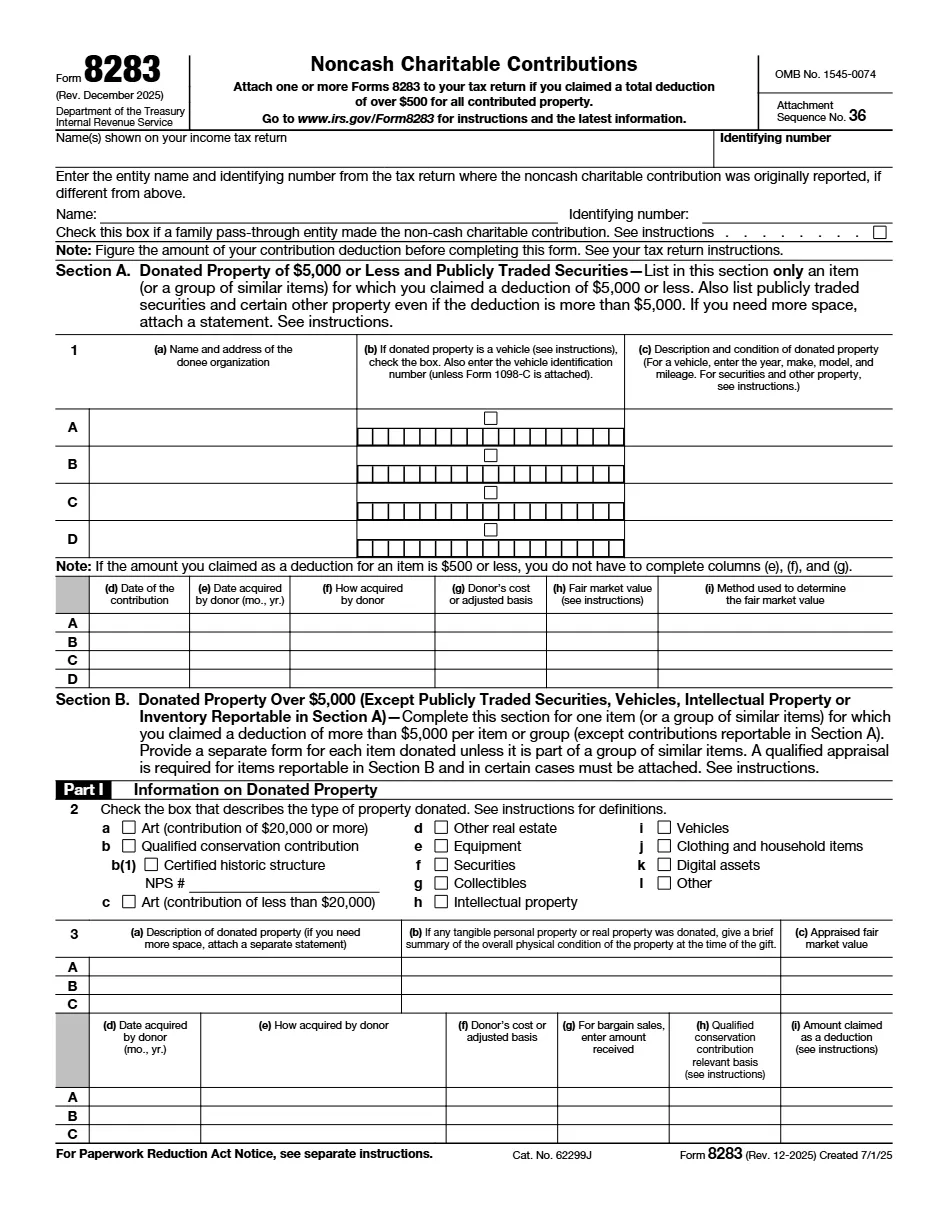
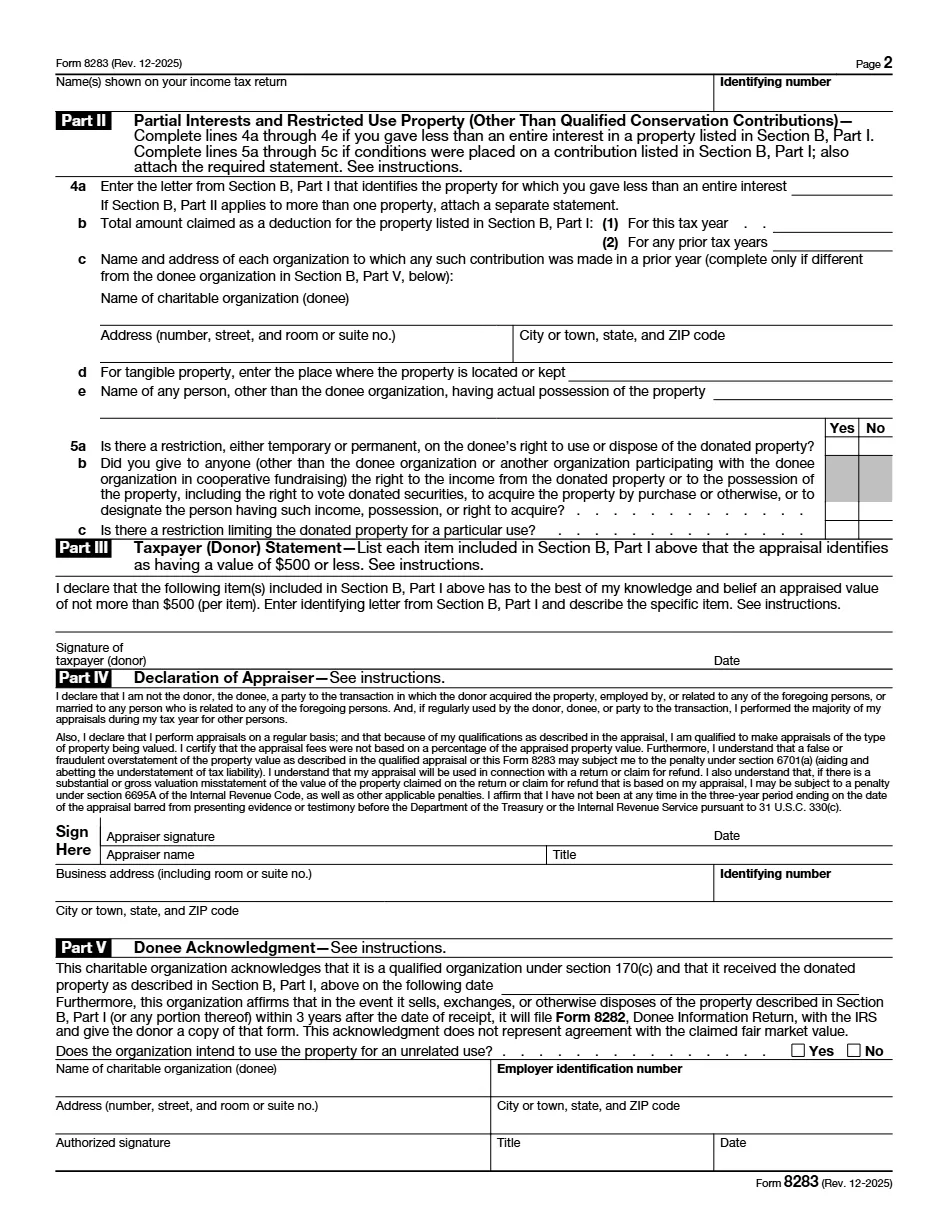
No. The IRS classifies sports memorabilia as similar items, so donations during the year are aggregated even when they go to different charities. Once the combined claimed value passes $5,000, a qualified appraisal and a signed Form 8283 Section B are required for the group, per IRS Publication 561.
What evidence supports the value of donated memorabilia?
Completed sales of comparable items, especially auction results, carry the weight; retail asking prices and static price guides are routinely discounted. Each piece should be described at the player, event, edition, and condition level, with signatures, serial numbers, authentication, and provenance documented in the report.
Will the charity auctioning my memorabilia affect the deduction?
It can. When tangible personal property is put to a use unrelated to the charity's exempt purpose, such as immediate sale at a fundraising auction, the deduction may be limited to your basis rather than fair market value. The donee's planned use should be settled before the gift is valued.
Are donated game tickets valued at their face value?
No, not when a secondary market exists. Fair market value is what a buyer would pay at the time of contribution, which for high-demand events can be a multiple of face value and for weak matchups can be less. Appraisals built on actual market data are the ones that survive review.