When does artwork on Form 706 require a formal appraisal?
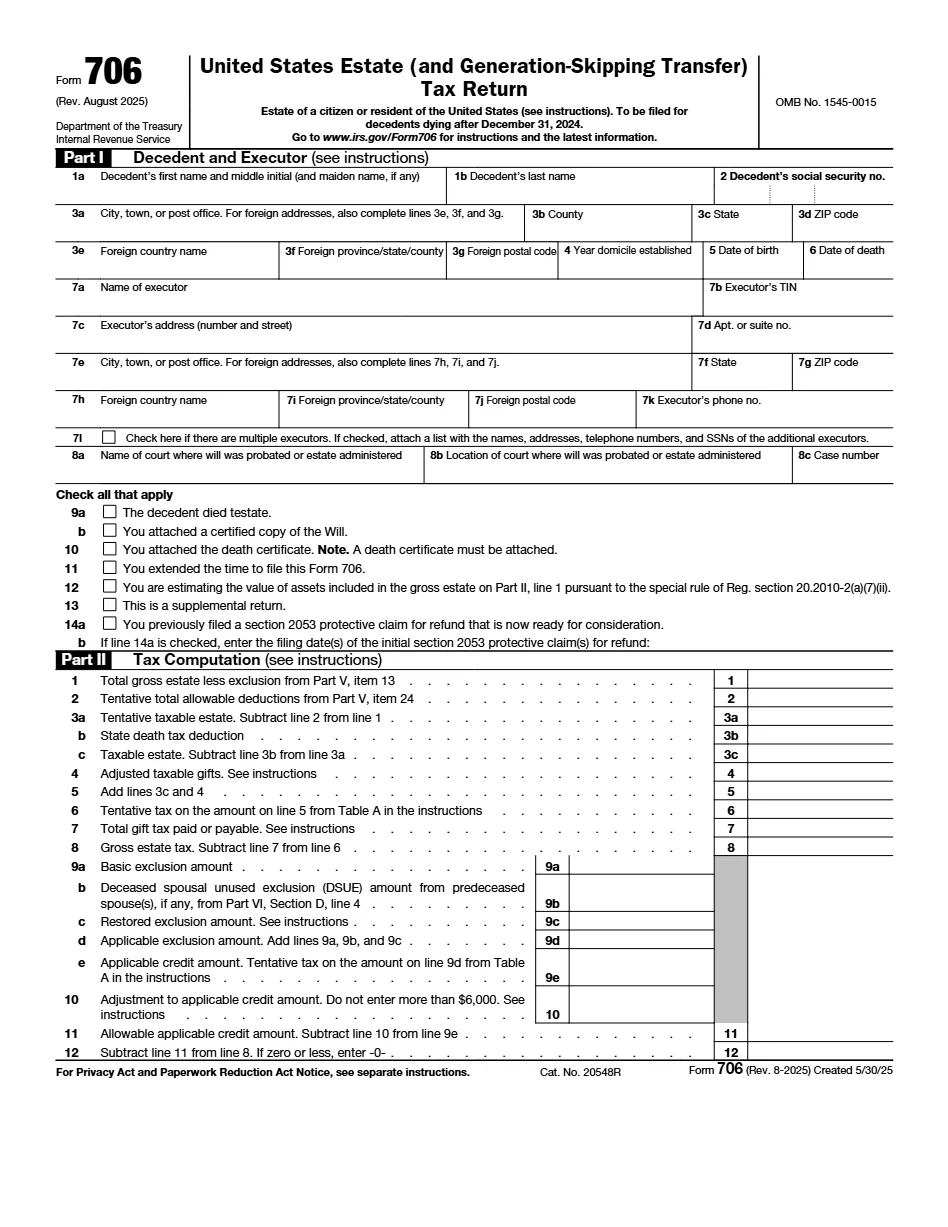
Under Treasury Regulation 20.2031-6, any item of marked artistic or intrinsic value over $3,000, or a collection over $10,000, requires an expert appraisal executed under oath and filed with the return, with the appraiser's qualifications attached. Works valued at $20,000 or more also need detailed descriptive documentation and a professional-quality photograph.
Which IRS reviewers scrutinize art values on estate tax returns?
Art reported above $20,000 is automatically referred to IRS Art Appraisal Services, and works of $50,000 or more can go to the Art Advisory Panel; Rev. Proc. 96-15 also lets an estate request a binding value in advance for high-value pieces. Provenance, exhibition history, condition reports, and photographs are what these reviewers weigh.
Can an estate use the gallery's retail asking price for artwork?
No. Estate tax fair market value must reflect the market in which the art is most commonly sold to the public, typically the auction market, and posted gallery prices are not controlling because they may never be realized. Purchase price and insurance schedule values are likewise rejected when they conflict with market evidence at the valuation date.
How does the Form 706 deadline affect estate art appraisals?
The return is generally due nine months after death, which compresses complex art valuations. Rushed reports with thin comparable research or missing condition analysis are the ones the Art Advisory Panel most often adjusts, so we anchor each work to documented sales as of the date of death, or the alternate valuation date if elected, early in administration.