Is my RV donation deduction based on the appraisal or the charity's sale price?
Usually the sale price. When a charity sells a donated motor vehicle without significant intervening use or material improvement, the deduction is capped at the gross proceeds even if the appraised value is higher, under IRS vehicle donation rules. A qualified appraisal does not override that limitation.
When can I deduct an RV's full fair market value instead?
Only in the IRS-recognized situations: the charity significantly uses the RV in its programs, materially improves it, or transfers it below market to a needy individual in furtherance of its mission. Value then comes from private-party guide pricing adjusted for the coach's actual condition, or a qualified appraisal at higher values.
What must the charity's acknowledgment for a donated RV include?
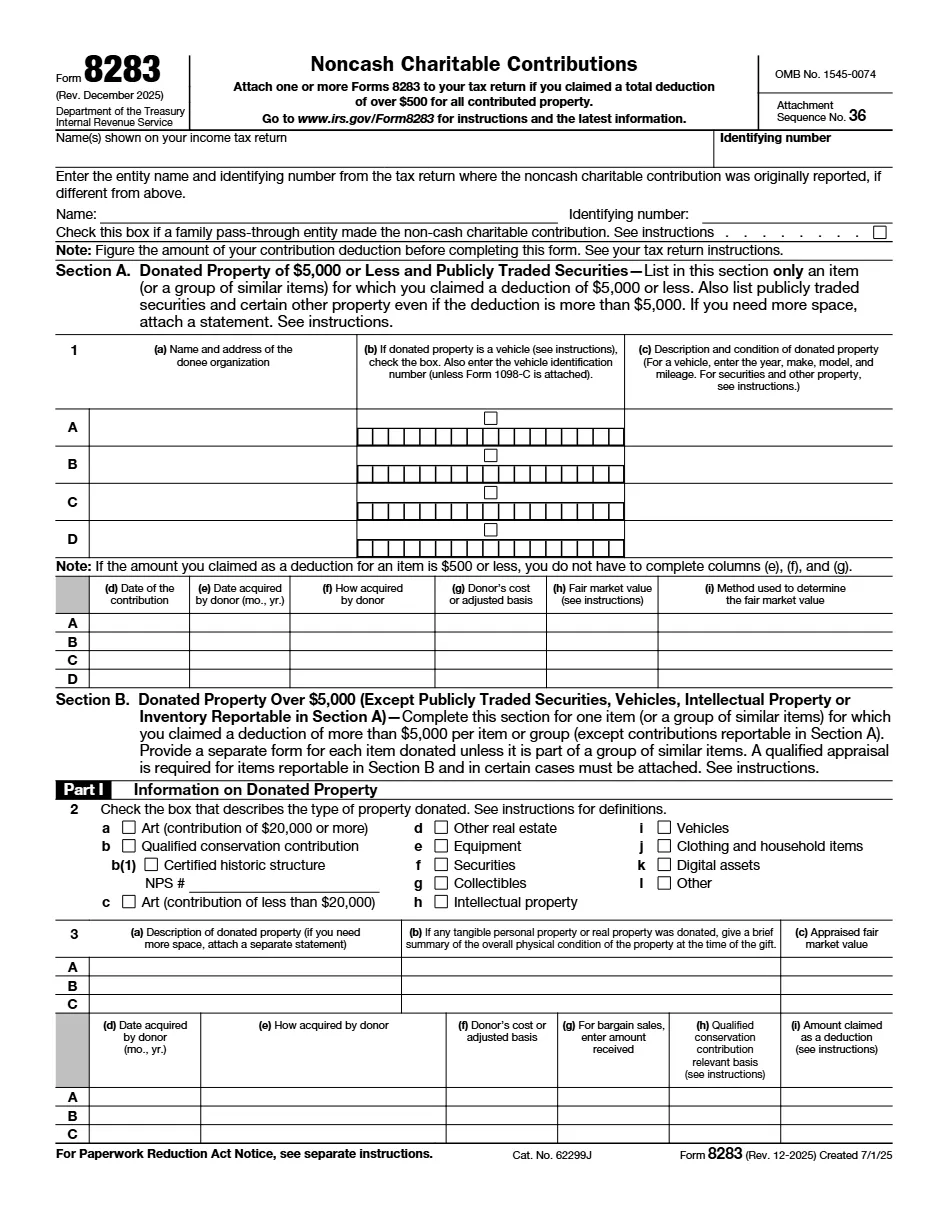
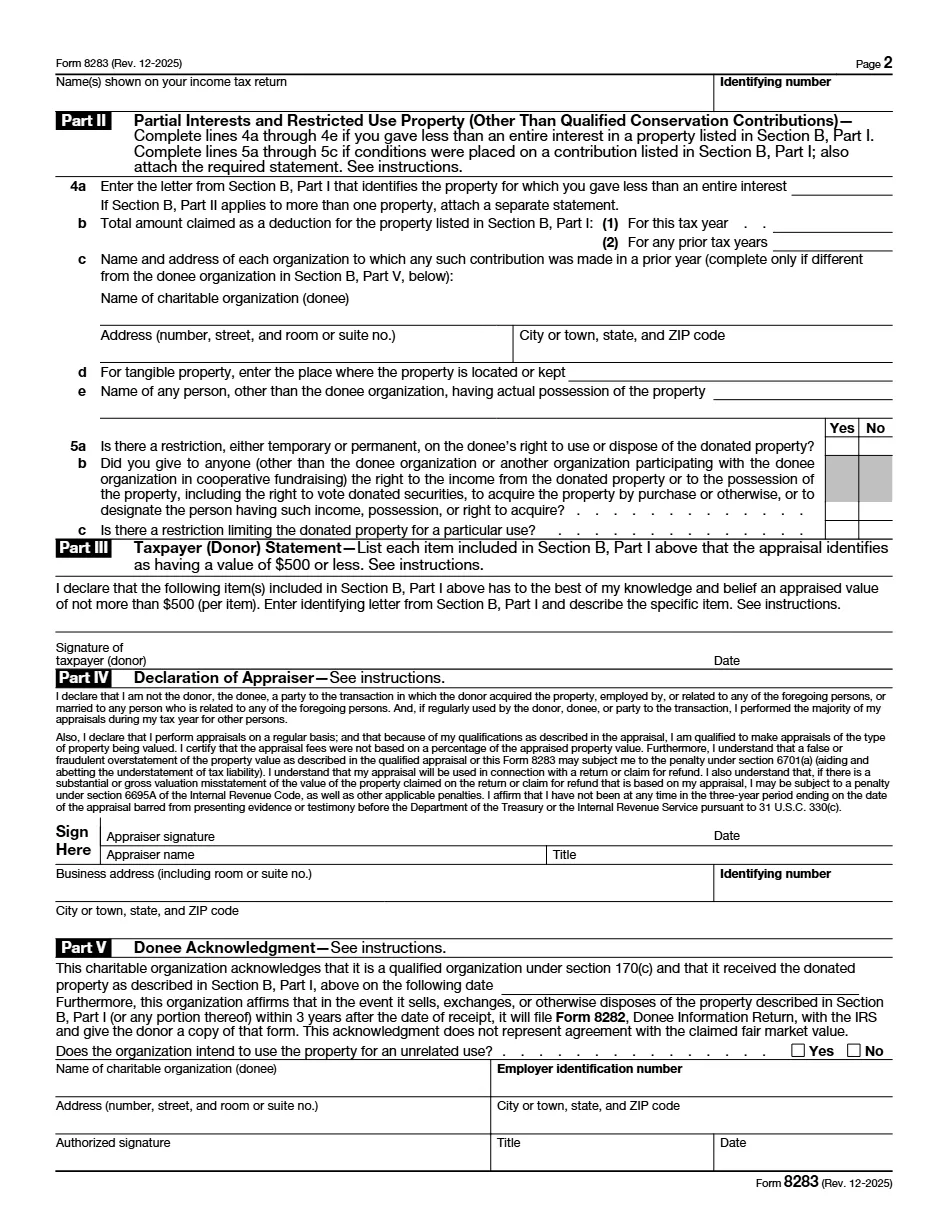
Your name and taxpayer ID, the VIN, the donation date, and either the gross sale proceeds or a certification of qualifying use or improvement. Claims over $5,000 also require Form 8283 Section B with the appraiser's and charity's signatures, and if the charity sells the RV for $500 or less, the deduction is the lesser of FMV or $500.
What documentation mistakes undermine RV donation deductions?
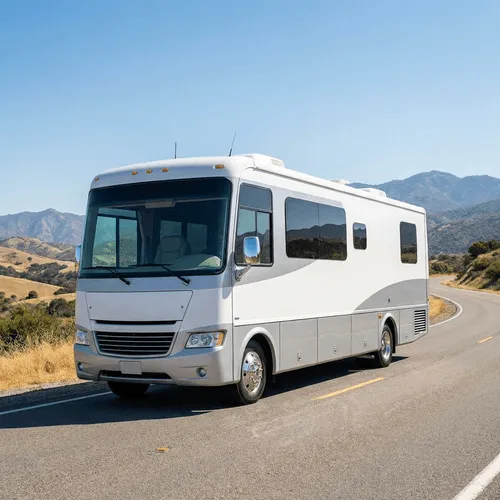
Mismatches between the title transfer, the acknowledgment, and Form 8283: wrong dates, VINs, or descriptions, such as motorhome versus travel trailer. Claiming an excellent-condition guide value for a coach with damage, high mileage, or mechanical issues is another red flag, as is reporting appraised FMV while ignoring the charity's reported sale.