How is a car valued for federal estate tax?
At fair market value on the decedent's date of death, not today's market and not the original purchase price. The date-specific rule matters because vehicle markets move: a collector car's value can shift materially between death and filing, and neither the insured amount nor the invoice price substitutes for date-of-death market evidence.
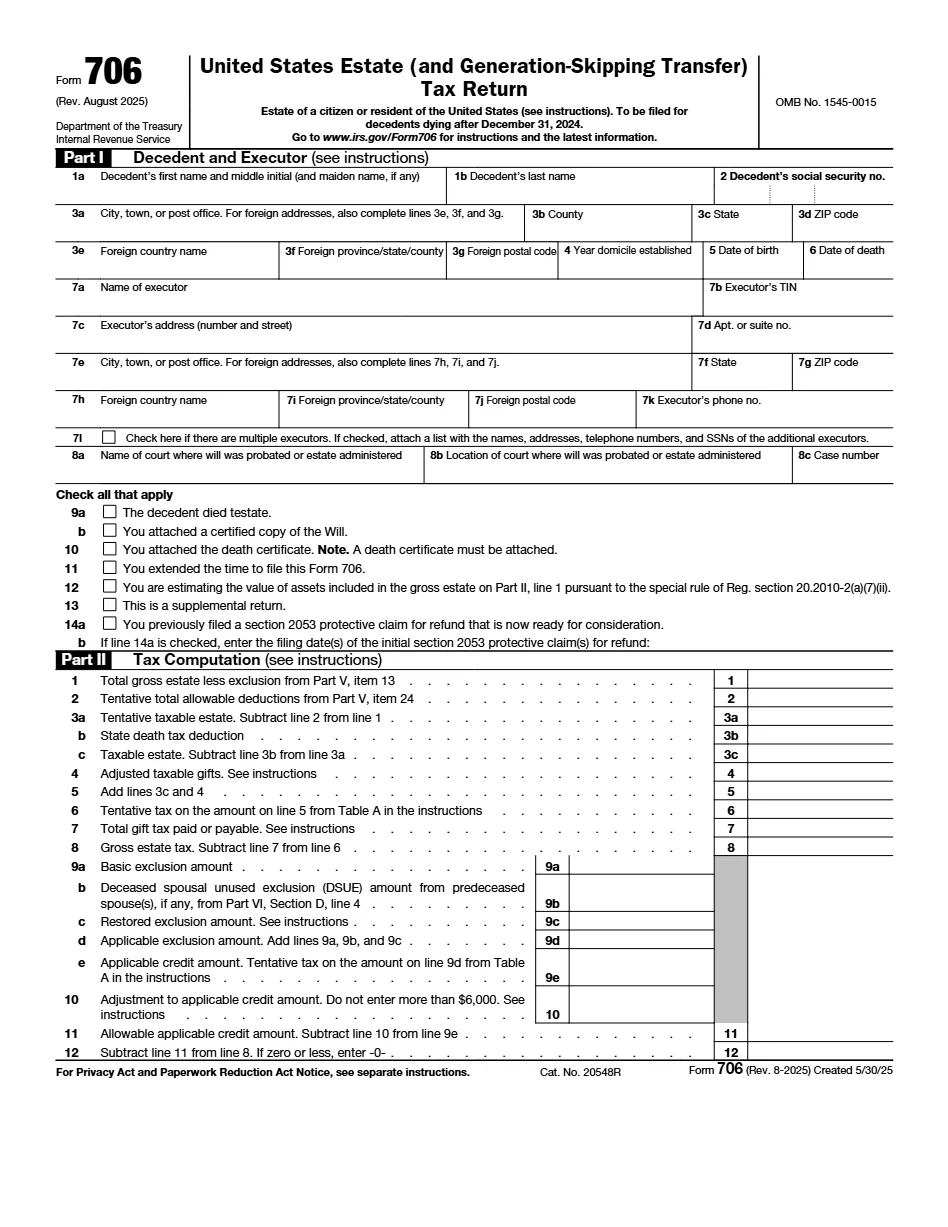
When does an estate vehicle need a qualified appraisal for Form 706?
When it is reported at more than $5,000. A defensible report documents the VIN, photographs, condition grading, mileage and maintenance history, and comparable sales near the valuation date, which is what withstands IRS examination for unusual, modified, or collector vehicles.
Can the executor just report a Kelley Blue Book number for the car?
Only as a supported starting point. Guide values must match the exact year, make, model, trim, mileage, and condition, and both government valuation practice and bankruptcy case law treat KBB and NADA figures as baselines to be adjusted on evidence. Dated printouts, photos, and condition notes belong in the estate file.
Do vehicle values matter if the estate is below the filing threshold?
Yes. Even when no Form 706 is due (the 2026 filing trigger is $15 million), probate courts and beneficiaries still expect a good-faith, documented fair market value for each vehicle so the inventory and percentage distributions under the will can be verified. Misvalued or omitted autos are a recurring source of beneficiary disputes.