What value must be reported when gifting a boat?
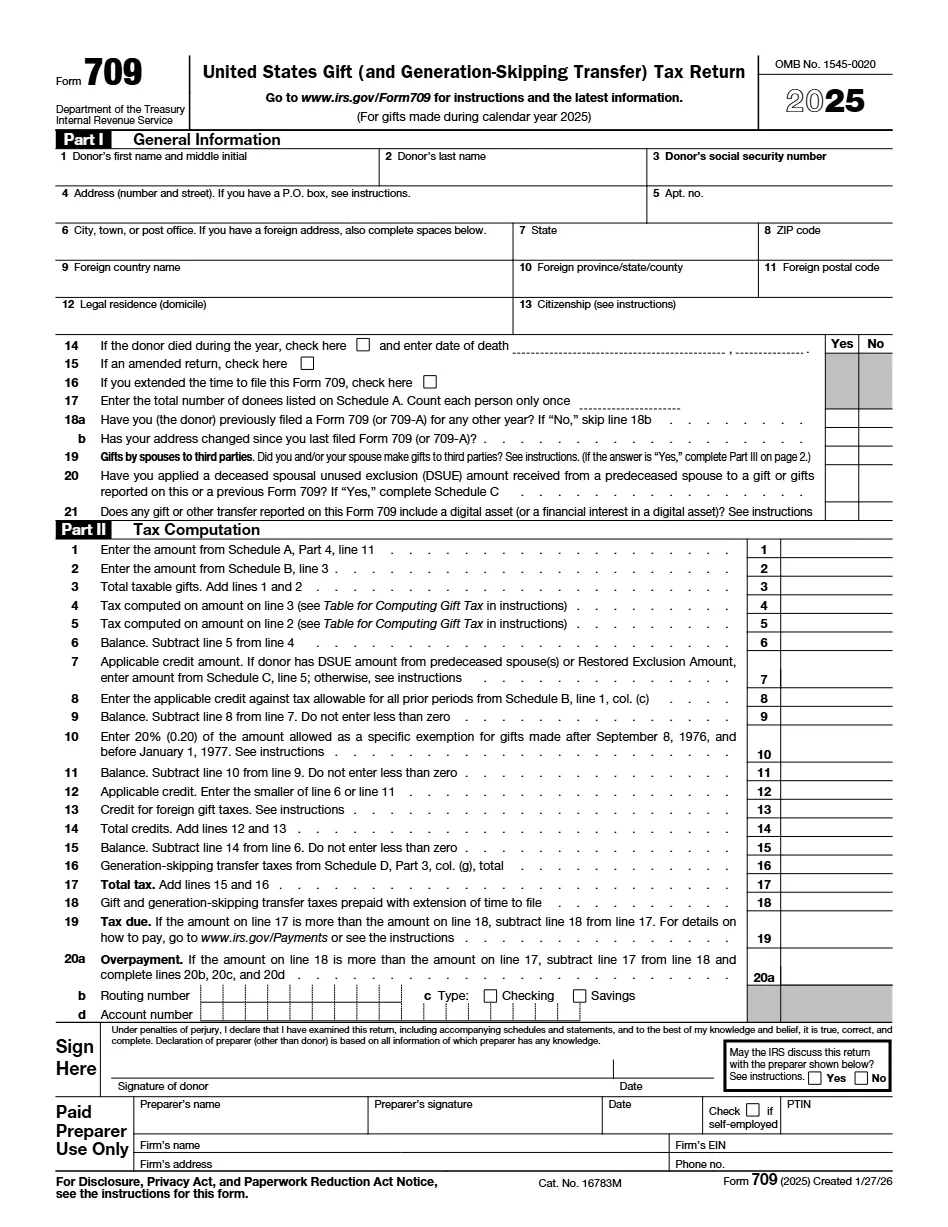
Fair market value on the date of the gift under the federal gift tax regulations: the price a willing buyer and willing seller would agree on in the relevant market. If the gift exceeds the annual exclusion, $19,000 per recipient for 2025, the donor reports it on Form 709 and the excess draws down the lifetime exemption.
Does selling a boat to family for a token price avoid gift tax?
No. When property transfers for less than adequate and full consideration, the spread between fair market value and the price paid is treated as a gift under 26 U.S.C. Section 2512(b) and belongs on Form 709. Informal family sales at a dollar are exactly the transfers this rule catches.
Will a pricing guide number alone satisfy the IRS for a gifted boat?
Rarely. Publication 561 limits the guides-only shortcut to inexpensive small boats and otherwise expects a marine surveyor's appraisal, because condition dominates boat value. The IRS also rejects list prices and unadjusted guide values that ignore the vessel's actual condition and verified comparable sales.
Can a state tax a gifted boat even when no federal gift tax is due?
Yes. Some states impose use tax on the boat's fair market value at registration regardless of the donor-recipient relationship, and the registration agency may apply its own valuation guide or demand an appraisal. That creates a second valuation record that should stay consistent with the federal reporting.