Is book value a reliable stand-in for equipment market value?
No. Balance-sheet carrying value reflects accounting policy, not observable resale prices or replacement cost. An appraisal adjusts for actual market conditions, physical wear, and functional and economic obsolescence, so relying on book value for lending, sale, or insurance decisions can badly misstate what machinery is worth.
What separates fair market value from liquidation value on machinery?
Exposure time and sale conditions. Fair market value assumes a willing buyer and seller with reasonable marketing time, orderly liquidation value assumes a compressed but managed sale, and forced liquidation value reflects auction-speed disposal. Lenders often underwrite against liquidation premises, so we confirm the required premise before starting.
When must Alabama businesses report equipment for property tax?
Between October 1 and December 31 each year. Alabama requires an itemized listing of personal property owned on October 1, with acquisition dates and costs, filed with the local assessing official; missing the third Monday in January triggers a 10% penalty. Equipment is assessed as Class II property at 20% of market value.
Does Alabama exempt farm equipment from property tax?
Yes, when it qualifies. Farm tractors, implements, and tools used by the owner exclusively in agricultural or forest operations are exempt from listing and assessment under Ala. Admin. Code Rule 810-4-1-.13. The exemption is use-based, though: poultry processing and hatchery equipment used in industrial operations remains fully taxable as business personal property.
What makes Alabama's auction market matter for machinery values?
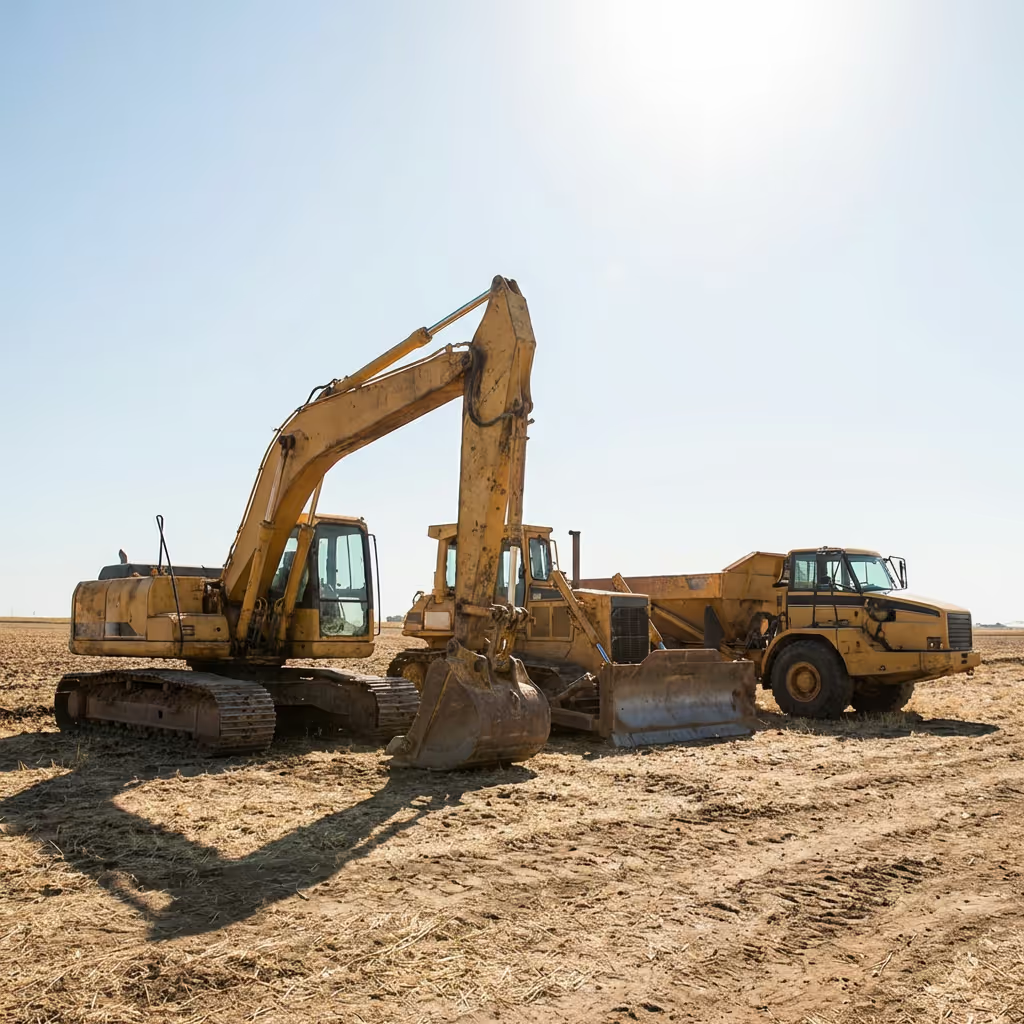
It generates in-state comparable sales. Alabama hosts large multi-day heavy-equipment auctions around Montgomery alongside a network of regional dealers, and those documented hammer prices give appraisers direct market evidence for dozers, excavators, and trucks working in Alabama rather than relying solely on national averages.