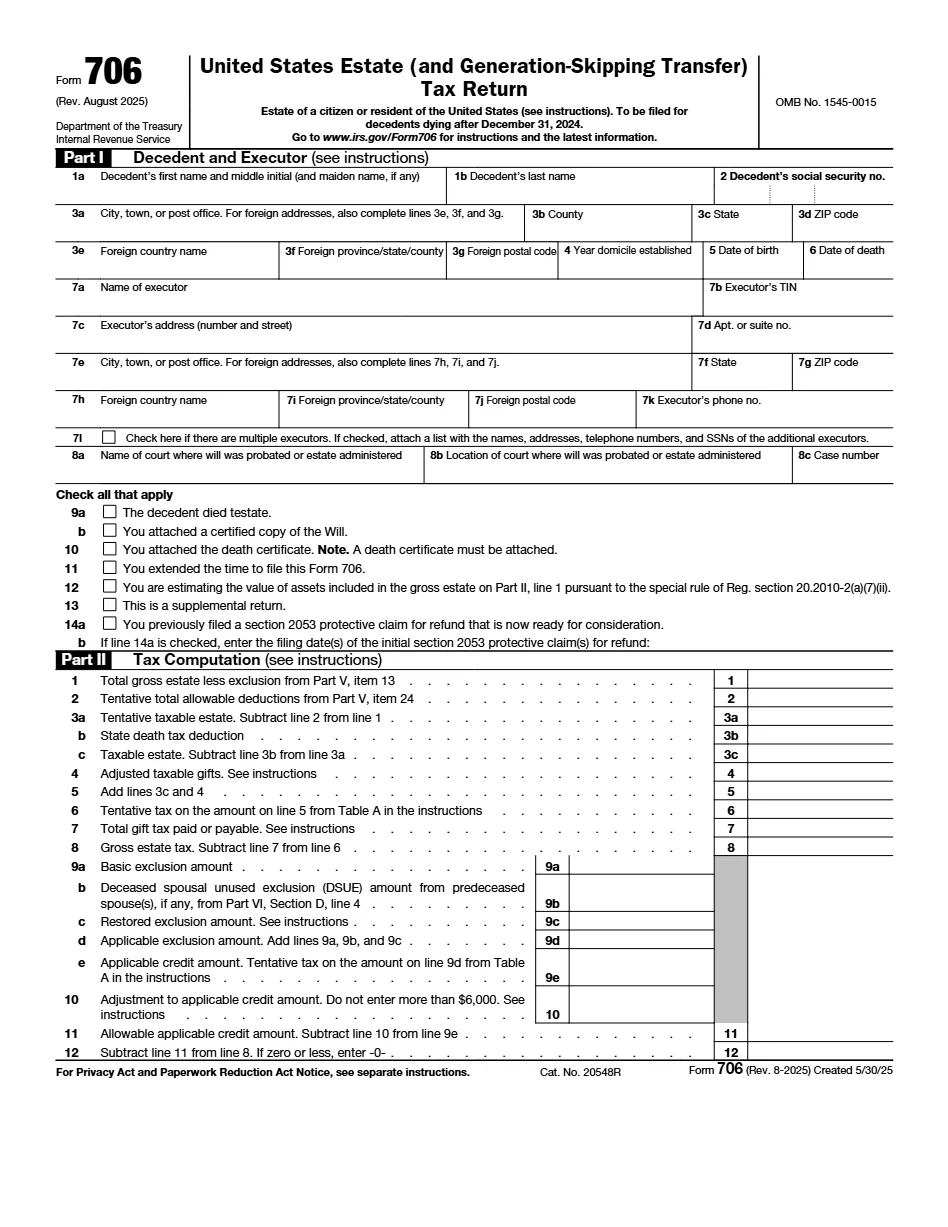
What value standard applies to a vehicle reported on Form 706?
At its retail-equivalent fair market value on the date of death: what it would cost to buy a comparable vehicle under normal market conditions, not a trade-in quote or quick-sale price. The appraisal must be retroactive, using pricing data and comparable sales from around the date of death rather than the market on the day the report is prepared.
Does a vehicle on Form 706 need a qualified appraisal?
When a vehicle is reported above roughly $5,000, the IRS expects a qualified appraisal substantiating the figure rather than a bare pricing-guide number. Generic guide values that ignore the exact trim, mileage, options, damage, or collector-market factors are the most common trigger for challenges from the IRS or from beneficiaries.
Why does the estate tax value matter when the car is later sold?
Because the estate's tax basis steps up to the date-of-death fair market value, and a subsequent sale is reported on Schedule D of Form 1041 using that basis. An undervalued car creates artificial capital gain on sale; an overvalued one can overstate the gross estate. The appraisal therefore controls two tax outcomes, not one.
What documentation ties the value to the specific car?
The VIN, year, make, model, trim, mileage, options, condition notes, and photos, matched to period pricing-guide printouts or comparable sales. Probate courts and the IRS expect the inventory and accounting to reconcile the exact vehicle to the value used, and our reports verify the VIN and grade condition so the figure survives scrutiny even in estates below the filing threshold.