What value applies when you gift a car?
The fair market value on the date of the gift, and specifically the retail price a member of the public would pay for a comparable car. Treasury Regulation 25.2512-1 uses the automobile as its example and expressly rejects dealer trade-in, wholesale, and auction prices as the benchmark, which is the single most common valuation mistake in car gifts.
When does gifting a car require Form 709?
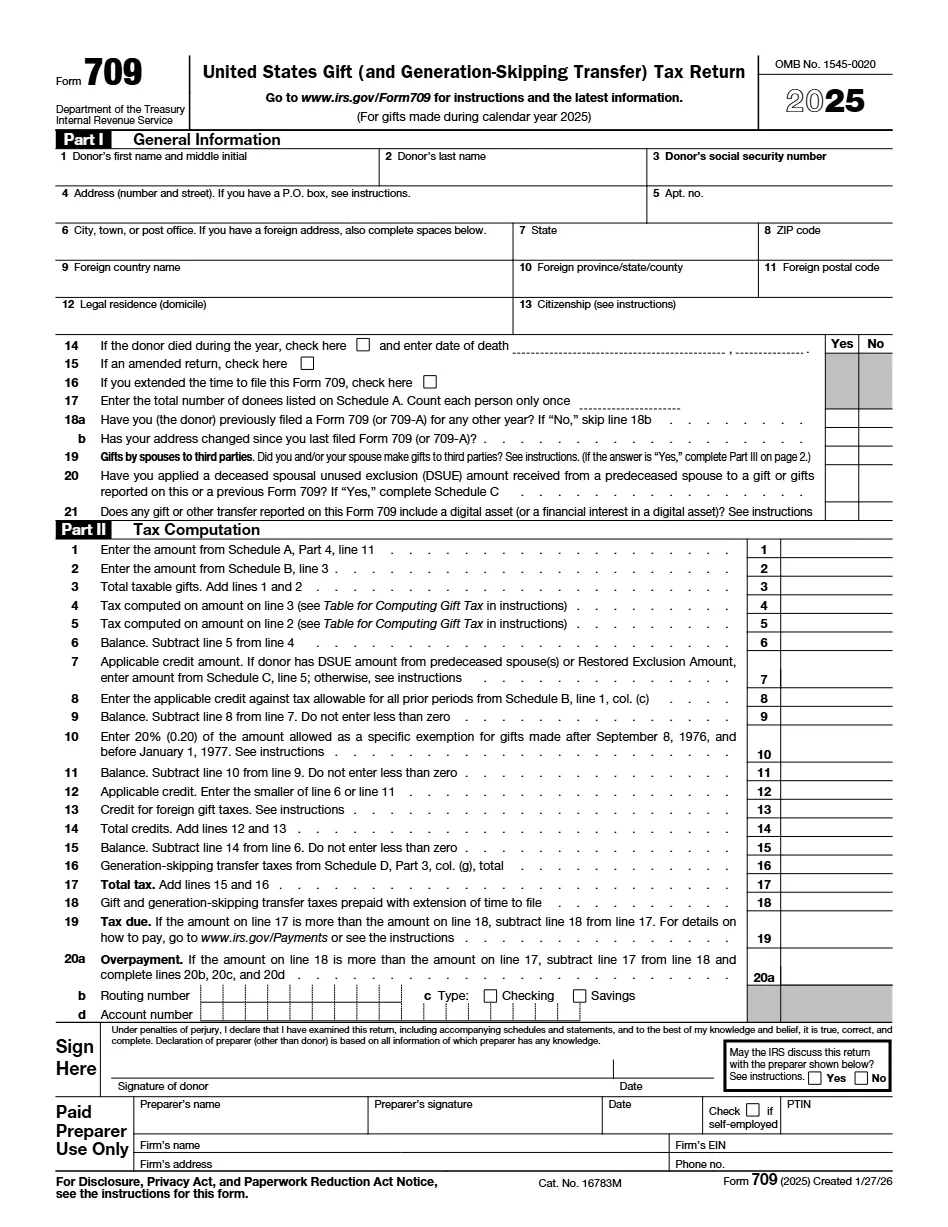
Whenever the car's fair market value to one recipient exceeds the annual exclusion, which was $18,000 for 2024 and $19,000 for 2025. The donor, not the recipient, files the return, and older articles citing fixed limits like $14,000 or $15,000 reflect prior-year exclusions that no longer apply.
Is a pricing-guide printout enough documentation?
For a standard passenger car, yes: a Kelley Blue Book, Edmunds, or NADA printout dated at the transfer, configured with the correct mileage, options, and condition, is generally sufficient. Classic, luxury, or heavily modified vehicles worth more than about $5,000 are the exception, where a formal appraisal is the expected support; vehicles donated to charity above $5,000 require a qualified appraisal.
Do state DMV values control the federal gift value?
No. States can apply their own presumptive values for motor vehicle transfer taxes, such as the standard presumptive value Texas uses for private-party transfers, and these figures can differ from the federal fair market value standard. The federal Form 709 value must still follow the retail-market test in the federal regulations.