Mobile Home Appraisal for Bankruptcy Filing

5.0from 80+ client reviews

Mobile home appraisals for bankruptcy filing, prepared in accordance with USPAP. AppraiseItNow provides USPAP-compliant valuations that clarify personal versus real property status, helping protect equity through trustee review.

Get an instant response

DEFENSIBLE, USPAP-COMPLIANT MOBILE HOME APPRAISAL REPORTS — QUALIFIED FOR THE IRS, AUDITORS, AND THE COURTS.

  • IRS
  • GASB
  • United States Courts
  • U.S. Small Business Administration
  • Chase
  • Bank of America
  • Wells Fargo

The vehicle team behind your valuation report

Between them, our vehicle appraisers hold CAGA designations, and every report is written to USPAP for the IRS, auditors, and the courts.

Joe Kattan

Joe Kattan

Owner & CEO

Joe founded AppraiseItNow to make a certified, USPAP-compliant appraisal as simple to order as anything else online. A former Bain & Company strategy consultant, Joe leads the entire team and specializes in strategy, growth, and the firm's tech capabilities.

Jason Dolph

Jason Dolph

Machinery & Equipment Appraiser

Third-generation auctioneer and CAGA Certified Appraiser with more than 20 years valuing machinery, equipment, vehicles, business assets, and estates for banks, attorneys, and trustees across the Carolinas.

Marnie Erkelens

Marnie Erkelens

Vehicle Appraiser

CAGA Certified Appraiser since 2014, covering vehicles, boats, equipment, fine art, and collectibles. A classic-car restoration background informs her vehicle work, with reports prepared for insurance, divorce, and charitable contributions.

Aron Blue

Aron Blue

Client Success Manager

Manages each engagement from the first enquiry to the delivered report, and keeps you posted at every step along the way.

  • USPAPWritten to the Uniform Standards of Professional Appraisal Practice
  • Rev. Rul. 59-60 and ASC 820The valuation framework the IRS, auditors, and courts test a business value against
  • Certified Appraisers Guild of AmericaCertified Appraiser
  • The Appraisal FoundationAuthorized by Congress as the source of appraisal standards

Mobile Home Appraisals for Bankruptcy Filing

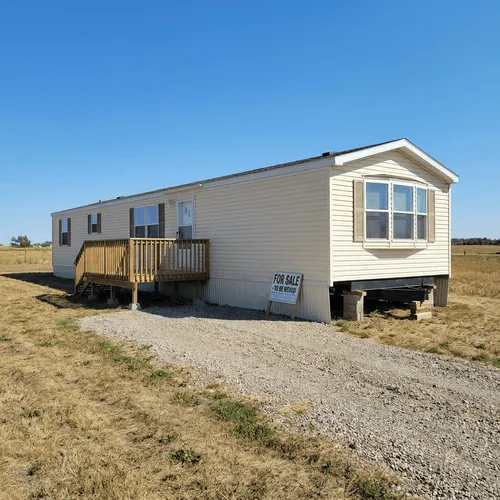
AppraiseItNow provides USPAP-compliant mobile and manufactured home appraisals specifically prepared for bankruptcy proceedings, covering both Chapter 7 liquidation and Chapter 13 reorganization cases. These appraisals establish the fair market value of the home as of the petition date, which is required for accurate completion of Schedule A/B and for supporting exemption claims, cramdown calculations, or trustee review. Whether the home is titled as personal property or has been converted to real property through affixation, our manufactured housing valuation team has the specialized experience to address the classification correctly.

We deliver appraisals both online and onsite across the United States, working directly with debtors, attorneys, and trustees to meet court deadlines. Our bankruptcy filing support includes full narrative reports that clearly define the applicable value standard, document the methodology used, and withstand creditor challenges or cross-examination.

Mobile Home Types We Appraise for Bankruptcy Cases

AppraiseItNow appraises a wide range of factory-built housing configurations commonly encountered in bankruptcy schedules.

  • Single-wide manufactured homes titled as personal property on leased land
  • Double-wide manufactured homes on owned lots, with or without affixation to a permanent foundation
  • Triple-wide and multi-section manufactured homes with complex title histories
  • HUD-code manufactured homes built after June 15, 1976
  • Pre-HUD mobile homes (built before 1976) with documented title and condition records
  • Manufactured homes in mobile home parks or land-lease communities
  • Homes subject to chattel loans or personal property financing agreements
  • Manufactured homes where a homestead declaration has been recorded pre-petition
  • Homes with deferred maintenance, storm damage, or significant depreciation affecting equity calculations
  • Manufactured homes with recent improvements or additions that may affect value relative to outstanding liens

How Our Bankruptcy Appraisal Process Works for Mobile Homes

Clients and their attorneys can expect a structured, transparent process from intake through final report delivery.

  • Appraisers credentialed through ISA, ASA, AAA, CAGA, AMEA, or NEBB conduct each assignment, with specific experience in manufactured housing and bankruptcy-context valuations
  • The appraisal report identifies the home's property classification (personal property vs. real property), defines the applicable value standard, and documents the comparable sales or cost approach methodology used to support the conclusion
  • Reports are formatted for court submission and include the petition-date value, a clear description of the subject property, and all data sources relied upon, making them suitable for Schedule A/B completion, exemption disputes, or cramdown negotiations
  • Delivery is available online for most assignments, with onsite inspection available where physical condition, affixation status, or creditor scrutiny requires direct observation

What clients say we are known for

AppraiseItNow Reviews: “They were wonderful to work with”

  1. Answering fast, and staying reachable while the work runs“From the start they were very responsive, price competitive” Chris S.Mentioned in 34 reviews
  2. Showing the research and the comparables behind the number“Very thorough and professional — great communication and outstanding service” Curt B.Mentioned in 29 reviews
  3. Delivering the finished report ahead of the deadlineMentioned in 21 reviews
  4. Taking on items other appraisers had already turned downMentioned in 14 reviews
  5. Following the regulatory guidelines the IRS and the courts requireMentioned in 11 reviews

Across 80+ published AppraiseItNow reviews the picture is consistent: every one is from a client who paid us for an appraisal, and the three things they raise most often are that they would hire us again, how quickly we answer, and how much research is visible in the report.

  • I was in dire need of an appraisal for my father's mobile home, which he needed for Medicaid approval. I couldn’t find anyone to do it for a long time, but then I found this company online and decided to give them a try. I’m so glad I did. They were wonderful to work with. I sent the pictures, and within just a few days I received the appraisal. They are absolutely worth the money.
    Kevin N. , Wellsburg, NY ·

    Mobile Home Appraisal

  • From the start they were very responsive, price competitive, and had a quick turn around time. Thank you so much to Joe who was very sweet in responding to my emails; I am looking forward to utilizing AppraiseItNow for many years to come.
    Chris S., San Clemente, CA ·
  • Very thorough and professional — great communication and outstanding service. Highly impressed with their work!
    Curt B. , Washington, UT ·

Frequently Asked Questions on Mobile Home Appraisals for Bankruptcy Filing

What standard values a mobile home in Chapter 7 or Chapter 13?

Replacement value under 11 U.S.C. Section 506(a)(2): the price a retail merchant would charge for a home of like age and condition as of the petition date. Courts apply this retail standard, following the Supreme Court's Rash decision, and reject wholesale or auction figures when the debtor keeps the home.

What evidence do bankruptcy courts rely on for mobile home values?

The NADA Manufactured Housing Appraisal Guide is the workhorse; courts have set values largely from NADA data when competing appraisals conflict. Dealer retail quotes, VIN-specific identification, condition photos, and appraisal reports round out the record, and judges will adjust an appraiser's figure for age, condition, and comparable retail evidence.

Does the bankruptcy value include the land, delivery, or setup?

Often not. When the lender's lien covers only the home itself, courts limit the secured claim to the box value of the unit, excluding value attributable to its location, and have excluded delivery and setup costs from replacement value when the debtor retains the home. That distinction can shrink the secured claim substantially.

Why does the appraisal matter so much in a cramdown?

Because it caps the secured claim. If a debtor owes far more than the home is worth, a Chapter 13 plan can pay the appraised replacement value over the plan term while the balance is treated as unsecured, so lenders contest the valuation and its NADA inputs closely, and the exemption analysis may separately turn on fair market value.