Boat Appraisal for Loan Collateral

5.0from 80+ client reviews

Boat appraisals for loan collateral, prepared in accordance with USPAP. AppraiseItNow provides certified marine valuations covering hull condition, comparable sales, and title status to support loan approval and favorable LTV terms.

Get an instant response

DEFENSIBLE, USPAP-COMPLIANT BOAT APPRAISAL REPORTS — QUALIFIED FOR LENDERS, BANKS, AND SURETY COMPANIES.

  • U.S. Small Business Administration
  • Chase
  • Bank of America
  • Wells Fargo
  • U.S. Bancorp
  • IRS

The marine team behind your collateral appraisal

Between them, our marine appraisers hold CAGA designations, and every report is written to USPAP for lenders, banks, and surety companies.

Joe Kattan

Joe Kattan

Owner & CEO

Joe founded AppraiseItNow to make a certified, USPAP-compliant appraisal as simple to order as anything else online. A former Bain & Company strategy consultant, Joe leads the entire team and specializes in strategy, growth, and the firm's tech capabilities.

Marnie Erkelens

Marnie Erkelens

Vehicle Appraiser

CAGA Certified Appraiser since 2014, covering vehicles, boats, equipment, fine art, and collectibles. A classic-car restoration background informs her vehicle work, with reports prepared for insurance, divorce, and charitable contributions.

Aron Blue

Aron Blue

Client Success Manager

Manages each engagement from the first enquiry to the delivered report, and keeps you posted at every step along the way.

  • USPAPWritten to the Uniform Standards of Professional Appraisal Practice
  • Fair market and liquidation valueThe collateral values lenders and surety companies underwrite against
  • Certified Appraisers Guild of AmericaCertified Appraiser
  • The Appraisal FoundationAuthorized by Congress as the source of appraisal standards

Boat Appraisals for Loan Collateral

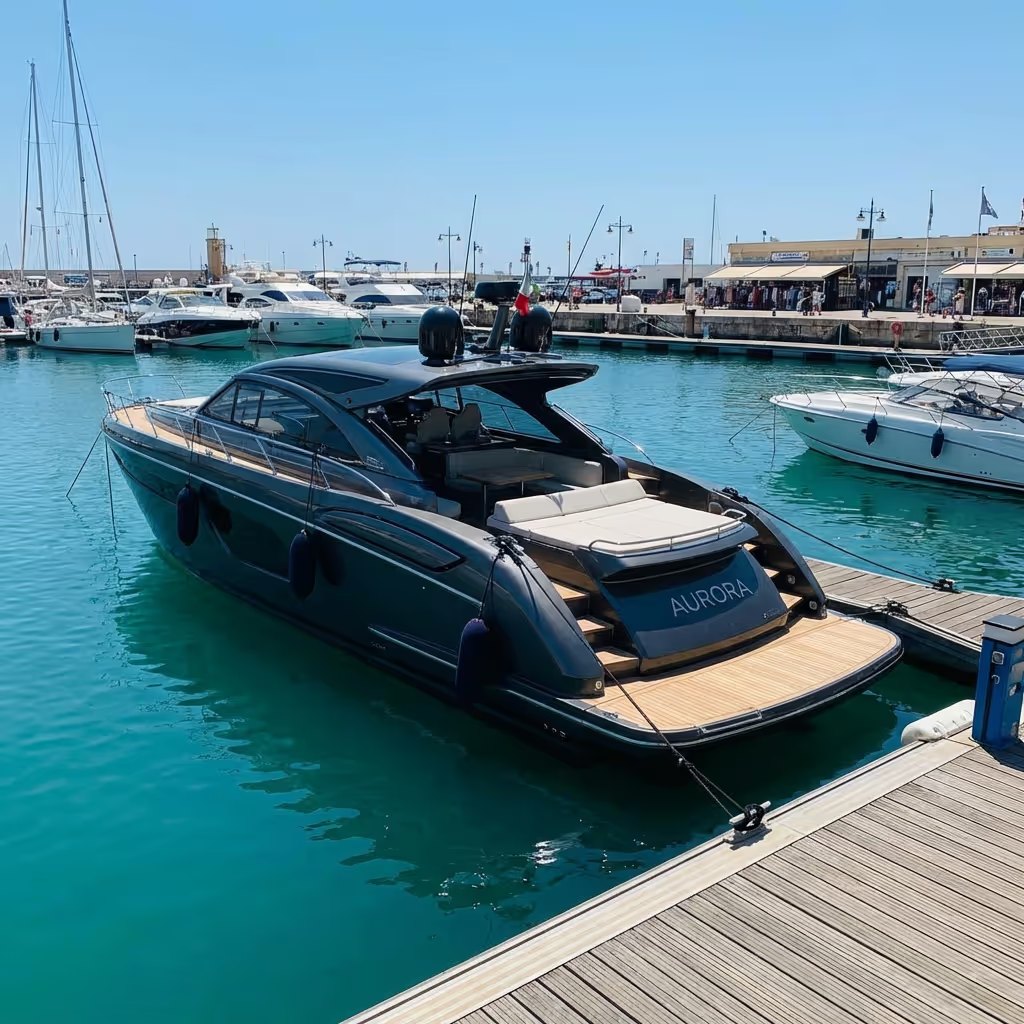
When a lender requires a vessel as security for a loan, an independent appraisal establishes the fair market value that determines how much the lender is willing to extend and at what loan-to-value ratio. Boats over 30 feet, vessels with complex systems, and higher-risk cases such as salvaged or older project boats typically trigger a full appraisal during underwriting. For federally documented vessels, lenders also rely on the appraisal to support a preferred mortgage filed under 46 U.S.C. with the U.S. Coast Guard, which requires the vessel to be identified by name and official hull number and the loan amount to be specified. Our vessel appraisal team covers all of these scenarios with credentialed, independent appraisers.

AppraiseItNow delivers both online and onsite appraisals, working directly with borrowers, marine lenders, and credit unions throughout the underwriting process. Our boat loan collateral appraisal services produce written reports that satisfy lender documentation requirements and banking regulatory standards.

Boats We Appraise for Loan Collateral

AppraiseItNow appraises a wide range of vessel types that lenders commonly accept as collateral.

  • Fiberglass powerboats, including center consoles, bowriders, and express cruisers
  • Aluminum fishing boats and jon boats used for freshwater and inshore applications
  • Pontoon and deck boats, including those with upgraded engine packages
  • Sailboats, including coastal cruisers and offshore bluewater vessels
  • Trawlers and motoryachts over 30 feet requiring detailed mechanical and structural review
  • Personal watercraft such as jet skis and wave runners pledged as secondary collateral
  • Houseboats and liveaboard vessels with complex onboard systems
  • Salvaged, rebuilt, or project boats requiring condition-specific valuation and repair cost documentation
  • Commercial fishing vessels and charter boats used in business operations
  • Vintage and classic wooden boats where provenance and restoration quality affect value significantly

How AppraiseItNow Handles Boat Loan Collateral Appraisals

Our appraisers inspect hull condition, mechanical systems, engines, electronics, and any modifications or upgrades, then cross-reference findings against recent comparable sales data to produce a credible opinion of value.

  • Reports include a full description of the vessel, condition assessment, comparable market data, and a clearly stated value conclusion that lenders can use to set LTV ratios and complete underwriting.
  • Appraisers are credentialed through recognized professional organizations including ISA, ASA, AAA, CAGA, AMEA, and NEBB, and all reports are prepared in compliance with USPAP standards, satisfying the independence requirements that banking regulators expect.
  • Clients receive a written, signed appraisal report suitable for submission to marine lenders, credit unions, and SBA-affiliated lenders, with turnaround times designed to keep loan timelines on track.
  • Both onsite inspections and desktop appraisals using client-supplied documentation, photos, maintenance records, and vessel specifications are available depending on lender requirements and vessel complexity.

What clients say we are known for

AppraiseItNow Reviews: What Clients Say About AppraiseItNow

  1. Answering fast, and staying reachable while the work runs“From the start they were very responsive, price competitive” Chris S.Mentioned in 34 reviews
  2. Showing the research and the comparables behind the number“Very thorough and professional — great communication and outstanding service” Curt B.Mentioned in 29 reviews
  3. Delivering the finished report ahead of the deadlineMentioned in 21 reviews
  4. Taking on items other appraisers had already turned downMentioned in 14 reviews
  5. Being the appraiser they come back toMentioned in 44 reviews

Across 80+ published AppraiseItNow reviews the picture is consistent: every one is from a client who paid us for an appraisal, and the three things they raise most often are that they would hire us again, how quickly we answer, and how much research is visible in the report.

  • AppraiseItNow helped us appraise a very unique set of propulsion boats. Service was top notch and provided incredible value for the cost!
    Austin S., San Francisco, CA ·

    Boat Appraisal for Loan Collateral

  • Very straightforward and efficient way to gain a quality certified boat appraisal. I will suggest AppraiseItNow to all my boating friends!
    Michael L., Wake Forest, NC ·

    Boat Appraisal for Loan Collateral

  • From the start they were very responsive, price competitive, and had a quick turn around time. Thank you so much to Joe who was very sweet in responding to my emails; I am looking forward to utilizing AppraiseItNow for many years to come.
    Chris S., San Clemente, CA ·
  • Very thorough and professional — great communication and outstanding service. Highly impressed with their work!
    Curt B. , Washington, UT ·

Frequently Asked Questions on Boat Appraisals for Loan Collateral

How do marine lenders value a boat offered as collateral?

From the wholesale side: NADA Marine, BUC, and sold-boat data adjusted for age, condition, and recent comparable sales, not advertised asking prices, which lenders explicitly reject as overstating what a repossessed vessel would bring. Our loan collateral appraisals document condition and comparables in a USPAP-compliant report written for exactly this audience.

What loan-to-value should a boat owner expect?

Secured boat loans commonly cap at roughly 70 to 80 percent of appraised value, and some consumer lenders advance only 40 to 60 percent of resale value while expecting the owner to hold 20 to 30 percent equity. The conservative structure reflects disposition costs and market declines the lender absorbs in a default.

When is a marine survey required for boat financing?

For larger or complex vessels, lenders often require a current survey, frequently within the last 12 months, plus a formal appraisal, particularly above thresholds like $100,000 or when the vessel is specialized. Regulated lenders must use USPAP-conforming appraisals when standard guides cannot reliably value the collateral.

What documentation problems can derail a boat collateral loan?

Mismatched hull identification numbers, unclear title or Coast Guard documentation, and undisclosed prior liens, any of which can block or subordinate the lender's security interest. Lenders also typically require insurance at full market value with a hull deductible capped around 2 percent, so an agreed value below the appraisal can hold up closing.