How is a gifted business interest valued for gift tax?
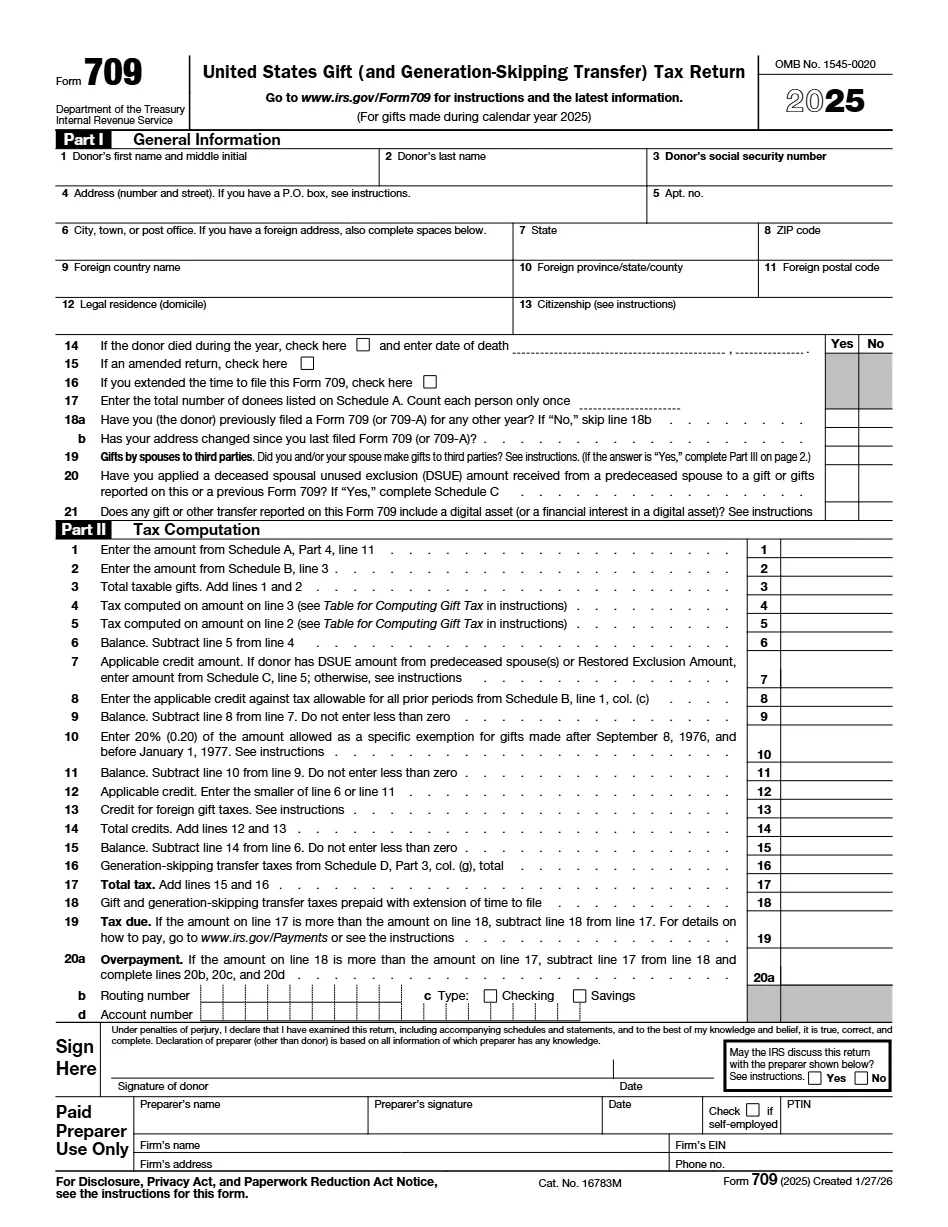
At fair market value on the date of the gift, as required by IRC Section 2512: the price a hypothetical willing buyer would pay a willing seller, both reasonably informed and neither compelled. That date-specific value is the amount reported on Form 709, and later company performance generally cannot reset it.
Does the price a family member pays set the taxable value?
No. The hypothetical buyer is not presumed to be the donor's child, so below-market family pricing does not reduce the reportable gift. The difference between fair market value and what the donee actually pays is itself treated as the taxable gift, which is why the IRS routinely challenges values based on intra-family transaction prices.
When does a gifted interest need a formal valuation report?
Whenever the transfer to one recipient exceeds the annual exclusion ($19,000 per recipient for 2025), practitioners expect a documented qualified appraisal supporting the Form 709 value, since closely held interests have no quoted market price. A bare number without a compliant report covering methods, assumptions, and the valuation date is a common audit vulnerability.
How does the IRS review gift tax business valuations?
IRS engineers apply the Business Valuation Guidelines in Internal Revenue Manual 4.48.4, checking whether the report addresses the eight Revenue Ruling 59-60 factors, justifies its choice among market, income, and net asset approaches, and supports any discounts for lack of control or marketability with empirical evidence. Minority-interest discounts are the most frequently contested item.