
Residential Personal Property Appraisal for Loan Collateral
Household personal property appraisal for loan collateral, covering upholstered and case furniture, dining and bedroom suites, wall décor and outdoor equipment pledged against a facility. AppraiseItNow inspected an Arizona residence on site, photographing and cataloguing the contents before researching comparable sales in the resale channels where each category clears.
Project Overview
Assignment Summary
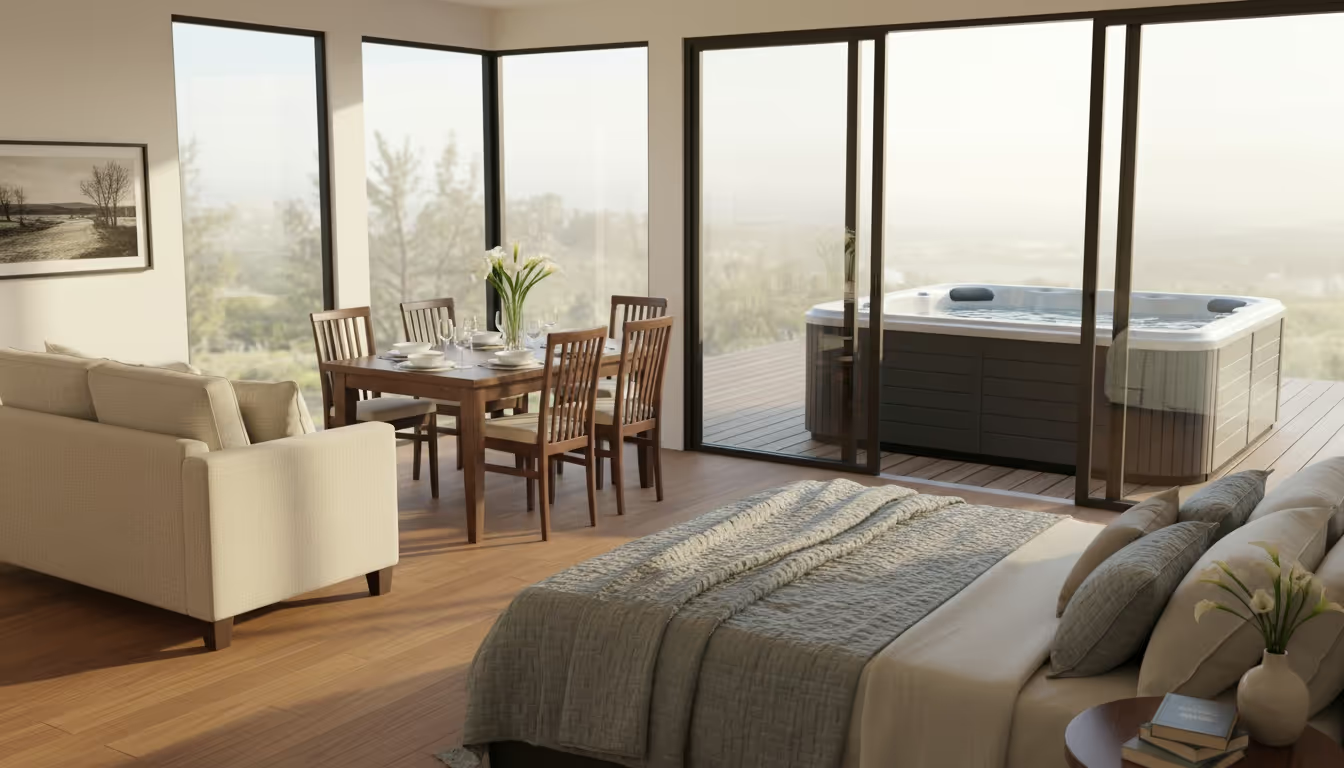
The scope of work encompassed an onsite inspection of tangible personal property, comprehensive photographic documentation, market research for comparable sales, and analysis to conclude fair market value for loan collateral purposes. Subject assets included household furnishings such as upholstered seating, dining and bedroom furniture, occasional tables, wall décor, and outdoor equipment including a manufactured hot tub unit. The sales comparison approach was employed to develop value conclusions based on the market where these items are commonly bought and sold. The appraisal was prepared in conformance with professional appraisal standards and included assignment-specific assumptions and limiting conditions communicated to the client.
Challenges
Our Approach
Project Outcome
Ready to start your appraisal?
Tell us the asset and what the value is for, and we will confirm scope, timing, and a fixed fee before any work begins.
Request an AppraisalFrequently Asked Questions
Can household furnishings actually serve as loan collateral?
They can, though lenders advance conservatively against them because the resale market for used furnishings is shallow and disposal costs are real. Where household property is pledged, the lender generally wants a liquidation premise rather than fair market value. Knowing which premise the lender requires before the engagement starts avoids delivering a report the lender cannot use.
Why does an on-site inspection matter more for collateral than for other purposes?
Because the lender needs to know the property exists, is where it is said to be, and is in the condition claimed. A desktop appraisal of pledged collateral verifies none of those. On-site work produces a photographed, catalogued record tied to a location and a date, which is what makes the collateral schedule something a lender can rely on.
How is a wide range of ages and conditions handled in one household?
Item by item, with condition recorded and adjustments made individually. A residence typically holds nearly new pieces alongside heavily used ones, and averaging across them produces a figure that describes nothing. Grouping by category and then adjusting within the group keeps the schedule usable without pretending the contents are homogeneous.
What happens to items with almost no resale market?
They are reported at nominal value and identified as such. Mass-market furniture, built-in fixtures and personalized items frequently cost more to move and sell than they return. Being explicit about this protects the lender from an inflated borrowing base and protects the borrower from an expectation that will not survive a liquidation.