
Suite Ticket Donation Appraisal for Tax Deduction
Luxury suite donation appraisal for a noncash charitable tax deduction, covering private venue suites, VIP access packages and hospitality inventory donated to a qualified nonprofit. AppraiseItNow appraised three private suite packages at an Austin, Texas entertainment and sports venue, weighing documented purchase prices against comparable public offerings for concert and collegiate events.
Project Overview
Assignment Summary
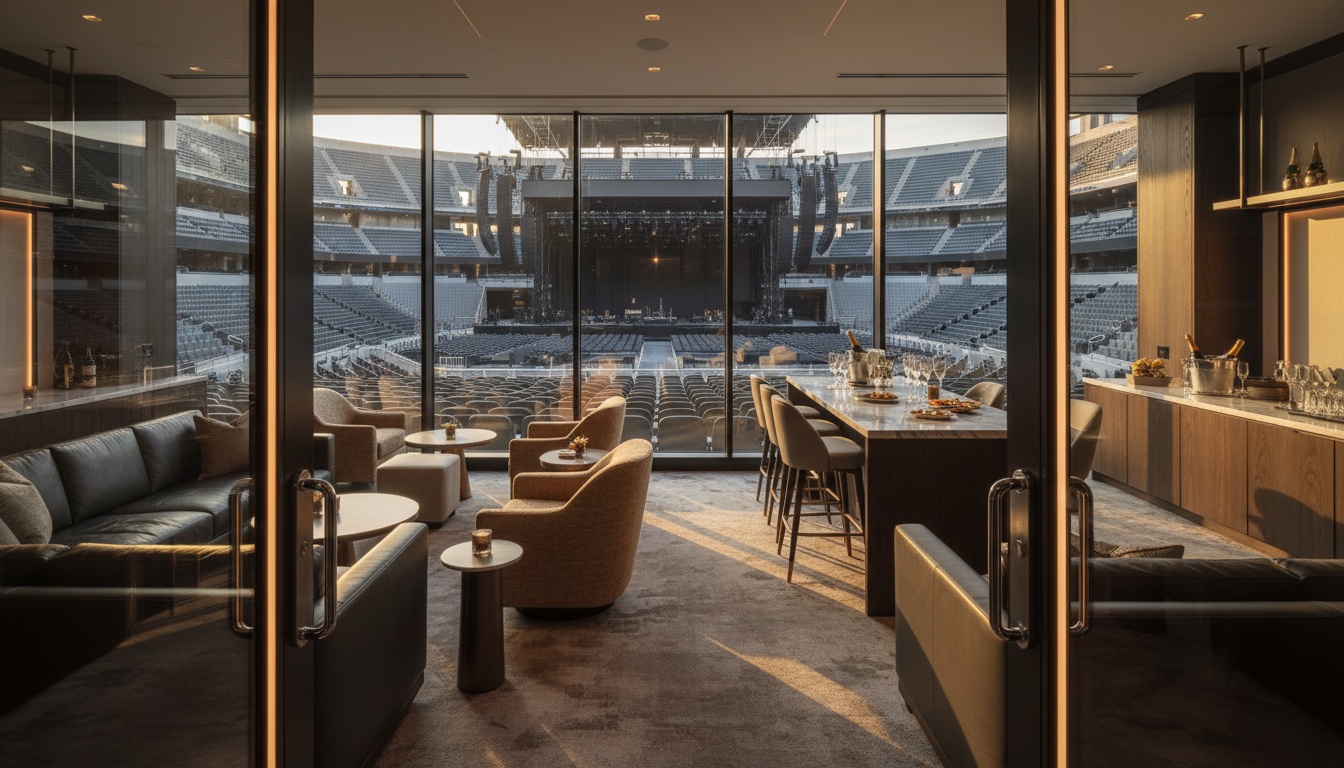
The client donated three private luxury suite packages to a qualifying nonprofit organization and needed a qualified appraisal to substantiate the fair market value of the donated property for federal tax reporting purposes. The suites were located at a premier entertainment and sports venue in Austin, Texas, and each package included VIP entrance access and exclusive seating for groups ranging from 16 to 20 guests across concert and collegiate sporting events. The appraisal was prepared in compliance with ISA appraisal standards and USPAP, meeting the IRS definition of a qualified appraisal under Treasury Regulation §1.170A-16-17 and consistent with IRS Publications 526 and 561. A pre-filled IRS Form 8283 was completed and included with the report to directly support the donor's charitable donation appraisal tax filing.
Challenges
One of the key challenges in this assignment was establishing fair market value for luxury suite packages, which are not frequently traded on an open secondary market in the way that standard event tickets are. Suite pricing is driven by a combination of event type, artist or team popularity, and venue exclusivity, which can make sourcing direct comparable sales difficult. Additionally, because the effective date of donation preceded the report preparation date, particular care was required to ensure that all values accurately reflected market conditions as of the correct point in time rather than at the time of writing.
Our Approach
The appraiser applied a market-based approach, with weight given to the documented original purchase prices of the suite packages, which were supported by receipts provided by the client. To further validate each value, the appraiser cross-referenced publicly available pricing data for comparable suite rentals at major venues hosting similar concert and sporting events. Fair market value was defined in accordance with ISA standards and consistent with IRS guidelines, ensuring full compliance with the personal property appraisal substantiation requirements under Treasury Regulation §1.170A-16-17.
Project Outcome
The engagement produced a fully IRS-compliant qualified appraisal report with an itemized breakdown of each suite package and a completed IRS Form 8283, giving the client a well-documented, straightforward path to filing their charitable contribution. This personal property for charitable donation engagement gave the client confidence that their noncash donation was properly valued and reported in accordance with federal requirements. Donors seeking personal property appraisers in Texas can rely on this same rigorous process for their own noncash contribution filings.
Ready to start your appraisal?
Tell us the asset and what the value is for, and we will confirm scope, timing, and a fixed fee before any work begins.
Request an AppraisalFrequently Asked Questions
How is a luxury suite package valued when suites rarely resell?
By combining documented acquisition cost with evidence from comparable offerings at the same and similar venues. Suites are sold by venues and rights holders rather than traded on a secondary market, so the analysis works from primary market pricing for equivalent packages on comparable event dates. Receipts establish what was paid; comparable offerings test whether that reflects the market.
Does the event itself change the value of a donated suite?
Substantially. A suite for a high-demand concert or a marquee collegiate matchup prices far above the same suite for a mid-week event, because demand for the event drives the package. The valuation is tied to the specific events included, and the report identifies them rather than reporting a generic per-suite figure.
What is included in a suite package for valuation purposes?
Whatever actually transferred, and it needs to be itemized: seat count, VIP entrance access, parking, catering credits and any hospitality inclusions. Packages vary widely in what they bundle, and a catering allowance or parking allocation is real value that a comparable analysis has to match. The report lists inclusions for each package appraised.
Is a donated ticket package treated as tangible personal property?
Tickets and hospitality packages are generally treated as intangible rights rather than tangible personal property, which means the related use rule that limits deductions on tangible property does not apply in the same way. It also means the charity's use of the package matters less to the deduction. The appraisal establishes fair market value under Treasury Regulation 1.170A-1(c)(2); the characterization belongs with the donor's tax advisor.