Which value premise applies to equipment in a bankruptcy case?
It depends on the chapter and the question before the court: Chapter 7 liquidations commonly use forced or orderly liquidation value, Chapter 11 reorganizations and negotiated Section 363 sales lean on orderly liquidation or going-concern values, and courts can direct value in use, value in exchange, or net realizable value for specific issues. One machine can carry several defensible numbers.
How is equipment valued for exemptions and retained collateral?
Exemption scheduling under Section 522 uses fair market value as of the petition date, while the Supreme Court's Rash decision values collateral a debtor keeps at replacement value: what a retail merchant would charge for property of that age and condition. Filing garage-sale or scrap numbers where the law requires a replacement-based value is a frequent trustee objection.
Why is mislabeling the premise so damaging?
Because forced liquidation value sits below orderly liquidation value, which sits below fair market value, a report using the wrong premise produces a number that is arithmetically sound but legally irrelevant. Creditors and debtors each prefer the premise that favors them, and courts focus on whether the premise matches the statutory question.
What should the appraisal file contain for a trustee or court?
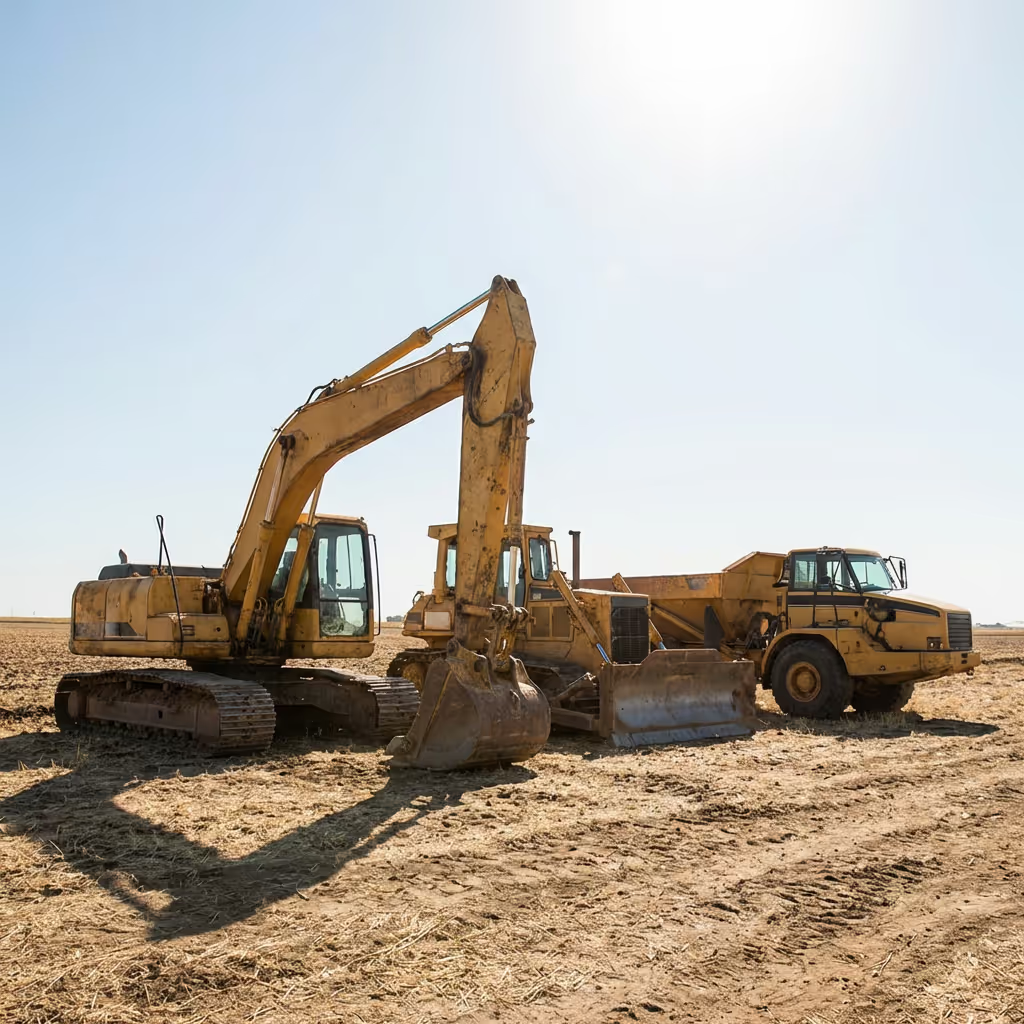
Serial-number-level identification, condition notes and photos, comparable sale and auction data, the valuation date, the stated premise, and any assumptions about dismantling, removal, or sale timing. Equipment value is highly sensitive to condition and marketability, so a bare estimate without that record rarely survives contested matters.