Does farm machinery have to be itemized on Form 706?
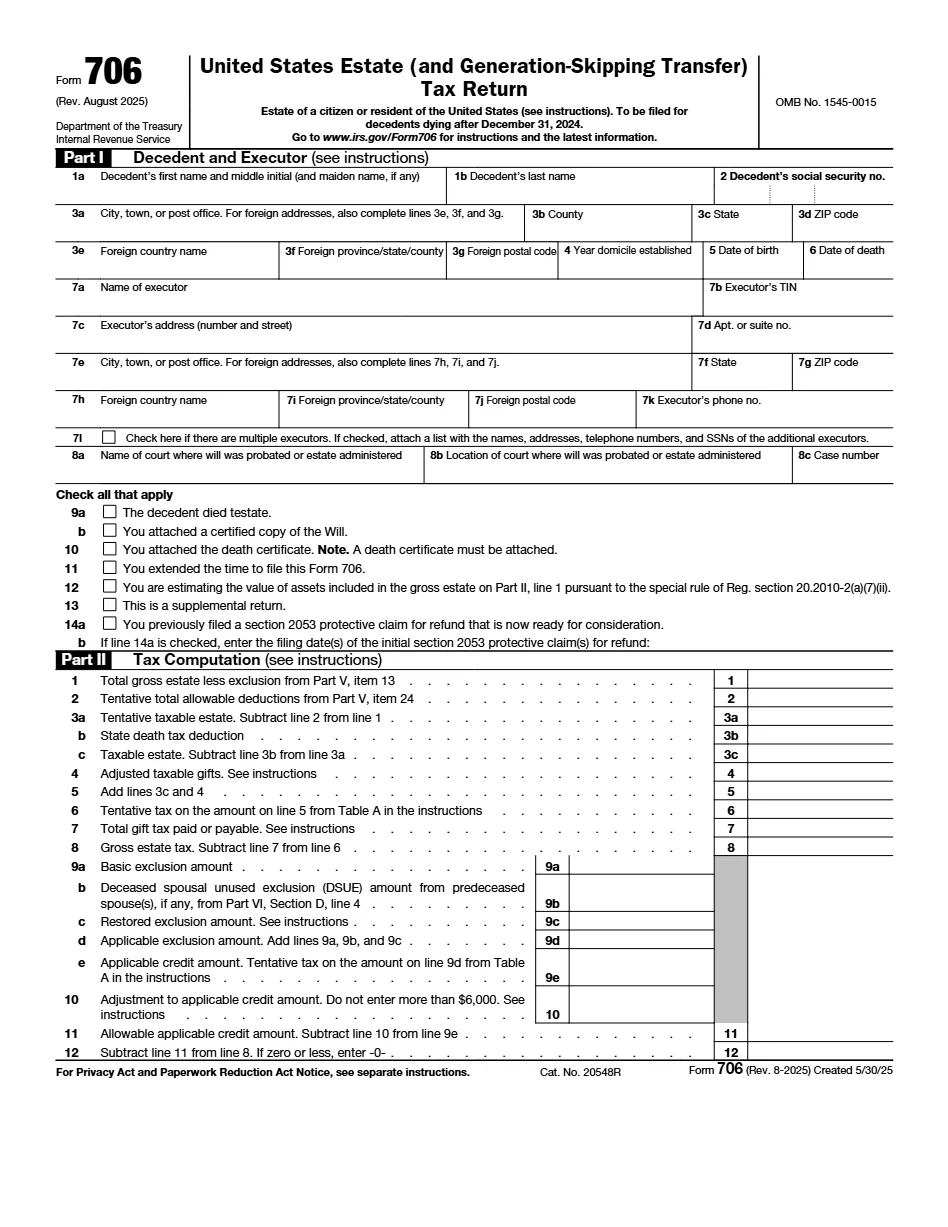
Yes. Treasury Regulation 20.2031-1(b) requires livestock, farm machinery, and crops to be itemized with each item separately valued at fair market value on the valuation date, and it prohibits using local property-tax assessments unless they equal fair market value. Lump-sum machinery figures without item detail are a standing IRS objection.
Can special use valuation lower the equipment values?
No, the IRC 2032A reduced-value formula applies only to qualifying real property. Machinery still matters to the election, though: tractors and combines count toward the requirement that at least half of the estate consist of farm or business property, so accurate equipment values help the land qualify even though the machines themselves stay at fair market value.
How do the reported values affect the heirs' taxes later?
They become the heirs' stepped-up basis: IRS Publication 225 confirms inherited property takes the fair market value from the estate valuation, and machinery is then depreciated from that figure. Undervaluing a combine on Form 706 hands the heir a smaller depreciation base and a larger gain on sale, so low numbers are not conservative.
What happens when an estate holds many similar machines?
An absorption analysis may be needed. Selling a fleet of similar tractors or irrigation units into the same market within a short period can depress per-unit prices, so multiplying one unit's value by the count can overstate realizable value. The appraisal should address market absorption explicitly, because the IRS disputes unsupported figures in both directions.