01
Household Goods & Personal Property
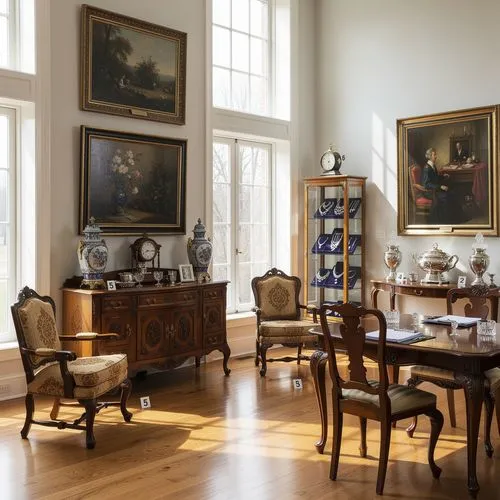
We determine fair market value for furniture and household contents: the price a willing buyer would pay a willing seller, with neither under pressure to act.
If you sent us a request between 28 July and 5 August, it did not reach us. A fault on our form stopped some messages from coming through. Please call (301) 820-7664 or fill the form again. We're sorry for the inconvenience.

Fair market value appraisal services covering personal property, equipment, vehicles, and business interests, prepared in accordance with IRS requirements and USPAP. AppraiseItNow appraises furniture, kitchen appliances, RVs, semi trucks, and tools at fair market value.
…the company exceeded all of my expectations… They’re now my go to source for my collection
…provided strong, well-supported comparisons to justify their appraisal values
They diligently researched both equipment items and provided well-documented reports
DEFENSIBLE, USPAP-COMPLIANT APPRAISAL REPORTS — QUALIFIED FOR THE IRS, CPAS, AND FINANCIAL ADVISORS.






01
We determine fair market value for furniture and household contents: the price a willing buyer would pay a willing seller, with neither under pressure to act.
02
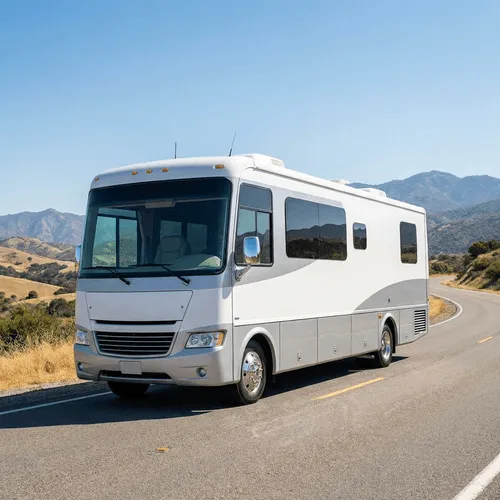
We appraise RVs and semi trucks at fair market value for sales, buyouts, tax and legal matters, using current market data for the specific make, model and condition.
03
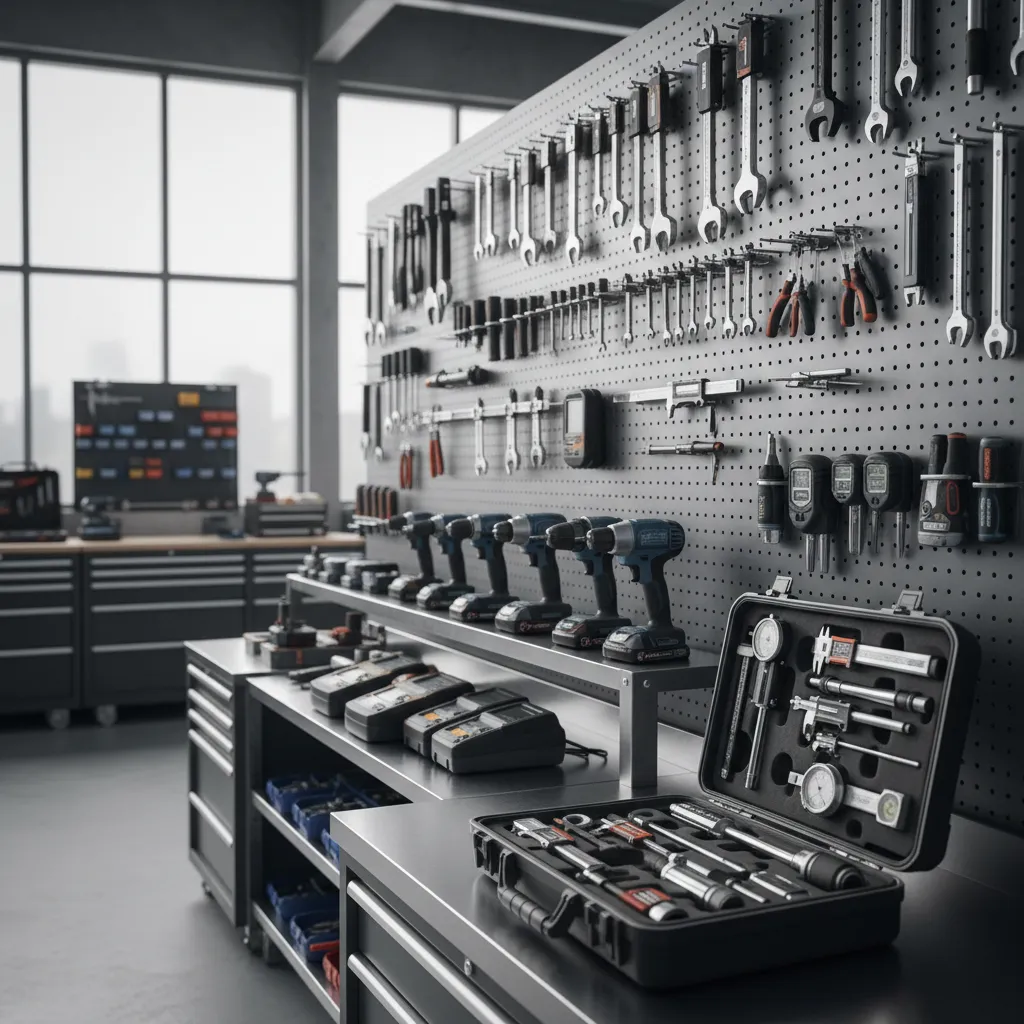
We value kitchen appliances, tools and small equipment at fair market value for resale, insurance and business transactions.

Owner & CEO
Joe founded AppraiseItNow to make a certified, USPAP-compliant appraisal as simple to order as anything else online. A former Bain & Company strategy consultant, Joe leads the entire team and specializes in strategy, growth, and the firm's tech capabilities.

Personal Property Appraiser
ISA Accredited Member with 30 years in the trade, from running estate sales and an auction gallery to appraising luxury apparel, furniture, artwork, antiques, and business assets, primarily for IRS tax filings.

Machinery & Equipment Appraiser
Third-generation auctioneer and CAGA Certified Appraiser with more than 20 years valuing machinery, equipment, vehicles, business assets, and estates for banks, attorneys, and trustees across the Carolinas.

Personal Property Appraiser
ISA Accredited Member specializing in Asian art, with a Master's from SOAS and a Postgraduate Diploma in Asian Art. Ashley chairs the ISA's Antiques, Furnishings, and Decorative Arts committee and appraises for charitable donation, insurance, and equitable distribution.

Vehicle Appraiser
CAGA Certified Appraiser since 2014, covering vehicles, boats, equipment, fine art, and collectibles. A classic-car restoration background informs her vehicle work, with reports prepared for insurance, divorce, and charitable contributions.
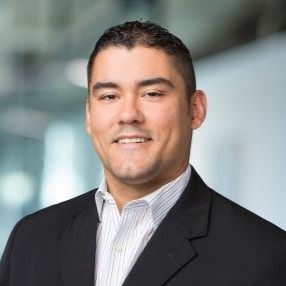
Business Valuation Expert & Appraiser
ASA, ABV, and CFA charterholder. Since 2016 Justin has valued businesses for estate and gift tax, purchase price allocations, fairness opinions, lending, and buy-sell agreements, across manufacturing, services, retail, and pre-revenue biotech.
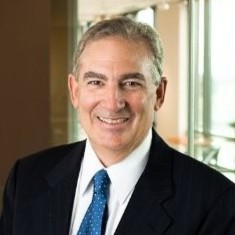
Business Valuation Expert & Appraiser
Accredited Senior Appraiser with the American Society of Appraisers. Raymond values capital stock, business enterprises, stock options, and intangible assets.

Client Success Manager
Manages each engagement from the first enquiry to the delivered report, and keeps you posted at every step along the way.
 International Society of AppraisersAccredited Member
 Certified Appraisers Guild of AmericaCertified Appraiser
 American Society of AppraisersAccredited Senior Appraiser
 The Appraisal FoundationAuthorized by Congress as the source of appraisal standards
A fair market value appraisal determines the price at which property would change hands between a hypothetical willing buyer and willing seller, both informed and acting without compulsion. FMV appraisals are required by the IRS for charitable property donations exceeding $5,000 (Form 8283), with full appraisal attachment required for business interests over $500,000. They also support estate tax filings, gift tax returns, ERISA plan compliance, and 409A valuations, following Treasury Regulation §20.2031-1(b), Revenue Ruling 59-60, and USPAP standards.
AppraiseItNow delivers qualified FMV appraisals online and onsite across the United States, covering personal property, equipment, vehicles, fine art, boats, business interests, and inventory. Our mission is to deliver defensible, USPAP-compliant valuations with exceptional speed, professionalism, and client service.
AppraiseItNow covers every major asset class that commonly requires a fair market value determination, including:
What clients say we are known for
Across 80+ published AppraiseItNow reviews the picture is consistent: every one is from a client who paid us for an appraisal, and the three things they raise most often are that they would hire us again, how quickly we answer, and how much research is visible in the report.
I was skeptical at first, but the company exceeded all of my expectations. The team responded quickly to every question, and the service was excellent. They’re now my go to source for my collection. I’ve used them twice already, and I plan to use them several more times.
Firearms Appraisal for Personal Use
Joe and his team were highly responsive and provided strong, well-supported comparisons to justify their appraisal values. The process of uploading photos was smooth and straightforward. We would definitely work with him again for future appraisal needs.
Antiques Appraisal for Personal Use
Extremely communicative, didn’t have to jump through hoops, loved their system and how easy it was to give them all the information. Highly recommend going with these guys, shout out to Joe too for being awesome to work with!
Trailer Appraisal for Personal Use
AppraiseItNow, Inc. was professional in every way. They were prompt, thorough, and provided impressive credentials that demonstrated their expertise. I highly recommend their services.
Antiques Appraisal for Personal Use
The staff at AppraiseItNow was exceptionally professional and attentive, ensuring a comfortable experience throughout the entire appraisal process.
Sports Memorabilia Appraisal for Personal Use
AppraiseItNow did an outstanding job appraising my 1998 Bobcat Skid Steer and circa 2010 Yuchai Crawler Dozer. We could not locate a serial number on the dozer, and there were no online sales available, but they were still able to develop an accurate appraisal using known specifications for my dozer compared to other comparable make and model dozers. They diligently researched both equipment items and provided well-documented reports.
Machinery & Equipment Appraisal
AppraiseItNow offers online appraisals and onsite appraisals in all 50 states.
FMV uses a hypothetical willing buyer and seller without compulsion, and often applies discounts for lack of control or marketability for private interests. Fair value under ASC 820 is an exit price between market participants and can produce materially higher results without those discounts. Using GAAP fair value instead of IRS FMV on a tax return can lead to disallowed deductions or penalties on forms like Form 8283.
Two common discounts apply to non-publicly traded interests. A discount for lack of control (DLOC) reduces value for minority stakes that lack voting power, typically 20 to 40%. A discount for lack of marketability (DLOM) accounts for illiquidity, typically 20 to 50%. Combined, these discounts can reduce value 30 to 60% compared to a controlling interest, consistent with Revenue Ruling 59-60.
The valuation date is the contribution date, meaning the date the property actually transfers, not the date an agreement is signed. This is defined under IRS Publication 561 and §1.170A-17. Using a later transaction date risks IRS adjustment if market conditions changed, which can result in a disallowed deduction.
A qualified appraisal under §1.170A-17 must include the property description, valuation and contribution dates, appraiser qualifications and fee, FMV, methodology, and supporting basis such as comparables or earnings. Omitting any of these elements voids the appraisal's qualified status and can trigger penalties of 20 to 40% under IRC §6662 for substantial or gross valuation misstatements.
FMV assumes hypothetical market participants without specific synergies, not actual strategic buyers, per Revenue Ruling 59-60 and §20.2031-1(b). Including strategic buyer premiums would overstate value relative to what a typical willing buyer would pay, which the IRS does not accept for tax reporting purposes.