Hawaii Equipment Appraisers

5.0 on Google110+ 5-star reviews

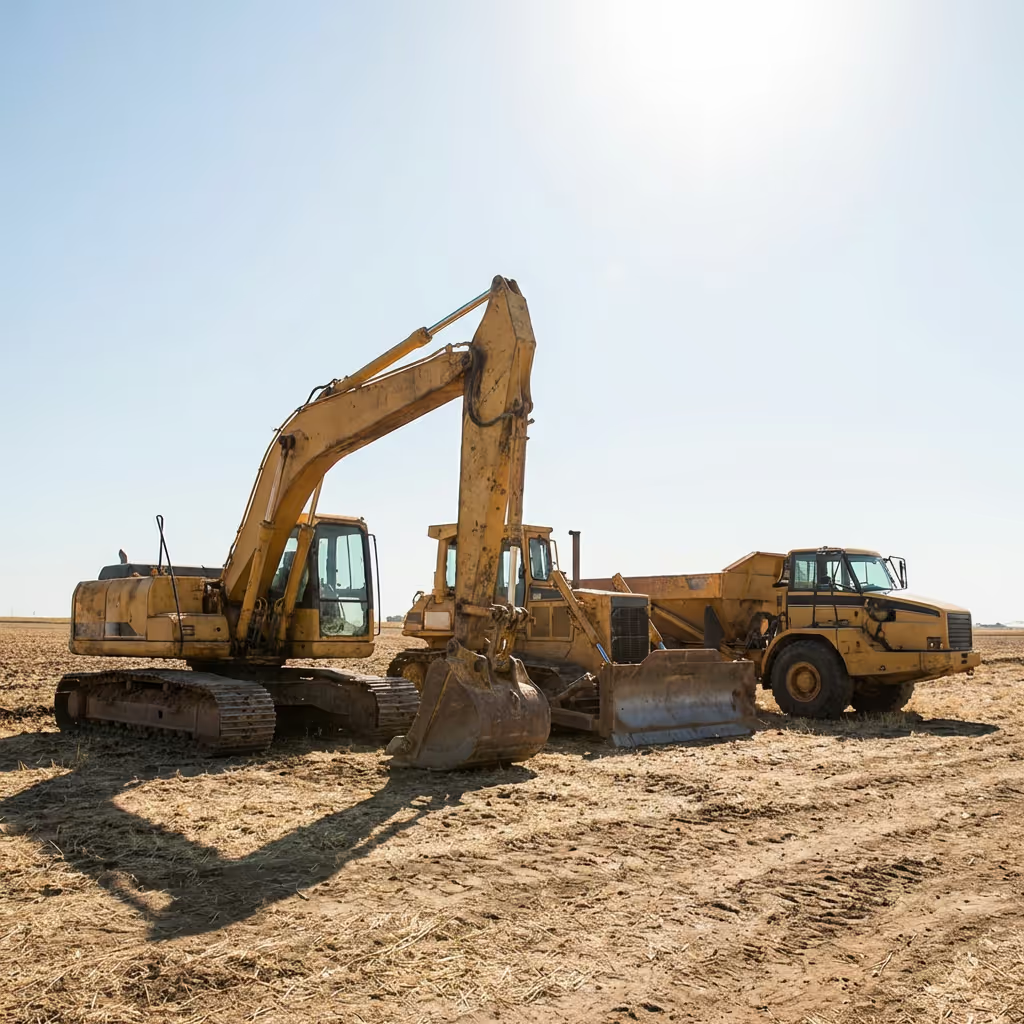
Equipment appraisals in Hawaii for donations, lending, M&A, and financial reporting, prepared in accordance with USPAP and IRS requirements. AppraiseItNow appraises industrial equipment, construction machinery, manufacturing assets, agricultural equipment, and fleet vehicles across Hawaii, including Honolulu, Hilo, and Kailua.

Get an instant response

DEFENSIBLE, USPAP-COMPLIANT MACHINERY & EQUIPMENT APPRAISAL REPORTS — QUALIFIED FOR THE IRS, HAWAII COURTS, LENDERS, INSURERS, AND MORE.

  • U.S. Small Business Administration
  • Chase
  • Wells Fargo
  • Bank of Hawaii
  • Nationwide Insurance
  • Bank of America
  • IRS
  • Hawaii Courts

Credentialed Appraisers Serving Hawaii

Between them, AppraiseItNow's machinery and equipment appraisers hold CAGA designations. These are a few of them, and our reports are written to USPAP for the IRS, Hawaii courts, lenders, insurers, and more.

Joe Kattan

Joe Kattan

Owner & CEO

Joe joined AppraiseItNow as a co-owner in 2022 and acquired the company in November 2024 to make a certified, USPAP-compliant appraisal as simple to order as anything else online. A former Bain & Company strategy consultant, Joe leads the entire team and specializes in strategy, growth, and the firm's tech capabilities.

Jason Dolph

Jason Dolph

Machinery & Equipment Appraiser

Third-generation auctioneer and CAGA Certified Appraiser with more than 20 years valuing machinery, equipment, vehicles, business assets, and estates for banks, attorneys, and trustees across the Carolinas.

Marnie Erkelens

Marnie Erkelens

Vehicle Appraiser

CAGA Certified Appraiser since 2014, covering vehicles, boats, equipment, fine art, and collectibles. A classic-car restoration background informs her vehicle work, with reports prepared for insurance, divorce, and charitable contributions.

Aron Blue

Aron Blue

Client Success Manager

Manages each engagement from the first enquiry to the delivered report, and keeps you posted at every step along the way.

  • USPAPWritten to the Uniform Standards of Professional Appraisal Practice
  • Certified Appraisers Guild of AmericaCertified Appraiser
  • The Appraisal FoundationAuthorized by Congress as the source of appraisal standards
What we value
Machines and whole facilitiesSingle units, production lines and complete shop or kitchen inventories, from excavators and standby generators to chillers, imaging systems and point of sale fleets.
Premises we report
Four, named explicitlyFair market value in continued use, orderly liquidation value, forced liquidation value and replacement value, picked for the use the report is written for and stated on its face.
Where evidence comes from
Sales and cost bothRecorded auction and dealer results for comparable units, and current replacement cost less depreciation where island sales are too thin to carry a conclusion alone.
How it is delivered
Online, or on site at scaleEquipment here is usually valued from asset lists, photographs and service records, with an appraiser on the ground for a large or multi island project.

Waipahu Fabricators and Pearl City Contractors Hand Our Hawaii Appraisers Machines to Value

AppraiseItNow appraises construction and agricultural machinery, commercial kitchen and hotel equipment, medical and imaging systems, generators and shop tooling in Hawaii for lending, charitable gifts, estate administration, insurance and financial reporting.

Construction and energy

Excavators, cranes, and standby generators

Heavy equipment here changes hands among a short list of operators, and an excavator that would move in a week elsewhere can sit through a season. We price hours, powertrain condition and the attachments separately, and we say which recorded sales we were able to find.

Hospitality and food service

Kitchens, chillers, and laundry plants

Hotel and restaurant equipment is usually installed, ducted and tied into building services, and none of that appears in a listing price. Each report states whether installation sits inside the figure, because under a liquidation premise it generally does not.

How Long a Hawaii Owner Would Have to Find a Buyer Changes the Number in Kona or Hilo

Two choices settled before any analysis decide the answer: the date the value speaks to, and how long the owner is assumed to have to find a buyer. Neither one is a property of the machine, and the report names both.

Lending

Collateral valued on what a workout would bring

A lender wants to know what the equipment realizes if it has to go quickly, so the report fixes an exposure period and holds its comparables to sales that closed inside one. Where that period is short, the figure is a forced sale figure and is labelled as one.

Estates and donations

Equipment inside a Hawaii estate or a gift

An executor needs the figure the equipment carried on the day the owner died; a donor needs the figure it carried when the gift took effect. Both are fair market value questions, and for a large plant we value by category instead of unit by unit, with the basis for each category stated.

Insurance

Schedules written on replacement cost

An insurance schedule asks what putting the same capability back would cost today, landed and installed here, which is not the same question as what the machine would sell for. Carriers receive the cost evidence standing behind the figure. Where a model has been discontinued, we name the closest current equivalent and say why it stands in.

Hawaii Pays a Credit on What a Machine Cost and Takes Part of It Back if the Machine Leaves

The rules that reach a machine in Hawaii sit in the income tax, and they are keyed to what it cost and to how long it stays in service.

What qualifies

Section 38 property

The federal definition Hawaii borrows for the credit

The Hawaii Capital Goods Credit Runs on Cost, and Only Where the Excise Tax Was Paid

The credit under HRS § 235-110.7 is four percent of the qualifying cost of eligible depreciable tangible personal property placed in service in Hawaii during the taxable year, and the Department of Taxation defines that property as section 38 property with a depreciable life under the federal code. The purchase or importation must have borne general excise or use tax at four percent, and the half of one percent county surcharges earn no credit at all. Cost means the lower of the invoice price and the basis depreciation is taken from, and credit allowed above the income tax owed is refunded.

Hawaii Form N-312 instructions, HRS § 235-110.7

Claim deadline

12 months

After the close of the year, amended claims included

The Hawaii Credit Closes Twelve Months After the Year Ends, With No Carryover

The instructions for Form N-312 set the deadline to claim this credit, including an amended claim, at twelve months after the close of the taxable year, and state that it cannot be claimed or amended after that. There is no carryback and no carryover of credit above the liability; the excess is refunded instead, though no refund is issued for less than a dollar. A taxpayer who claims it either treats the amount as a taxable income item for the year or reduces the depreciable basis of the property by it.

Hawaii Form N-312 instructions, HRS § 235-110.7

Recapture

Three years

From the month the machine went into service

Selling a Hawaii Machine Early, or Using It Less, Pulls Part of the Credit Back

The recapture period begins on the first day of the month the property is placed in service and extends a full three years. Disposing of the property inside that window, or simply reducing its business use, forces a recomputation of the credit already taken, multiplied by a recapture percentage that accounts for any earlier recapture on the same asset. The resulting increase counts as income tax for the recapture year even where the taxpayer has a loss or would otherwise file nothing, and it cannot exceed the credit claimed.

Hawaii Form N-312 instructions, HRS § 235-110.7

What Hawaii clients say we are known for

Hawaii Appraisal Reviews: “Very impressive and incredibly helpful” and “I highly recommend the AppraiseItNow team”

  1. Being the appraiser they come back to“I would definitely use them again” Richard A.Mentioned in 12 reviews
  2. Answering fast, and staying reachable while the work runs“They were responsive and timely from start to finish” Julia P.Mentioned in 6 reviews
  3. Showing the research and the comparables behind the number“They diligently researched both equipment items and provided well-documented reports” Bob H.Mentioned in 5 reviews
  4. Delivering the finished report ahead of the deadlineMentioned in 4 reviews
  5. Taking on items other appraisers had already turned downMentioned in 4 reviews

Across 18 published Hawaii appraisal reviews, every one from a client who paid AppraiseItNow for an appraisal, the three things they raise most often are that they would hire us again, how quickly we answer, and how much research is visible in the report.

  • I needed a rapid turnaround appraisal on a charitable donation. The team here was able to review and complete my appraisal in under 24 hours, the same day that I sent the request in. Very impressive and incredibly helpful!
    Phil R. ·

    Machinery & Equipment Appraisal for Charitable Donation

  • I highly recommend the AppraiseItNow team. They were responsive and timely from start to finish, and the whole process was seamless. The final report was super detailed and gave me all the information I needed. I am so glad I hired them and would recommend them to anyone needing an appraisal!
    Julia P. ·

    Technology Equipment Appraisal for Divorce

  • I recommend AppraiseItNow Inc. highly. I needed an appraisal of fair market value for geologic laboratory equipment for charitable donations to three universities. The unique items and limited secondary market complicated the valuation. They provided a sound, verifiable estimate and the 8283 forms that I was able to use in my tax filings. I would use them again.
    Alan B. ·

    Lab Equipment Appraisal for Charitable Donation

  • I needed an IRS-qualified appraisal for an unusual and costly piece of medical equipment. AppraiseItNow was able to provide me exactly what I needed on a timely basis. The personnel at the company are very friendly and helpful. I would definitely use them again.
    Richard A. ·

    Medical Equipment Appraisal for Charitable Donation

  • AppraiseItNow did an outstanding job appraising my 1998 Bobcat Skid Steer and circa 2010 Yuchai Crawler Dozer. We could not locate a serial number on the dozer, and there were no online sales available, but they were still able to develop an accurate appraisal using known specifications for my dozer compared to other comparable make and model dozers. They diligently researched both equipment items and provided well-documented reports.
    Bob H. ·

    Machinery & Equipment Appraisal

  • Affordable and reliable, with fast service and always responsive to my messages and questions. They delivered my appraisal on time without a glitch. 100% Recommended! I wouldn’t use anyone else for my business. Thank you, Joe — you’re great!
    Ana R. ·

    Machinery & Equipment Appraisal for Bankruptcy Filing

We produce written equipment appraisal reports for lending, insurance, charitable donations, and litigation

Given the USPAP-compliant nature of AppraiseItNow’s appraisal reports, we prepare our deliverables for major legal, tax, and financial reporting purposes for individual and commercial clients.

Popular uses of our appraisal reports include:‍

Tax, Estate & Financial Planning

Transactions, Lending & Investment

Insurance & Risk Management

Life Events & Special Circumstances

  • Divorce
  • Social Security reporting or Medicaid Application Filings
  • E-2 visa applications

Frequently Asked Questions on Hawaii Equipment Appraisers

What is the difference between fair market value and liquidation value for equipment in Hawaii?

Fair market value assumes a willing buyer and seller with reasonable exposure time, while orderly and forced liquidation values assume shortened marketing periods and can run dramatically lower for the same machinery. Lenders financing Hawaii equipment often ask for liquidation premises, so we state the premise explicitly in every report to avoid mismatched numbers.

Which records speed up a machinery appraisal at a Hawaii facility?

Make, model, serial number, year, capacity, configuration, purchase date and cost, condition notes, and maintenance history are the core inputs. Detailed asset-level documentation lets our appraisers match each unit to comparable sales and cost data accurately instead of relying on broad assumptions.

Is book value a reliable stand-in for what Hawaii equipment is worth?

No. Book value reflects accounting depreciation schedules, while appraised value reflects actual market conditions, physical wear, and obsolescence, and the two routinely diverge. We work from cost and market evidence, separating physical deterioration from functional and economic obsolescence, rather than accepting the balance sheet figure.

Is machinery in Hawaii assessed for annual property tax?

No. Hawaii's property tax system is county-based and aimed at real property, and there is no statewide machinery or business personal property tax like those in Texas or Colorado. Equipment valuations in Hawaii are instead driven by probate inventories, lending and liquidation decisions, insurance, and litigation, so the appraisal premise follows the transaction rather than an assessment calendar.

How does Hawaii's isolation change equipment values?

It cuts both ways. Freight, inter-island transport, and long lead times shrink the pool of local buyers for used machinery, which can push local bids below mainland levels, while the same logistics raise the effective cost of bringing replacement equipment in. Our appraisers state which market the value reflects, because a Honolulu liquidation and a mainland replacement scenario produce very different defensible numbers.