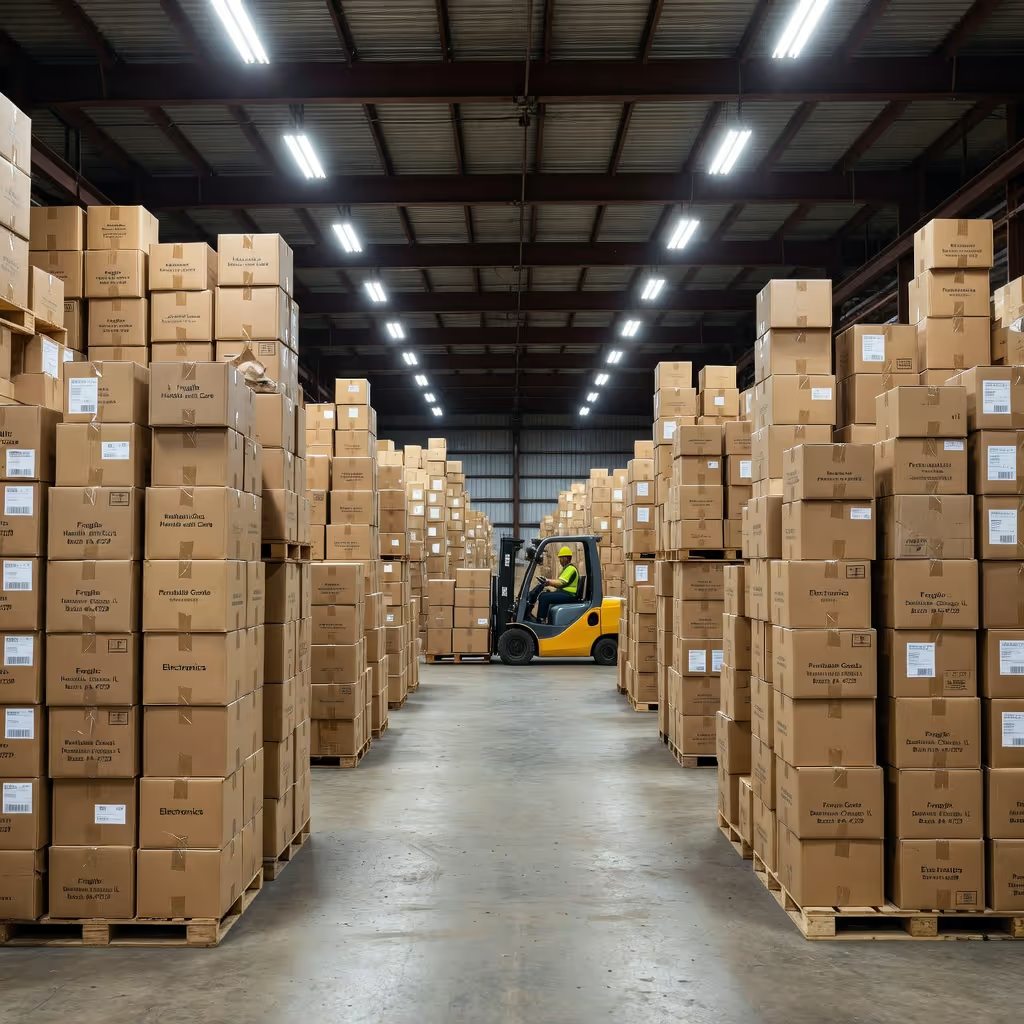
What standard of value applies to damaged business inventory?
Whatever the policy specifies: replacement cost or actual cash value, with ACV commonly meaning replacement cost minus fair depreciation, a formula California codifies in Insurance Code 2051(b). For commercial stock, endorsements like CP 99 30 (Value of Stock) or CP 99 20 (Manufacturer's Selling Price) can override the default ACV rule, so the declarations page controls before any appraisal begins.
What does an adjuster expect for each damaged line item?
Item-level detail: identity, quantity, condition, age, and value for every entry, supported by purchase invoices, photos, serial or model numbers, and a contemporaneous inventory list. Lump-sum estimates slow settlement and get reduced; a damaged-stock appraisal that matches the policy's value standard prevents the most common delays.
How is repairable inventory handled differently from destroyed stock?
Repairable goods are measured by the net cost of repairs, capped at the difference between pre-loss and post-loss value, with salvage value deducted. Destroyed stock is measured by pre-loss value minus any residual. Claims therefore need repair bids, salvage disposition records, and before-and-after condition evidence, not just an original cost figure.
Can the claim be based on lost retail selling price?
Sometimes, but not automatically. Courts require competent proof of lost value, and while property held for sale may be measured by diminution in retail market value in some jurisdictions, others limit recovery to replacement cost. The valuation standard itself is usually the first fight, which is why we anchor inventory damage reports to the specific policy and jurisdiction.