Inventory Appraisal for Loan Collateral

5.0from 80+ client reviews

Inventory appraisals for loan collateral, prepared in accordance with USPAP. AppraiseItNow delivers defensible borrowing base valuations across finished goods, raw materials, and work-in-process to support secured lending decisions.

Get an instant response

DEFENSIBLE, USPAP-COMPLIANT INVENTORY APPRAISAL REPORTS — QUALIFIED FOR LENDERS, BANKS, AND SURETY COMPANIES.

  • U.S. Small Business Administration
  • Chase
  • Bank of America
  • Wells Fargo
  • U.S. Bancorp
  • IRS

The inventory team behind your collateral appraisal

Between them, our inventory appraisers hold ISA and CAGA designations, and every report is written to USPAP for lenders, banks, and surety companies.

Joe Kattan

Joe Kattan

Owner & CEO

Joe founded AppraiseItNow to make a certified, USPAP-compliant appraisal as simple to order as anything else online. A former Bain & Company strategy consultant, Joe leads the entire team and specializes in strategy, growth, and the firm's tech capabilities.

Anne Hay

Anne Hay

Personal Property Appraiser

ISA Accredited Member with 30 years in the trade, from running estate sales and an auction gallery to appraising luxury apparel, furniture, artwork, antiques, and business assets, primarily for IRS tax filings.

Jason Dolph

Jason Dolph

Machinery & Equipment Appraiser

Third-generation auctioneer and CAGA Certified Appraiser with more than 20 years valuing machinery, equipment, vehicles, business assets, and estates for banks, attorneys, and trustees across the Carolinas.

Ashley Innes

Ashley Innes

Personal Property Appraiser

ISA Accredited Member specializing in Asian art, with a Master's from SOAS and a Postgraduate Diploma in Asian Art. Ashley chairs the ISA's Antiques, Furnishings, and Decorative Arts committee and appraises for charitable donation, insurance, and equitable distribution.

Aron Blue

Aron Blue

Client Success Manager

Manages each engagement from the first enquiry to the delivered report, and keeps you posted at every step along the way.

  • USPAPWritten to the Uniform Standards of Professional Appraisal Practice
  • Fair market and liquidation valueThe collateral values lenders and surety companies underwrite against
  • International Society of AppraisersAccredited Member
  • Certified Appraisers Guild of AmericaCertified Appraiser
  • The Appraisal FoundationAuthorized by Congress as the source of appraisal standards

Appraising Corporate Inventory for Loan Collateral

Corporate inventory is one of the most commonly pledged assets in asset-based lending, yet it requires careful, methodology-driven valuation to be useful to lenders. The standard measure lenders rely on is net orderly liquidation value, which reflects what inventory would realistically yield if sold in an organized liquidation rather than at distressed auction prices. For SBA 7(a) loans, an independent appraisal is required when the financed amount exceeds $250,000, and many conventional lenders impose similar thresholds. Our inventory appraisal practice covers finished goods, raw materials, and work-in-process across a wide range of industries, producing the documented advance-rate support that lenders need to structure a borrowing base.

We deliver these appraisals both onsite and through our online platform, depending on the nature and location of the inventory. Our appraisers are credentialed through ISA, ASA, AAA, CAGA, AMEA, and NEBB, and carry no financial interest in any transaction they evaluate. Whether you are securing a revolving credit facility or a term loan, our collateral lending appraisal services provide the independent, lender-ready documentation your deal requires.

Types of Corporate Inventory We Appraise for Loan Collateral

AppraiseItNow covers the full range of inventory categories that lenders commonly accept as collateral, including:

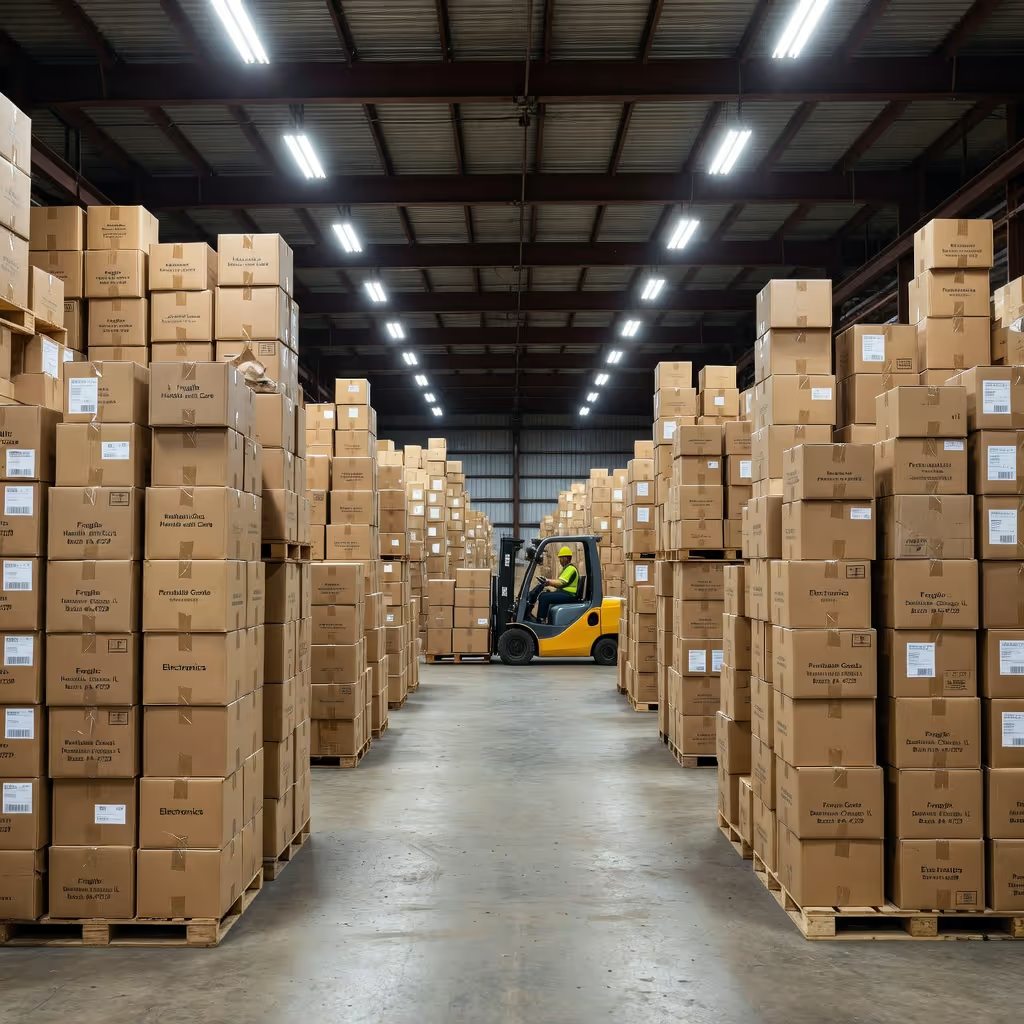
  • Finished goods held in a company's own warehouse or distribution center
  • Raw materials including metals, chemicals, textiles, lumber, and agricultural commodities
  • Work-in-process inventory at various stages of manufacturing completion
  • Retail merchandise including apparel, consumer electronics, and hard goods
  • Wholesale and distributor stock across industrial, medical, and commercial supply chains
  • Perishable and time-sensitive inventory where shelf life directly affects collateral value
  • Specialty or proprietary inventory with limited secondary market demand
  • Imported goods in transit or held in bonded warehouses
  • Seasonal inventory with cyclical demand patterns that affect liquidation timing
  • Consigned inventory analysis to identify and exclude non-owned stock from eligible collateral

How AppraiseItNow Conducts Inventory Appraisals for Lenders

Our process is structured to produce reports that meet lender, regulatory, and USPAP standards from start to finish.

  • Appraisers conduct a thorough review of perpetual inventory records, SKU-level data, cost reports, and any existing field audit findings to establish a baseline before any onsite visit or remote analysis begins.
  • The valuation methodology focuses on net orderly liquidation value, with analysis of eligible versus ineligible inventory categories, including obsolete stock, consigned goods, and off-site inventory lacking landlord waivers, so lenders receive a clear picture of what is actually lendable.
  • Delivered reports include a narrative description of the inventory, the valuation methodology applied, supporting market data, and a final value conclusion that lenders can use directly to set advance rates and borrowing base calculations.
  • All appraisers are credentialed through recognized professional organizations and operate independently of the borrower, lender, and any other party to the transaction, satisfying the independence requirements that banking regulators and SBA guidelines impose.

What clients say we are known for

AppraiseItNow Reviews: What Clients Say About AppraiseItNow

  1. Answering fast, and staying reachable while the work runs“From the start they were very responsive, price competitive” Chris S.Mentioned in 34 reviews
  2. Showing the research and the comparables behind the number“Very thorough and professional — great communication and outstanding service” Curt B.Mentioned in 29 reviews
  3. Delivering the finished report ahead of the deadlineMentioned in 21 reviews
  4. Being the appraiser they come back toMentioned in 44 reviews
  5. Taking on items other appraisers had already turned downMentioned in 14 reviews

Across 80+ published AppraiseItNow reviews the picture is consistent: every one is from a client who paid us for an appraisal, and the three things they raise most often are that they would hire us again, how quickly we answer, and how much research is visible in the report.

  • Had a great experience working with AppraiseItNow for a potential loan our company was working on. I was very appreciative of the time they took to prepare the appraisal, plus the extra effort to advise us and explain the appraisal findings.
    David O., New York, NY ·

    Inventory Appraisal for Loan Collateral

  • From the start they were very responsive, price competitive, and had a quick turn around time. Thank you so much to Joe who was very sweet in responding to my emails; I am looking forward to utilizing AppraiseItNow for many years to come.
    Chris S., San Clemente, CA ·
  • Very thorough and professional — great communication and outstanding service. Highly impressed with their work!
    Curt B. , Washington, UT ·

Frequently Asked Questions on Inventory Appraisals for Loan Collateral

What value do lenders put on inventory pledged as collateral?

Net orderly liquidation value: the gross recovery from an orderly sale minus auction fees, legal costs, storage, and transport, not fair market or book value. Regulators reinforce this, directing that inventory collateral be based on the lesser of cost or liquidation value with soft costs excluded, because the lender's question is what the stock brings after a default.

What portion of the inventory's value can be borrowed against?

Typically around half, with asset-based lenders commonly advancing 50 to 65 percent of net orderly liquidation value on eligible inventory. Inventory is treated as one of the weakest collateral classes because liquidating it quickly at full value is hard, so borrowers expecting book-value credit are routinely surprised by the haircut.

Which inventory gets excluded from the borrowing base?

Obsolete stock, consigned goods the borrower does not own, and off-site inventory without landlord waivers are standard ineligibles, and raw materials or work-in-process may be credited at as little as 0 to 10 percent of value versus 50 to 60 percent for finished goods. Our reports classify eligible versus ineligible categories so the lender sees exactly what is lendable.

Why do costing methods matter in a collateral appraisal?

Because the borrowing base starts from book inventory and lenders must trust the costing behind it: FIFO, LIFO, or standard cost each embed different assumptions, and regulators expect soft costs like overhead and freight stripped out. Field exams test these inputs, and disagreements over costing and eligibility are the most common source of collateral value disputes.