Inventory Appraisal for Mergers & Acquisitions

5.0from 80+ client reviews

Inventory appraisals for mergers & acquisitions, prepared in accordance with USPAP. AppraiseItNow delivers accurate fair market value assessments of stock, raw materials, and finished goods to keep deals on track.

Get an instant response

DEFENSIBLE, USPAP-COMPLIANT INVENTORY APPRAISAL REPORTS — QUALIFIED FOR THE IRS, AUDITORS, AND THE COURTS.

  • IRS
  • GASB
  • United States Courts
  • U.S. Small Business Administration
  • Chase
  • Bank of America
  • Wells Fargo

The inventory team behind your valuation report

Between them, our inventory appraisers hold ISA and CAGA designations, and every report is written to USPAP for the IRS, auditors, and the courts.

Joe Kattan

Joe Kattan

Owner & CEO

Joe founded AppraiseItNow to make a certified, USPAP-compliant appraisal as simple to order as anything else online. A former Bain & Company strategy consultant, Joe leads the entire team and specializes in strategy, growth, and the firm's tech capabilities.

Anne Hay

Anne Hay

Personal Property Appraiser

ISA Accredited Member with 30 years in the trade, from running estate sales and an auction gallery to appraising luxury apparel, furniture, artwork, antiques, and business assets, primarily for IRS tax filings.

Jason Dolph

Jason Dolph

Machinery & Equipment Appraiser

Third-generation auctioneer and CAGA Certified Appraiser with more than 20 years valuing machinery, equipment, vehicles, business assets, and estates for banks, attorneys, and trustees across the Carolinas.

Ashley Innes

Ashley Innes

Personal Property Appraiser

ISA Accredited Member specializing in Asian art, with a Master's from SOAS and a Postgraduate Diploma in Asian Art. Ashley chairs the ISA's Antiques, Furnishings, and Decorative Arts committee and appraises for charitable donation, insurance, and equitable distribution.

Aron Blue

Aron Blue

Client Success Manager

Manages each engagement from the first enquiry to the delivered report, and keeps you posted at every step along the way.

  • USPAPWritten to the Uniform Standards of Professional Appraisal Practice
  • Rev. Rul. 59-60 and ASC 820The valuation framework the IRS, auditors, and courts test a business value against
  • International Society of AppraisersAccredited Member
  • Certified Appraisers Guild of AmericaCertified Appraiser
  • The Appraisal FoundationAuthorized by Congress as the source of appraisal standards

Inventory Appraisals for Mergers and Acquisitions

Accurate inventory valuation is one of the most consequential and frequently contested elements of any M&A transaction. Under ASC 805, business combinations require fair value measurement of all acquired assets, including inventory, as of the acquisition date. For tax purposes, purchase price allocations under IRC Section 1060 must reflect fair market value across asset classes, with both buyer and seller filing IRS Form 8594 using identical figures. Our inventory appraisal services address the full scope of these requirements, from raw materials and work-in-process to finished goods, applying GAAP-consistent methodology that holds up to auditor and IRS scrutiny.

AppraiseItNow delivers inventory appraisals online and onsite throughout the United States, supporting deal teams, CFOs, and transaction counsel at every stage of the process. Whether you need a pre-close valuation to anchor working capital negotiations or a post-close opening balance sheet figure, our M&A appraisal services are structured to meet deal timelines without sacrificing rigor.

Inventory Types We Appraise in M&A Transactions

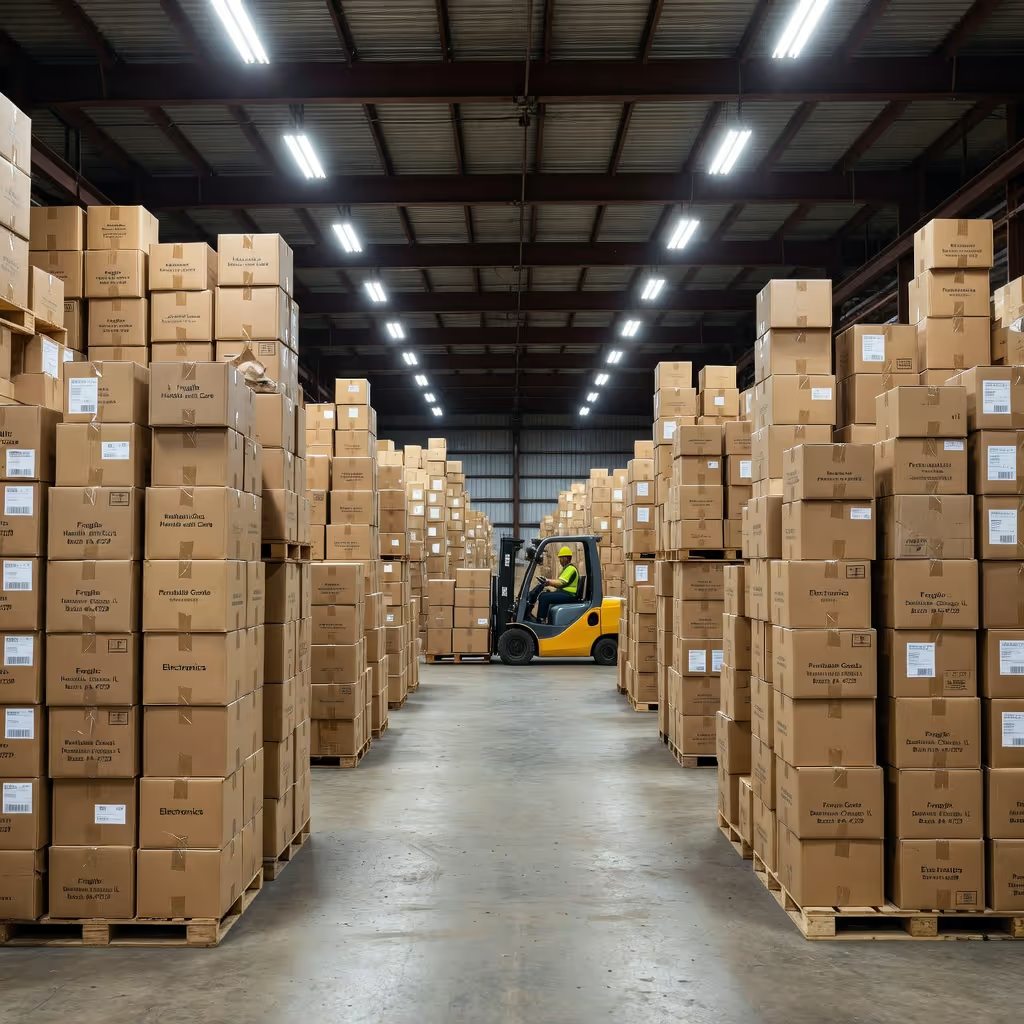
AppraiseItNow appraises a wide range of inventory categories that commonly appear in acquisition due diligence and purchase price allocation work.

  • Raw materials, including bulk commodities, components, and unprocessed inputs held at manufacturing or distribution facilities
  • Work-in-process inventory at various stages of completion, requiring cost-layer analysis from receipt through production
  • Finished goods ready for sale, valued against current market pricing and net realizable value
  • Slow-moving, excess, and obsolete stock requiring reserve analysis and SKU-level aging review
  • Consigned inventory, whether held by the seller on behalf of others or held by third parties on behalf of the seller
  • Spare parts and maintenance, repair, and operations (MRO) inventory tied to production equipment
  • Retail merchandise inventory across single or multi-location businesses, including seasonal and clearance stock
  • Wholesale and distributor inventory with layered cost structures and varying turnover rates
  • Perishable or shelf-life-limited inventory requiring condition assessment and remaining usability analysis
  • Industry-specific inventory such as pharmaceutical stock, food and beverage products, or specialty chemicals with regulatory considerations

How AppraiseItNow Approaches M&A Inventory Appraisals

Our appraisers review inventory listings by location, including item descriptions, SKU numbers, acquisition dates, unit counts, and recorded costs, and reconcile these against physical count observations and usage reports.

  • Valuation methodology follows ASC 330 and ASC 805 requirements, with analysis of cost basis from receipt to current condition, turnover rates, and reserve adequacy for slow-moving or obsolete items. Where pre-M&A accounting practices deviate from GAAP, such as expensed inbound freight or inconsistent overhead capitalization, our appraisers document the adjustments required to arrive at a compliant fair value conclusion.
  • Reports are structured to support both financial reporting and tax allocation purposes, with reconciliation between fair value under ASC 805 and fair market value for IRS Form 8594 filings. This dual-purpose documentation reduces the risk of discrepancies between buyer and seller filings, which are a known audit trigger.
  • AppraiseItNow appraisers hold credentials through recognized professional organizations including ASA, ISA, AAA, and others, and are experienced working alongside quality of earnings analysts, transaction attorneys, and Big Four audit teams on time-sensitive deal schedules.
  • Appraisals are available both onsite, with physical count observation and facility walkthroughs, and remotely using digital inventory records, photographs, and management interviews, depending on deal structure and timeline requirements.

What clients say we are known for

AppraiseItNow Reviews: What Clients Say About AppraiseItNow

  1. Answering fast, and staying reachable while the work runs“From the start they were very responsive, price competitive” Chris S.Mentioned in 34 reviews
  2. Showing the research and the comparables behind the number“Very thorough and professional — great communication and outstanding service” Curt B.Mentioned in 29 reviews
  3. Delivering the finished report ahead of the deadlineMentioned in 21 reviews
  4. Being the appraiser they come back toMentioned in 44 reviews
  5. Taking on items other appraisers had already turned downMentioned in 14 reviews

Across 80+ published AppraiseItNow reviews the picture is consistent: every one is from a client who paid us for an appraisal, and the three things they raise most often are that they would hire us again, how quickly we answer, and how much research is visible in the report.

  • From the start they were very responsive, price competitive, and had a quick turn around time. Thank you so much to Joe who was very sweet in responding to my emails; I am looking forward to utilizing AppraiseItNow for many years to come.
    Chris S., San Clemente, CA ·
  • Very thorough and professional — great communication and outstanding service. Highly impressed with their work!
    Curt B. , Washington, UT ·

Frequently Asked Questions on Inventory Appraisals for Mergers & Acquisitions

How is inventory valued when a company changes hands?

Under different standards for different purposes: buyers price inventory at its investment value to their own operations, tax purchase price allocations require fair market value, and post-closing financial statements measure it at ASC 820 fair value from a market-participant perspective. Using the wrong standard for the context is the core technical error in M&A inventory work.

What inventory records do buyers scrutinize in diligence?

SKU-level stock listings, aging schedules, costing policies, and write-down history. Buyers and their lenders challenge valuations that ignore obsolescence or excess stock, because the asset approach restates book inventory to fair value and any padding flows straight into the price. Missing aging detail is treated as risk and priced accordingly.

How does inventory affect the purchase price beyond its own line?

Deal multiples on EBITDA or seller's discretionary earnings implicitly assume normalized working capital, including typical inventory levels. When inventory is unusually high, low, or partly obsolete, the parties adjust the working capital peg or the earnings base, so a disputed inventory number can move the price by more than the inventory itself.

Does the negotiated deal price establish fair value of the assets?

Not automatically. Delaware courts treat merger price as evidence of fair value, sometimes decisive evidence, but only when the sale process was sound, and statutory fair value excludes value created by the merger itself. The deal price is a data point for asset-level values, not a substitute for supported allocation work.