Iowa Equipment Appraisers

5.0from 80+ client reviews

Equipment appraisals in Iowa for donations, lending, M&A, and financial reporting, prepared in accordance with USPAP and IRS requirements. AppraiseItNow appraises agricultural equipment, manufacturing machinery, construction equipment, fleet vehicles, and industrial tools across Iowa, including Des Moines, Cedar Rapids, and Davenport.

Get an instant response

DEFENSIBLE, USPAP-COMPLIANT MACHINERY & EQUIPMENT APPRAISAL REPORTS — QUALIFIED FOR THE IRS, IOWA COURTS, LENDERS, INSURERS, AND MORE.

  • U.S. Small Business Administration
  • Chase
  • Wells Fargo
  • First National Bank of Omaha
  • Nationwide Insurance
  • Bank of America
  • IRS
  • Iowa Courts

Credentialed Appraisers Serving Iowa

Between them, our machinery and equipment appraisers hold CAGA designations, and every report is written to USPAP for the IRS, Iowa courts, lenders, insurers, and more.

Joe Kattan

Joe Kattan

Owner & CEO

Joe founded AppraiseItNow to make a certified, USPAP-compliant appraisal as simple to order as anything else online. A former Bain & Company strategy consultant, Joe leads the entire team and specializes in strategy, growth, and the firm's tech capabilities.

Jason Dolph

Jason Dolph

Machinery & Equipment Appraiser

Third-generation auctioneer and CAGA Certified Appraiser with more than 20 years valuing machinery, equipment, vehicles, business assets, and estates for banks, attorneys, and trustees across the Carolinas.

Marnie Erkelens

Marnie Erkelens

Vehicle Appraiser

CAGA Certified Appraiser since 2014, covering vehicles, boats, equipment, fine art, and collectibles. A classic-car restoration background informs her vehicle work, with reports prepared for insurance, divorce, and charitable contributions.

Aron Blue

Aron Blue

Client Success Manager

Manages each engagement from the first enquiry to the delivered report, and keeps you posted at every step along the way.

  • USPAPWritten to the Uniform Standards of Professional Appraisal Practice
  • Certified Appraisers Guild of AmericaCertified Appraiser
  • The Appraisal FoundationAuthorized by Congress as the source of appraisal standards
What we value in Iowa
Farm to factoryTractors, combines, mowers, and tillage tools on one side; CNC machines, processing lines, shop equipment, and fleet units on the other.
How the work is done
Online by defaultAsset lists, photographs, and purchase records carry most assignments. Our appraisers travel for a plant, a yard, or an inventory spread across several Iowa sites.
Why owners call us
Gifts, loans, estatesCharitable donations, collateral and SBA files, purchase price allocations, partner buyouts, and estate inventories.

Iowa Manufacturers in Cedar Rapids and Growers Near Davenport Send Us Equipment to Value

AppraiseItNow appraises farm machinery, processing and packaging lines, construction equipment, shop tools, and fleet units in Iowa for charitable donations, lending, estates, partner buyouts, and financial reporting.

Donations

Equipment given to a charity or a school

A donated machine is valued as it stands, from sales of the same model in the same condition, with the serial plate and the service history doing the work of proof. A charity cannot sign for a number it did not reach, so the report carries the comparables rather than a conclusion.

Lending

Collateral for an Iowa lender or an SBA file

A loan file needs a figure tied to a stated premise and a stated date, supported by auction results and dealer offerings for the same make and model rather than a schedule depreciated on a single curve. Where a lender wants a liquidation premise as well, both figures sit in one report with the exposure period each assumes written out.

Estates and buyouts

Machines inside an estate or a partner buyout

When a farm or a shop passes to heirs, or one owner buys the other out, the machines that carry the money are valued one at a time and the small tools by category, at a depth agreed before we start. That keeps the cost proportionate to what is actually in dispute.

Financial reporting

A purchase price allocation after an acquisition

After an acquisition, the equipment on the schedule has to be restated at value rather than carried at book, machine by machine. We work from the fixed asset register, the plant layout, and what the same lines are selling for used.

Donated Farm and Medical Equipment in Davenport and Mason City Are Iowa Files We Have Valued

Two recent Iowa equipment assignments, cut down to what the work was. The donors, the figures, and the serial data stay in the report, and the photographs here are illustrations rather than the items themselves.

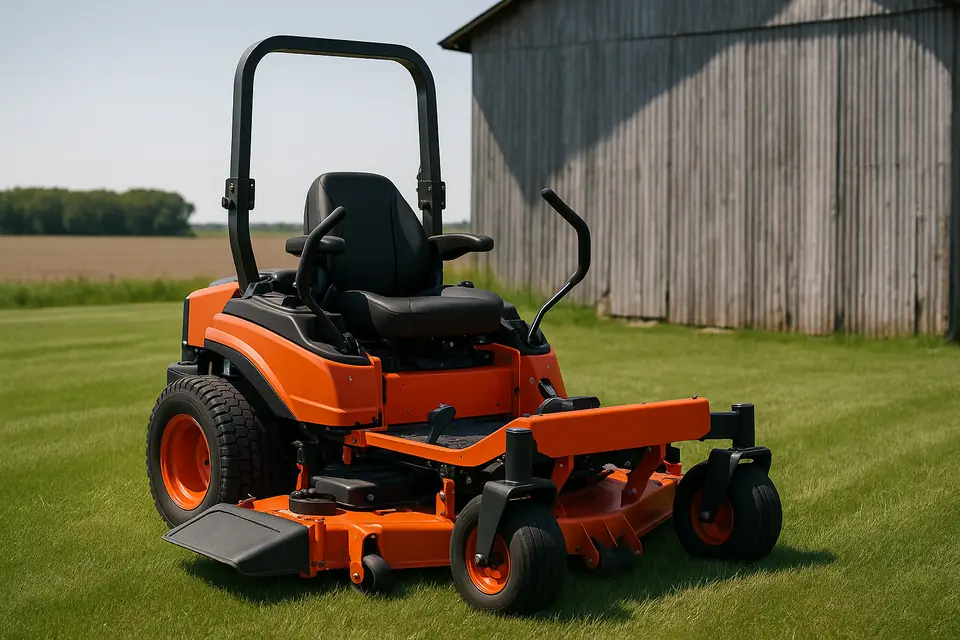
Orange and black zero turn riding mower parked on mown grass beside a farm shed

Farm equipment donation

A Davenport farm donation of Kubota mowing equipment

Valued from the serial plates and model codes the donor supplied, at what the same machines bring on the used market.

  • Fair market value
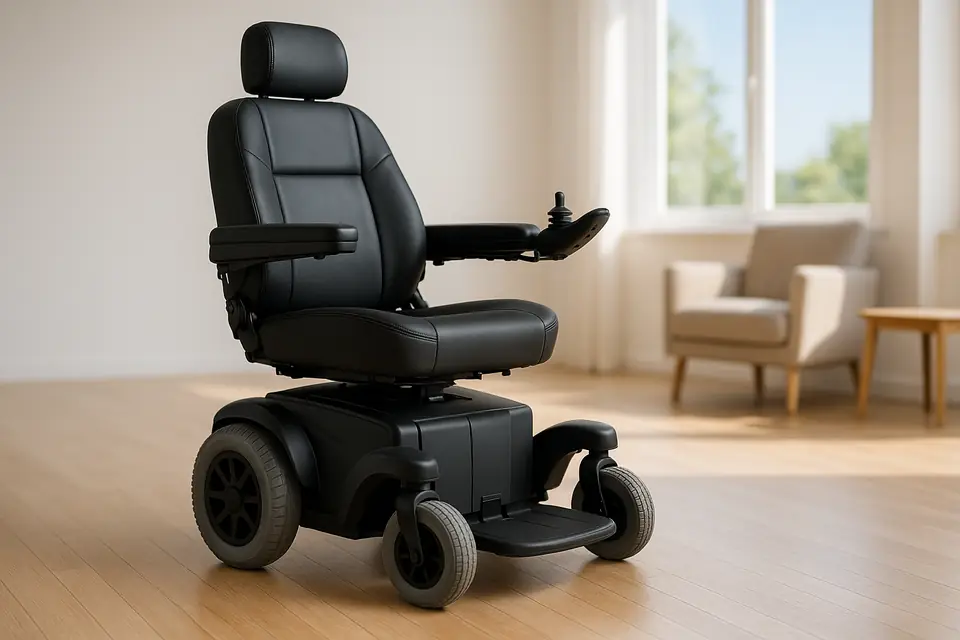
Power wheelchair with a padded seat and joystick control in a bright empty living room

Medical equipment donation

Home medical and lift equipment donated in Mason City

A ceiling lift, a portable patient lift, and a power wheelchair, each valued against comparable used units rather than new list prices.

  • Fair market value

Iowa Law Reaches Equipment in a Collection Case, a Tax Invoice, and a Closing Dealership

Three Iowa rules decide how much equipment a debtor keeps, whether sales tax belongs inside a replacement cost figure, and what a supplier owes a dealership on its way out.

Collections

$10,000

of trade or farm equipment a debtor may hold exempt

Iowa Lets a Debtor Keep Ten Thousand Dollars of the Tools the Work Runs On

Iowa exempts the proper implements, professional books, and tools of a debtor’s trade up to ten thousand dollars in the aggregate. A debtor engaged in farming may instead select implements and equipment reasonably related to a normal farming operation, together with livestock and feed, up to the same aggregate figure, and that is on top of an exempt motor vehicle. Because the line is an aggregate value rather than a list of machines, which implements stay depends on what each one is worth.

Iowa Code § 627.6(11), (12)

Cost approach

Exempt

Iowa sales tax on qualifying farm and factory machinery

Qualifying Iowa Farm and Factory Machinery Is Bought Without Sales Tax

Iowa exempts from sales tax farm machinery and equipment, with the auxiliary attachments and replacement parts that serve it, when it is directly and primarily used in the production of agricultural products and is self propelled or customarily drawn by a self propelled implement. A separate exemption covers computers, machinery, equipment, and replacement parts directly and primarily used in processing by a manufacturer. Vehicles subject to registration fall outside the farm exemption. A replacement cost figure built from invoices therefore carries Iowa tax on some assets in a schedule and none on others.

Iowa Code § 423.3(8), (47)

Dealerships

100%

of net cost, the buyback price of unused equipment

An Iowa Supplier Buys a Closing Dealership Out at Percentages Set by Statute

When an Iowa equipment dealership agreement is cancelled or not renewed by either side, the supplier must repurchase the dealer’s stock: the full net cost of unused complete equipment, including attachments, bought from the supplier in the twenty four months before notice and still in new condition; ninety percent of net price on repair parts; and seventy five or fifty percent of net cost on special repair tools, by how long ago they were bought. Demonstration units are repurchased at an agreed depreciated value, the one figure in that list a price sheet cannot settle.

Iowa Code § 322F.3

What Iowa clients say we are known for

Iowa Appraisal Reviews: “I highly recommend the AppraiseItNow team” and “I would definitely use them again”

  1. Being the appraiser they come back to“I would definitely use them again” Richard A.Mentioned in 11 reviews
  2. Answering fast, and staying reachable while the work runs“They were responsive and timely from start to finish” Julia P.Mentioned in 6 reviews
  3. Showing the research and the comparables behind the number“They diligently researched both equipment items and provided well-documented reports” Bob H.Mentioned in 5 reviews
  4. Taking on items other appraisers had already turned downMentioned in 4 reviews
  5. Delivering the finished report ahead of the deadline“They did it quickly” Phil L.Mentioned in 3 reviews

Across 16 published Iowa appraisal reviews, every one from a client who paid AppraiseItNow for an appraisal, the three things they raise most often are that they would hire us again, how quickly we answer, and how much research is visible in the report.

  • I recommend AppraiseItNow Inc. highly. I needed an appraisal of fair market value for geologic laboratory equipment for charitable donations to three universities. The unique items and limited secondary market complicated the valuation. They provided a sound, verifiable estimate and the 8283 forms that I was able to use in my tax filings. I would use them again.
    Alan B. ·

    Lab Equipment Appraisal for Charitable Donation

  • AppraiseItNow did an outstanding job appraising my 1998 Bobcat Skid Steer and circa 2010 Yuchai Crawler Dozer. We could not locate a serial number on the dozer, and there were no online sales available, but they were still able to develop an accurate appraisal using known specifications for my dozer compared to other comparable make and model dozers. They diligently researched both equipment items and provided well-documented reports.
    Bob H. ·

    Machinery & Equipment Appraisal

  • I highly recommend the AppraiseItNow team. They were responsive and timely from start to finish, and the whole process was seamless. The final report was super detailed and gave me all the information I needed. I am so glad I hired them and would recommend them to anyone needing an appraisal!
    Julia P. ·

    Technology Equipment Appraisal for Divorce

  • I needed an IRS-qualified appraisal for an unusual and costly piece of medical equipment. AppraiseItNow was able to provide me exactly what I needed on a timely basis. The personnel at the company are very friendly and helpful. I would definitely use them again.
    Richard A. ·

    Medical Equipment Appraisal for Charitable Donation

  • Affordable and reliable, with fast service and always responsive to my messages and questions. They delivered my appraisal on time without a glitch. 100% Recommended! I wouldn’t use anyone else for my business. Thank you, Joe — you’re great!
    Ana R. ·

    Machinery & Equipment Appraisal for Bankruptcy Filing

  • They did an appraisal of medical equipment for donation. They did it quickly, and I received a blank form 8283 signed by the appraiser. It was what I needed. The price was higher than I wanted to spend on an appraisal, but a lot lower than other appraisers. AppraiseItNow was very responsive and communicative, and the other appraisers were not. I would use them again.
    Phil L. ·

    Medical Equipment Appraisal for Charitable Donation

We produce written equipment appraisal reports for lending, insurance, charitable donations, and litigation

Given the USPAP-compliant nature of AppraiseItNow’s appraisal reports, we prepare our deliverables for major legal, tax, and financial reporting purposes for individual and commercial clients.

Popular uses of our appraisal reports include:‍

Tax, Estate & Financial Planning

Transactions, Lending & Investment

Life Events & Special Circumstances

  • Divorce
  • Social Security reporting or Medicaid Application Filings
  • E-2 visa applications

Frequently Asked Questions on Iowa Equipment Appraisers

What information should an Iowa business gather before an equipment appraisal?

An asset list with make, model, serial numbers, year, capacity, configuration, purchase dates and costs, condition, and maintenance history. Complete asset-level documentation is what allows accurate matching to market comparables and credible cost-approach calculations for each machine.

How does depreciation really work in machinery appraisals?

Appraisers deduct three distinct components from replacement cost new: physical wear, functional obsolescence from technology or capacity mismatches, and economic obsolescence from external market changes. A simple age-based schedule misses those distinctions, which is why appraised values often diverge from book figures for Iowa equipment.

Why would the same Iowa machine carry three different values?

Because fair market value, orderly liquidation value, and forced liquidation value are separate premises tied to different exposure times and sale conditions. Lenders and workout situations often call for the liquidation premises, and owners who request the wrong one end up with a number that does not fit the decision at hand.

Why is our Iowa machinery carried on the real property tax roll?

Because Iowa Code section 427A.1 treats machinery used in manufacturing establishments as real estate for purposes of taxation, a rule the Iowa Supreme Court applied in Maytag Co. v. Partridge. That classification is limited to assessment. The same machines remain personal property when they are sold, pledged, or transferred through an estate, so tax treatment does not control how we classify or value them.

Does Iowa still tax industrial machinery and computers?

Largely no. Industrial machinery, equipment, and computers acquired after 1981 were assessed at no more than 30 percent of net acquisition cost through the 1998 assessment year and at zero percent for assessment years after that, which removed most of these assets from the tax base. Owners who expect an assessor's value to exist for their equipment usually find that none does.