Maryland Business Valuation

5.0 on Google110+ 5-star reviews

Business valuations in Maryland for donations, M&A, gift tax, and IRA conversion, prepared in accordance with USPAP and IRS requirements. AppraiseItNow appraises small businesses, partnerships, corporations, professional practices, and franchises across Maryland, including Baltimore, Annapolis, and Rockville.

Get an instant response

DEFENSIBLE, USPAP-COMPLIANT BUSINESS APPRAISAL REPORTS — QUALIFIED FOR THE IRS, MARYLAND COURTS, LENDERS, INSURERS, AND MORE.

  • IRS
  • GASB
  • Maryland Courts
  • U.S. Small Business Administration
  • Chase
  • M&T Bank
  • Bank of America

Credentialed Appraisers Serving Maryland

Between them, AppraiseItNow's business valuation appraisers hold ASA, ABV, and CFA designations. These are a few of them, and our reports are written to USPAP for the IRS, Maryland courts, lenders, insurers, and more.

Joe Kattan

Joe Kattan

Owner & CEO

Joe joined AppraiseItNow as a co-owner in 2022 and acquired the company in November 2024 to make a certified, USPAP-compliant appraisal as simple to order as anything else online. A former Bain & Company strategy consultant, Joe leads the entire team and specializes in strategy, growth, and the firm's tech capabilities.

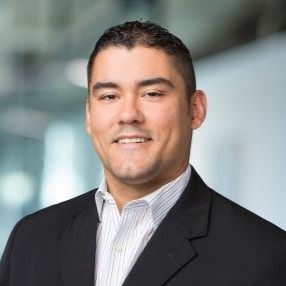
Justin Ramirez

Justin Ramirez

Business Valuation Expert & Appraiser

ASA, ABV, and CFA charterholder. Since 2016 Justin has valued businesses for estate and gift tax, purchase price allocations, fairness opinions, lending, and buy-sell agreements, across manufacturing, services, retail, and pre-revenue biotech.

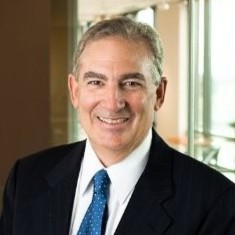
Raymond Ghelardi

Raymond Ghelardi

Business Valuation Expert & Appraiser

Accredited Senior Appraiser with the American Society of Appraisers. Raymond values capital stock, business enterprises, stock options, and intangible assets.

Aron Blue

Aron Blue

Client Success Manager

Manages each engagement from the first enquiry to the delivered report, and keeps you posted at every step along the way.

  • USPAPWritten to the Uniform Standards of Professional Appraisal Practice
  • American Society of AppraisersAccredited Senior Appraiser
  • AICPAAccredited in Business Valuation
  • CFA InstituteChartered Financial Analyst
  • The Appraisal FoundationAuthorized by Congress as the source of appraisal standards
What we value
Whole companies and minority stakesControlling interests, minority blocks, and single member LLCs.
Standard of value
Named in the reportFair market value and statutory fair value answer different questions, so the report says which one applies.
Engagement
RemoteRecords, management interviews, and a written conclusion, wherever the company sits.

The Maryland Companies We Value Are Family Corporations, Medical Practices, Contractors, and Single Owner LLCs in Gaithersburg and Bel Air

AppraiseItNow values Maryland corporations, partnerships, LLCs, and professional practices for gift and estate tax filings, buy and sell agreements, shareholder exits, and charitable gifts of closely held stock.

Operating companies

Contractors, Distributors, and Light Manufacturers

Along the Baltimore and Washington corridor these are often second generation companies where one or two owners still do the selling. Backlog, customer lists, and whether the work would follow an owner out the door all get tested before any multiple is applied.

Professional practices

Medical, Dental, and Accounting Firms

A practice is valued on what it earns after a market rate of pay for the people producing the revenue. Partner compensation, referral sources, and the terms of associate agreements shape that figure more than the headline collections do.

Holding entities

Real Estate and Investment LLCs

Where an entity holds assets rather than operations, the question moves to the interest itself: what a holder controls, what they can compel, and what the operating agreement permits. Underlying property values are an input to that, never the conclusion.

Franchised operations

Dealerships, Agencies, and Franchise Units

A franchise agreement decides who may buy an interest, on what timetable, and with whose consent, which narrows the market before anything financial is considered. We read the agreement and its transfer provisions beside the statements rather than after them.

What a Maryland Valuation Runs On Is the Returns, the Operating Agreement, and the Cap Table in Salisbury and Ellicott City

Most of a Maryland engagement is reading documents the owner already holds.

Financial record

Five Years of Returns and Statements

Tax returns, internal statements, and the reconciliation between them. Where the two disagree the reasons are usually ordinary, and we would far rather write them down ourselves than have a reviewer find them later.

Governing documents

The Operating Agreement and Any Buy Sell Terms

Transfer restrictions, mandatory purchase terms, and voting provisions bear directly on what an interest is worth to the person holding it. A formula in an old agreement gets read, and so does the question of whether anyone has ever followed it.

Ownership map

The Cap Table and Who Holds What

Who owns which class, in what proportion, and on what terms decides whether a block carries control, a swing vote, or neither. That map, rather than the size of the company, drives the adjustments at the end of the report.

Maryland Hands the Fair Value Question to Three Court Appointed Appraisers

Maryland does not leave a dissenting stockholder's number to the parties to settle between themselves.

Appraisal rights

The day of the vote

is the moment value is measured

Maryland Sets a Dissenting Stockholder's Value Date by the Calendar, Not by the Closing

Where a Maryland stockholder objects to a transaction and seeks fair value, the statute fixes the measuring moment: the close of business on the day the stockholders voted on the transaction objected to, or, for a merger under § 3-106 or § 3-106.1, the day notice is given or waived. Fair value may not include any appreciation or depreciation which directly or indirectly results from the transaction or from its proposal. A valuation written for this purpose therefore carries a precise effective date and a deliberate blindness to the deal itself.

Md. Code, Corps. & Ass'ns § 3-202

Court appraisal

Three appraisers

with sixty days to report

A Maryland Court Appoints Three Disinterested Appraisers and Gives Them Sixty Days

If the court finds the objecting stockholder entitled to an appraisal, it appoints three disinterested appraisers on terms it considers proper, and each takes an oath to perform the duties honestly and faithfully. Within sixty days of appointment, unless the court allows longer, they determine fair value as of the appropriate date and file a report giving the majority's conclusion, the reasons for it, and a transcript of all testimony and exhibits offered. A copy goes to each party the day it is filed, and any party then has fifteen days to object and ask for a hearing.

Md. Code, Corps. & Ass'ns § 3-210

What clients say we are known for

AppraiseItNow Reviews: “The report was quite thorough as well” and “The team was highly knowledgeable, helpful, and efficient”

  1. Being the appraiser they come back to“I highly recommend their appraisal services, especially for private companies” Steve R.Mentioned in 55 reviews
  2. Answering fast, and staying reachable while the work runsMentioned in 47 reviews
  3. Showing the research and the comparables behind the number“Their work was quick, thorough” Jeff H.Mentioned in 35 reviews
  4. Delivering the finished report ahead of the deadlineMentioned in 31 reviews
  5. Following the regulatory guidelines the IRS and the courts requireMentioned in 15 reviews

Across 110+ published AppraiseItNow reviews the picture is consistent: every one is from a client who paid us for an appraisal, and the three things they raise most often are that they would hire us again, how quickly we answer, and how much research is visible in the report.

  • Reached out to Joe and Team in a difficult spot. A client gifted 5 Private Market LPs to a trust and needed a valuation and had a 5 week window to get it done. We had a call with Joe and he outlined what information was needed and provided an estimated cost. We received a detailed engagement letter with final cost. Joe was confident his team could get the job done on time. We received the draft valuation in approximately 4 weeks which needed to be reviewed by tax and legal counsel. When it was all said and done the final report was delivered a couple days earlier than originally promised which was a huge weight lifted off the client and his advisors. Communication is key and AppraiseItNow did a great job from start to finish and delivered exactly what they promised. Great experience!
    Ryan T., Annapolis, MD ·

    Business Valuation for Gift Tax

  • Responsive, professional, first class deliverables -- especially considering that that the appraised assets are extremely complex financial assets with little by way of comps. The deliverable satisfied my accountants and advisers as being more than adequate to support the valuation needed to complete a conversion to a Roth IRA
    Dave T. ·

    Business Valuation for IRA Conversion

  • Joe and Aron were extremely impressive - the entire process went very smoothly. They were always quick to respond to any questions I had and could not have been more helpful. They were aware of some tight time restrictions I had and made sure I received my reports in a timely fashion. I highly recommend them to anyone needing a valuation.
    William L. ·

    Business Valuation for Charitable Donation

  • I used AppraiseItNow to examine a contribution to a foundation. Their work was quick, thorough, and easy to work with, as they’ve developed a simple system for uploading documents. I plan to use them again.
    Jeff H. ·

    Business Valuation for Charitable Donation

  • The team was highly knowledgeable, helpful, and efficient. I highly recommend their appraisal services, especially for private companies.
    Steve R. ·

    Business Valuation for IRA Conversion

  • I found them professional & responsive. The report was quite thorough as well.
    Daniel L. ·

    Business Valuation for Charitable Donation

AppraiseItNow delivers written business valuations for gift and estate tax, IRA conversions, charitable donations, and buy/sell agreements

Given the USPAP-compliant nature of AppraiseItNow’s appraisal reports, we prepare our deliverables for major legal, tax, and financial reporting purposes for individual and commercial clients.

Popular uses of our appraisal reports include:‍

Tax, Estate & Financial Planning

Transactions, Lending & Investment

Frequently Asked Questions on Maryland Business Valuations

What standards govern a business valuation used in tax filings?

The IRS Business Valuation Guidelines in Internal Revenue Manual 4.48.4, which require the appraiser to define the valuation issue, analyze the business's history, financial condition, and earning capacity, and document how comparable transactions and any discounts led to the conclusion. IRS reviewers use these same guidelines to evaluate submitted appraisals.

How are business interests treated in a Maryland divorce?

Maryland follows equitable distribution: the court identifies marital property, values it, and divides it fairly rather than automatically equally. Courts typically value marital assets, including business interests, as of a date near trial, so the valuation needs a current effective date rather than one anchored to the separation.

Does Maryland tax a family business at death?

It can. Maryland imposes an estate tax on taxable estates above $5 million at a 16% rate, plus a separate 10% inheritance tax on property passing to non-exempt beneficiaries. Whether a closely held business crosses those lines depends on its appraised fair market value, which is why succession planning starts with a credible valuation.

When must a Maryland estate value a decedent’s business interest?

Within three months of appointment. Estates and Trusts 7-201 requires the personal representative to file an inventory listing each asset, closely held shares, partnership interests, and LLC stakes included, at fair market value as of the date of death along with any encumbrances. That deadline drives how quickly valuation work needs to be engaged.

Is goodwill divided when a Maryland business goes through divorce?

Only enterprise goodwill. Maryland courts distinguish goodwill that belongs to the business itself from personal goodwill tied to an individual owner’s reputation and relationships, and treat only the enterprise portion as divisible marital property. Separating the two is a valuation exercise, which is why the goodwill allocation often becomes the most contested number in the case.