Nevada Business Valuation

5.0from 80+ client reviews

Business valuations in Nevada for donations, M&A, gift tax, and IRA conversion, prepared in accordance with USPAP and IRS requirements. AppraiseItNow appraises small businesses, partnerships, corporations, LLCs, and professional practices across Nevada, including Las Vegas, Reno, and Henderson.

Get an instant response

DEFENSIBLE, USPAP-COMPLIANT BUSINESS APPRAISAL REPORTS — QUALIFIED FOR THE IRS, NEVADA COURTS, LENDERS, INSURERS, AND MORE.

  • IRS
  • GASB
  • Nevada Courts
  • U.S. Small Business Administration
  • Chase
  • Western Alliance Bank
  • Bank of America

Credentialed Appraisers Serving Nevada

Between them, our business valuation appraisers hold ASA, ABV, and CFA designations, and every report is written to USPAP for the IRS, Nevada courts, lenders, insurers, and more.

Joe Kattan

Joe Kattan

Owner & CEO

Joe founded AppraiseItNow to make a certified, USPAP-compliant appraisal as simple to order as anything else online. A former Bain & Company strategy consultant, Joe leads the entire team and specializes in strategy, growth, and the firm's tech capabilities.

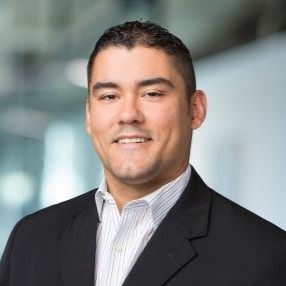
Justin Ramirez

Justin Ramirez

Business Valuation Expert & Appraiser

ASA, ABV, and CFA charterholder. Since 2016 Justin has valued businesses for estate and gift tax, purchase price allocations, fairness opinions, lending, and buy-sell agreements, across manufacturing, services, retail, and pre-revenue biotech.

Raymond Ghelardi

Raymond Ghelardi

Business Valuation Expert & Appraiser

Accredited Senior Appraiser with the American Society of Appraisers. Raymond values capital stock, business enterprises, stock options, and intangible assets.

Aron Blue

Aron Blue

Client Success Manager

Manages each engagement from the first enquiry to the delivered report, and keeps you posted at every step along the way.

  • USPAPWritten to the Uniform Standards of Professional Appraisal Practice
  • American Society of AppraisersAccredited Senior Appraiser
  • AICPAAccredited in Business Valuation
  • CFA InstituteChartered Financial Analyst
  • The Appraisal FoundationAuthorized by Congress as the source of appraisal standards

A Sale, a Gift Return, and a Buyout Ask Three Different Questions About One Nevada Company

AppraiseItNow appraises Nevada companies, and partial interests in them, for sales and purchases, gift and estate returns, charitable donations, and owner buyouts. The engagement names its standard of value before any analysis starts, because the standard decides which adjustments are open to us and which are closed. An operating company, a holding entity and a professional practice are not three versions of one analysis, and the report says which of them it treated this as.

Transfers and filings

A value tied to the day the interest moved

A gift return or an estate filing reports what an interest was worth on one particular day, built from the statements and agreements that existed then. Years later, that is the record the figure stands on, so the working papers behind it matter as much as the conclusion.

Buyouts

A number two sides will both attack

A departing owner and the owners who remain read the same company differently. The valuation sets out what it relied on and what it set aside, so the argument narrows to facts instead of impressions, and the parties can see which assumption is actually between them.

The Records a Las Vegas or Carson City Company Keeps Decide Which Approach Its Nevada Valuation Is Built On

What a company can show us narrows the field before we choose anything. Reviewed statements open one route, a thin set of returns closes it, and a balance sheet weighted with equipment points somewhere else entirely. A Nevada operator with two good years and five lean ones is a different problem from one with a steady decade.

Statements and returns

What the earnings history will support

Five years of statements and returns, the owner's pay reset to what the job would cost to fill, and the working capital the business cannot run without. One customer carrying most of the revenue is priced as risk, not noted as a caveat.

The agreement

What the operating agreement already decided

Transfer restrictions, distribution rights and what happens on a member's death were written down before anyone argued, and they bound what the interest can do long before we were asked about it. An agreement with a formula price in it is evidence, not an answer.

Asset heavy companies

When the balance sheet is the better read

Holding entities, real property companies and operations whose worth sits in machinery are read from what the assets fetch standing alone, and those assets are priced on their own terms first through our Nevada equipment appraisal work.

Nevada Taxes the Company Itself Above One Revenue Figure, and a Reno or Henderson Buyer Prices That In

Two Nevada rules change the number. One says what fair value means when a stockholder is bought out. The other takes a share of revenue before the owners see any of it.

The standard

No discount

for lack of marketability or minority status is permitted when Nevada fair value is determined for a dissenting stockholder

Nevada Writes the Valuation Method Into Its Own Definition of Fair Value

Fair value, with respect to a dissenter's shares, means the value of the shares determined immediately before the effectuation of the corporate action to which the dissenter objects, excluding any appreciation or depreciation in anticipation of that action unless exclusion would be inequitable; using customary and current valuation concepts and techniques generally employed for similar businesses in the context of the transaction requiring appraisal; and without discounting for lack of marketability or minority status.

That last clause is the one that moves money. A minority block discounted heavily for a gift return is valued here on its proportionate footing, so the same shares carry two defensible and very different conclusions depending on why they are being valued at all.

NRS 92A.320

Entity level tax

$4,000,000

of Nevada gross revenue in a taxable year is where the commerce tax starts, at a rate set by the business category the entity designates

A Nevada Company Pays on Revenue Before Its Owners Are Paid Anything

A commerce tax is imposed on each business entity whose Nevada gross revenue in a taxable year exceeds $4,000,000. The taxable year for it runs from July 1 to June 30, and the return is due on or before the forty fifth day immediately following the end of that year. An entity whose Nevada gross revenue is $4,000,000 or less is not required to file a return at all. The amount owed is computed on the revenue above that figure, at the rate for the business category the entity designates on its first return.

In a valuation this is a real charge against the earnings a buyer would acquire, and it is measured on revenue rather than on profit, so a high volume business running a thin margin feels it most.

NRS 363C.080 and 363C.200

What clients say we are known for

AppraiseItNow Reviews: “The report was quite thorough as well” and “The team was highly knowledgeable, helpful, and efficient”

  1. Being the appraiser they come back to“I highly recommend their appraisal services, especially for private companies” Steve R.Mentioned in 44 reviews
  2. Answering fast, and staying reachable while the work runsMentioned in 34 reviews
  3. Showing the research and the comparables behind the number“Their work was quick, thorough” Jeff H.Mentioned in 29 reviews
  4. Delivering the finished report ahead of the deadlineMentioned in 21 reviews
  5. Taking on items other appraisers had already turned downMentioned in 14 reviews

Across 80+ published AppraiseItNow reviews the picture is consistent: every one is from a client who paid us for an appraisal, and the three things they raise most often are that they would hire us again, how quickly we answer, and how much research is visible in the report.

  • Responsive, professional, first class deliverables -- especially considering that that the appraised assets are extremely complex financial assets with little by way of comps. The deliverable satisfied my accountants and advisers as being more than adequate to support the valuation needed to complete a conversion to a Roth IRA
    Dave T. ·

    Business Valuation Appraisal for IRA Conversion

  • Joe and Aron were extremely impressive - the entire process went very smoothly. They were always quick to respond to any questions I had and could not have been more helpful. They were aware of some tight time restrictions I had and made sure I received my reports in a timely fashion. I highly recommend them to anyone needing a valuation.
    William L. ·

    Business Valuation Appraisal for Charitable Donation

  • I used AppraiseItNow to examine a contribution to a foundation. Their work was quick, thorough, and easy to work with, as they’ve developed a simple system for uploading documents. I plan to use them again.
    Jeff H. ·

    Business Valuation Appraisal for Charitable Donation

  • The team was highly knowledgeable, helpful, and efficient. I highly recommend their appraisal services, especially for private companies.
    Steve R. ·

    Business Valuation Appraisal for IRA Conversion

  • I found them professional & responsive. The report was quite thorough as well.
    Daniel L. ·

    Business Valuation Appraisal for Charitable Donation

  • From the start they were very responsive, price competitive, and had a quick turn around time. Thank you so much to Joe who was very sweet in responding to my emails; I am looking forward to utilizing AppraiseItNow for many years to come.
    Chris S. ·

AppraiseItNow delivers written business valuations for gift and estate tax, IRA conversions, charitable donations, and buy/sell agreements

Given the USPAP-compliant nature of AppraiseItNow’s appraisal reports, we prepare our deliverables for major legal, tax, and financial reporting purposes for individual and commercial clients.

Popular uses of our appraisal reports include:‍

Transactions, Lending & Investment

Frequently Asked Questions on Nevada Business Valuations

What should a credible Nevada business valuation report state?

The standard of value, the premise of value, the effective date, the exact interest being valued, and every key assumption and information source. Professional standards from USPAP, the AICPA, ASA, and NACVA all require these identifications, and a report that presents a number without them will not hold up to scrutiny.

Are fair market value and investment value the same number?

No, and confusing them is a frequent and costly error. Fair market value is the price between a hypothetical willing buyer and seller under no compulsion, while investment value reflects worth to a particular buyer including synergies. Selecting the wrong basis of value for a Nevada engagement can swing the conclusion substantially.

Does Nevada tax a business interest passing through an estate?

No. Nevada repealed its former estate tax and has no inheritance tax, so there is no state-level exemption amount or rate schedule to plan around. Valuation requirements for Nevada estates holding company interests come from federal estate tax rules and probate administration, both of which rest on fair market value.

Who pays Nevada personal property tax on financed business equipment?

The business in possession, not the lender. Under NRS 361.245, property subject to a security interest is deemed the property of the possessor for tax purposes, so a company using financed machinery lists and pays tax on it even though a bank holds title. Asset schedules behind a Nevada valuation should reflect that treatment.

What happens if a Nevada business skips its property declaration?

The assessor can estimate the value and add penalties. Nevada ties assessment to the July 1 lien date, and NRS 361.265 requires a signed statement listing all taxable personal property owned, possessed, or controlled. Failing to provide it invites an estimated assessment, and contesting an estimate costs more than filing a clean, well-supported declaration.