How is gifted personal property valued for gift tax?
At fair market value on the date of the gift under Treasury Regulation 25.2512-1, measured in the market where the item is most commonly sold to the public. For many personal items that is the retail market, and the regulation expressly rejects forced-sale prices as the measure of value.
When does a gift of personal property need to be reported to the IRS?
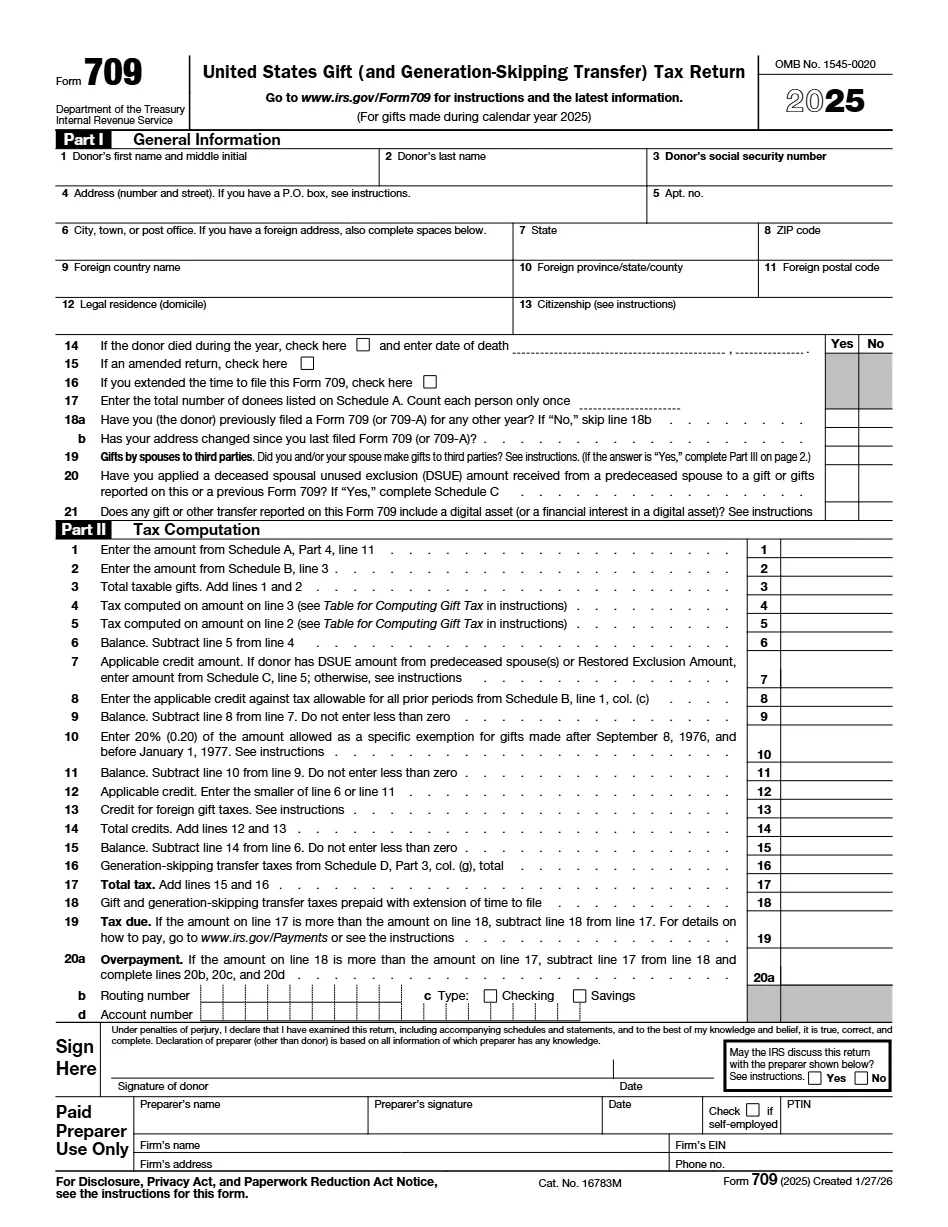
When its value to any one recipient exceeds the annual exclusion, which is $19,000 for 2025, reporting on Form 709 is generally required even if no tax is due, per IRS gift tax guidance. The appraisal often determines which side of that line a gifted item falls on.
Does the recipient of gifted property get a stepped-up basis?
No. A donee generally takes the donor's adjusted basis for computing gains, with fair market value at the gift date serving as the floor for losses, and gift tax paid on post-1976 appreciation can increase basis. That is why FMV support matters even when no tax is currently owed.
Can a tax assessment or trade-in quote establish gift tax value?
Not by itself. The regulation permits a local assessment only when it actually represents fair market value on the gift date, and wholesale or trade-in figures usually reflect the wrong market. The IRS looks to the asset's ordinary public sale channel, adjusted for location where relevant.