Washington Equipment Appraisers

5.0 on Google110+ 5-star reviews

Equipment appraisals in Washington for donations, lending, M&A, and financial reporting, prepared in accordance with USPAP and IRS requirements. AppraiseItNow appraises manufacturing equipment, construction machinery, agricultural equipment, medical devices, and industrial tools across Washington, including Seattle, Spokane, and Tacoma.

Get an instant response

DEFENSIBLE, USPAP-COMPLIANT MACHINERY & EQUIPMENT APPRAISAL REPORTS — QUALIFIED FOR THE IRS, WASHINGTON COURTS, LENDERS, INSURERS, AND MORE.

  • U.S. Small Business Administration
  • Chase
  • Wells Fargo
  • WaFd Bank
  • Nationwide Insurance
  • Bank of America
  • IRS
  • Washington Courts

Credentialed Appraisers Serving Washington

Between them, AppraiseItNow's machinery and equipment appraisers hold CAGA designations. These are a few of them, and our reports are written to USPAP for the IRS, Washington courts, lenders, insurers, and more.

Joe Kattan

Joe Kattan

Owner & CEO

Joe joined AppraiseItNow as a co-owner in 2022 and acquired the company in November 2024 to make a certified, USPAP-compliant appraisal as simple to order as anything else online. A former Bain & Company strategy consultant, Joe leads the entire team and specializes in strategy, growth, and the firm's tech capabilities.

Jason Dolph

Jason Dolph

Machinery & Equipment Appraiser

Third-generation auctioneer and CAGA Certified Appraiser with more than 20 years valuing machinery, equipment, vehicles, business assets, and estates for banks, attorneys, and trustees across the Carolinas.

Marnie Erkelens

Marnie Erkelens

Vehicle Appraiser

CAGA Certified Appraiser since 2014, covering vehicles, boats, equipment, fine art, and collectibles. A classic-car restoration background informs her vehicle work, with reports prepared for insurance, divorce, and charitable contributions.

Aron Blue

Aron Blue

Client Success Manager

Manages each engagement from the first enquiry to the delivered report, and keeps you posted at every step along the way.

  • USPAPWritten to the Uniform Standards of Professional Appraisal Practice
  • Certified Appraisers Guild of AmericaCertified Appraiser
  • The Appraisal FoundationAuthorized by Congress as the source of appraisal standards
Scope we handle
Lines and single assetsOne CNC machine or a diagnostic imaging unit, a processing line, the contents of a shop, or a full plant across several sites.
Which standard the report carries
Named up frontFair market value for a donation return or a transaction, orderly and forced liquidation value for a lender or a wind down, replacement cost for an insurance schedule.
How the work runs
Online, onsite at scaleMost Washington assignments run from asset lists, purchase invoices, and photographs. Larger multi-site projects get an inspection in person.

Machine Shops in Everett and Clinics in Spokane Need Washington Equipment Valued for Lenders, Donations, and Filings

AppraiseItNow appraises machinery and equipment in Washington for asset based lending, charitable donation returns, purchases and sales, financial reporting, and county personal property listings and appeals.

Assets we value

Production, shop, and clinical equipment

The state's mix runs from aerospace and marine fabrication to food processing, timber, and healthcare, and the same shop floor often holds assets bought a decade apart. We appraise:

  • Manufacturing and production machinery
  • Construction and heavy equipment
  • Agricultural equipment and implements
  • Medical, dental, and imaging equipment
  • Shop tooling, forklifts, and support assets

Which value applies

Fair market, orderly liquidation, and forced liquidation

A lender underwriting against equipment wants to know what it brings in an orderly sale and what it brings in a fast one. A donor needs fair market value on the day of the gift. A buyer needs the figure that holds while the plant keeps running. The intended use picks one of those, the report states which, and the difference between them on a single line of machinery can be most of its value.

Listings and appeals

Values for the listing and for the appeal

Cost and year of acquisition say nothing about a machine idle for two seasons or superseded by a newer model. Where the assessed figure runs past what the equipment would actually bring, a supported value is what the appeal is argued from, and the same schedule serves the next year's listing.

Transactions

Values written for a sale or a wind down

Buying a line, selling a division, or closing a site all come back to what the assets fetch away from the business that ran them. We develop those figures from auction results and dealer sales for comparable machines, adjusted for hours, condition, and how specialised the equipment is, then say which market each number assumes.

Two Donation Files From Woodland and Stanwood Show How We Value Washington Equipment

Two Washington assignments, reduced to a line each. The client names, the figures, and the locations stay in the working file.

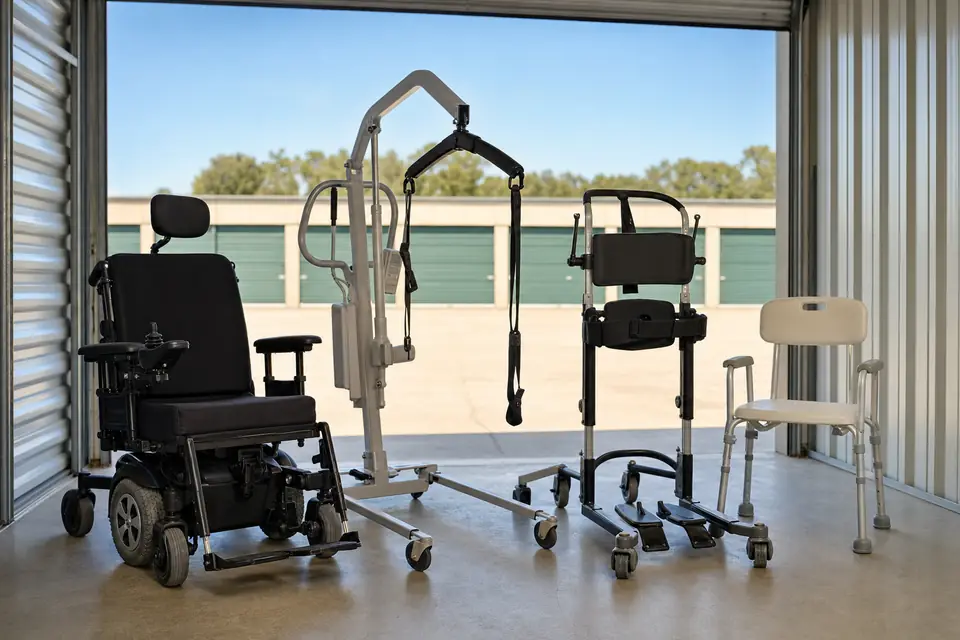
Power wheelchair, patient lift, standing frame, and shower chair grouped in an open storage unit in daylight

Charitable donation

Home medical equipment in Woodland, valued as one group

Power wheelchairs, a lift system, a standing frame, and bath and transfer aids held in a storage unit, valued together for a noncash charitable contribution.

  • Fair market value
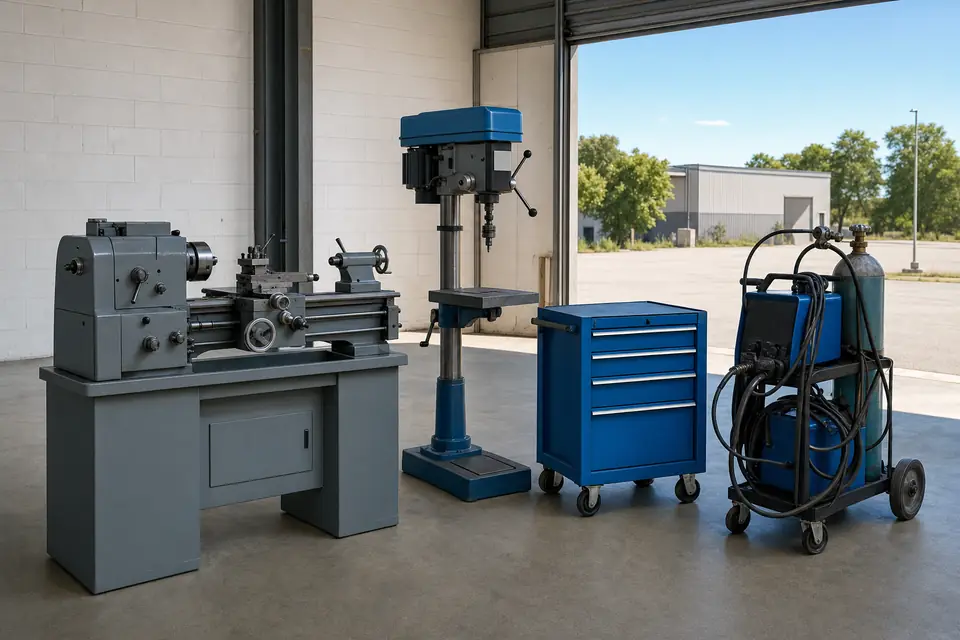
Lathe, drill press, tool cabinet, and welding cart on a workshop floor beside an open roller door

Donation filing

Equipment donated by a Stanwood owner

Machinery and equipment valued at fair market value for the donor's noncash charitable contribution return.

  • Fair market value

Washington Taxes Equipment, Exempts Part of It, and Collects Early When It Moves

Three rules sit under every equipment file in this state, and each of them turns on a line somebody has to draw across a plant.

Sales tax

Used directly

the test Washington applies to machinery bought by a manufacturer or processor for hire

Washington Exempts the Machinery Used Directly in Production, and Not the Building Around It

Sales to a manufacturer or processor for hire of machinery and equipment used directly in a manufacturing, research and development, or testing operation are exempt from retail sales tax, together with the labor to install, repair, clean, alter, or improve it. The statute then draws its line: machinery and equipment does not include hand-powered tools, property with a useful life of under one year, buildings, or building fixtures that are not integral to the operation, such as heating, ventilation, plumbing, and electrical systems.

A cost study has to draw the same line. Qualifying production machinery carries no sales tax inside its cost new, the fixtures around it do, and the two depreciate on different curves.

RCW 82.08.02565

Liens

Each item

the unit a Washington personal property tax lien attaches to

A Washington Tax Lien Rides on the Equipment Itself, Through Any Sale

Taxes assessed on personal property become a lien on that property from the date it is listed with and valued by the county assessor, and no sale or transfer of the property affects that lien. The treasurer may also charge the amount against real property of the person assessed, and against other goods distrained for it.

Used equipment therefore carries its own history. A buyer pulling a line out of a Washington plant, or a lender taking it as collateral, is looking at assets whose unpaid tax follows them, which is one reason the report identifies what it valued and on what basis.

RCW 84.60.020

Advance tax

Before the levy

when Washington can tax equipment that looks likely to leave the county

Equipment About to Leave Washington Can Be Taxed and Distrained Without Notice

Where the assessor or the county treasurer judges that personal property is being removed from the state, dissipated, sold, or taken out of the county so as to jeopardize collection of taxes, the treasurer prepares papers in distraint at once and, without demand or notice, distrains enough goods to cover the tax, the interest, and the costs.

If that happens after January 1 but before the year's levy, the tax is computed on the preceding year's rate and entered on the prior year's rolls. Auctions, plant closures, and equipment heading to another state all sit inside that rule, and each of them starts with a number.

RCW 84.56.090

What Washington clients say we are known for

Washington Appraisal Reviews: “Very impressive and incredibly helpful” and “I highly recommend the AppraiseItNow team”

  1. Being the appraiser they come back to“I would definitely use them again” Richard A.Mentioned in 12 reviews
  2. Answering fast, and staying reachable while the work runs“They were responsive and timely from start to finish” Julia P.Mentioned in 7 reviews
  3. Showing the research and the comparables behind the number“They diligently researched both equipment items and provided well-documented reports” Bob H.Mentioned in 6 reviews
  4. Delivering the finished report ahead of the deadlineMentioned in 4 reviews
  5. Taking on items other appraisers had already turned downMentioned in 4 reviews

Across 19 published Washington appraisal reviews, every one from a client who paid AppraiseItNow for an appraisal, the three things they raise most often are that they would hire us again, how quickly we answer, and how much research is visible in the report.

  • I needed a rapid turnaround appraisal on a charitable donation. The team here was able to review and complete my appraisal in under 24 hours, the same day that I sent the request in. Very impressive and incredibly helpful!
    Phil R. ·

    Machinery & Equipment Appraisal for Charitable Donation

  • I highly recommend the AppraiseItNow team. They were responsive and timely from start to finish, and the whole process was seamless. The final report was super detailed and gave me all the information I needed. I am so glad I hired them and would recommend them to anyone needing an appraisal!
    Julia P. ·

    Technology Equipment Appraisal for Divorce

  • I recommend AppraiseItNow Inc. highly. I needed an appraisal of fair market value for geologic laboratory equipment for charitable donations to three universities. The unique items and limited secondary market complicated the valuation. They provided a sound, verifiable estimate and the 8283 forms that I was able to use in my tax filings. I would use them again.
    Alan B. ·

    Lab Equipment Appraisal for Charitable Donation

  • I needed an IRS-qualified appraisal for an unusual and costly piece of medical equipment. AppraiseItNow was able to provide me exactly what I needed on a timely basis. The personnel at the company are very friendly and helpful. I would definitely use them again.
    Richard A. ·

    Medical Equipment Appraisal for Charitable Donation

  • AppraiseItNow did an outstanding job appraising my 1998 Bobcat Skid Steer and circa 2010 Yuchai Crawler Dozer. We could not locate a serial number on the dozer, and there were no online sales available, but they were still able to develop an accurate appraisal using known specifications for my dozer compared to other comparable make and model dozers. They diligently researched both equipment items and provided well-documented reports.
    Bob H. ·

    Machinery & Equipment Appraisal

  • Affordable and reliable, with fast service and always responsive to my messages and questions. They delivered my appraisal on time without a glitch. 100% Recommended! I wouldn’t use anyone else for my business. Thank you, Joe — you’re great!
    Ana R. ·

    Machinery & Equipment Appraisal for Bankruptcy Filing

We produce written equipment appraisal reports for lending, insurance, charitable donations, and litigation

Given the USPAP-compliant nature of AppraiseItNow’s appraisal reports, we prepare our deliverables for major legal, tax, and financial reporting purposes for individual and commercial clients.

Popular uses of our appraisal reports include:‍

Tax, Estate & Financial Planning

Transactions, Lending & Investment

Insurance & Risk Management

Life Events & Special Circumstances

  • Divorce
  • Social Security reporting or Medicaid Application Filings
  • E-2 visa applications

Frequently Asked Questions on Washington Equipment Appraisers

How do we appraise specialized machinery with few comparable sales?

With the cost approach: we develop current replacement cost from manufacturer or vendor quotes and cost guides such as Marshall Valuation Service, then deduct physical, functional, and economic depreciation. For Washington processors and manufacturers running custom lines, this is often the most reliable path to a supportable value.

What goes on Washington's annual personal property listing?

Item-level detail for taxable business equipment: description, cost, and year of acquisition, with cost defined to include freight and installation but exclude sales tax. The listing is generally due to the county assessor by April 30, and assessors use it to value property at 100% of true and fair market value as of January 1.

What happens if a business misses Washington's listing deadline?

Statutory penalties apply, calculated as a percentage of the tax due, on top of the assessed tax itself. Filing on time with accurate cost data is cheaper than defending an assessor's estimate later, and an independent appraisal can support a correction when listed costs no longer reflect the equipment's actual condition or market.

How is software treated when Washington equipment is valued for tax?

Embedded software, the control code built into CNC machines, medical devices, and similar equipment, is valued as part of the machine itself. Standalone software follows a statutory schedule under RCW 84.40.037: 100% of acquisition cost the first year, 50% the second, and no taxable value afterward. Separating the two on a listing can meaningfully change an assessment.

Is Washington farm equipment fully exempt from property tax?

No, only partly. RCW 84.36.630 exempts qualifying farm machinery and equipment owned by an active farmer from the state portion of the property tax, but county and other local levies still apply. Owners sometimes assume the exemption wipes out the whole bill; it does not, and the equipment must still be listed and valued.