What value should machinery be insured at?
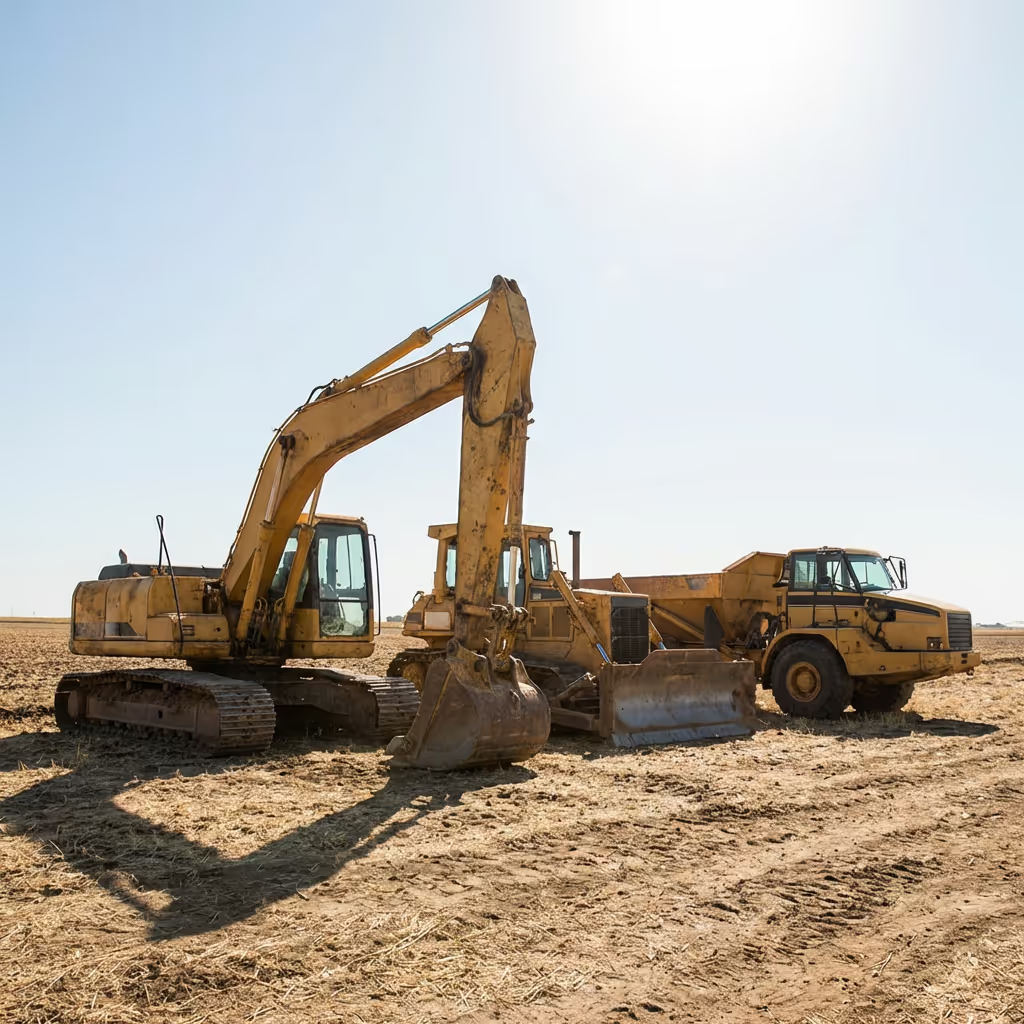
Its new replacement value when the policy is written on a sum-insured or replacement-cost basis: the current cost to replace with like kind and quality, ignoring depreciation. Scheduling older equipment at book value or secondhand market price is the classic mistake, because the policy limit then falls short of actual replacement cost and underinsurance penalties follow.
Which insurance-specific value definitions appear in these appraisals?
Insurance cost new, meaning replacement or reproduction cost new as the policy defines it less specifically excluded items, and insurable value depreciated, which subtracts accrued depreciation as considered for insurance purposes. These policy-tied standards, not generic fair market value, are what carriers expect an equipment coverage appraisal to report.
How do appraisers keep replacement values current?
By periodic reappraisal, escalating original purchase prices with cost indices or obtaining current supplier quotations, with adjustments for freight, duties, and exchange rates on imported machinery. Inflation and technology changes erode scheduled values quickly, and outdated schedules are a leading cause of underinsured equipment losses.
Where does fair market value fit in insurance coverage work?
Mostly it does not. Fair market value anchors tax, estate, and litigation appraisals, but insurers indemnify on replacement cost or actual cash value as defined in the policy, and at claim time ACV formulas cap recovery based on age and service life. We state the applicable insurance standard in the report so the schedule matches how a claim would actually be paid.