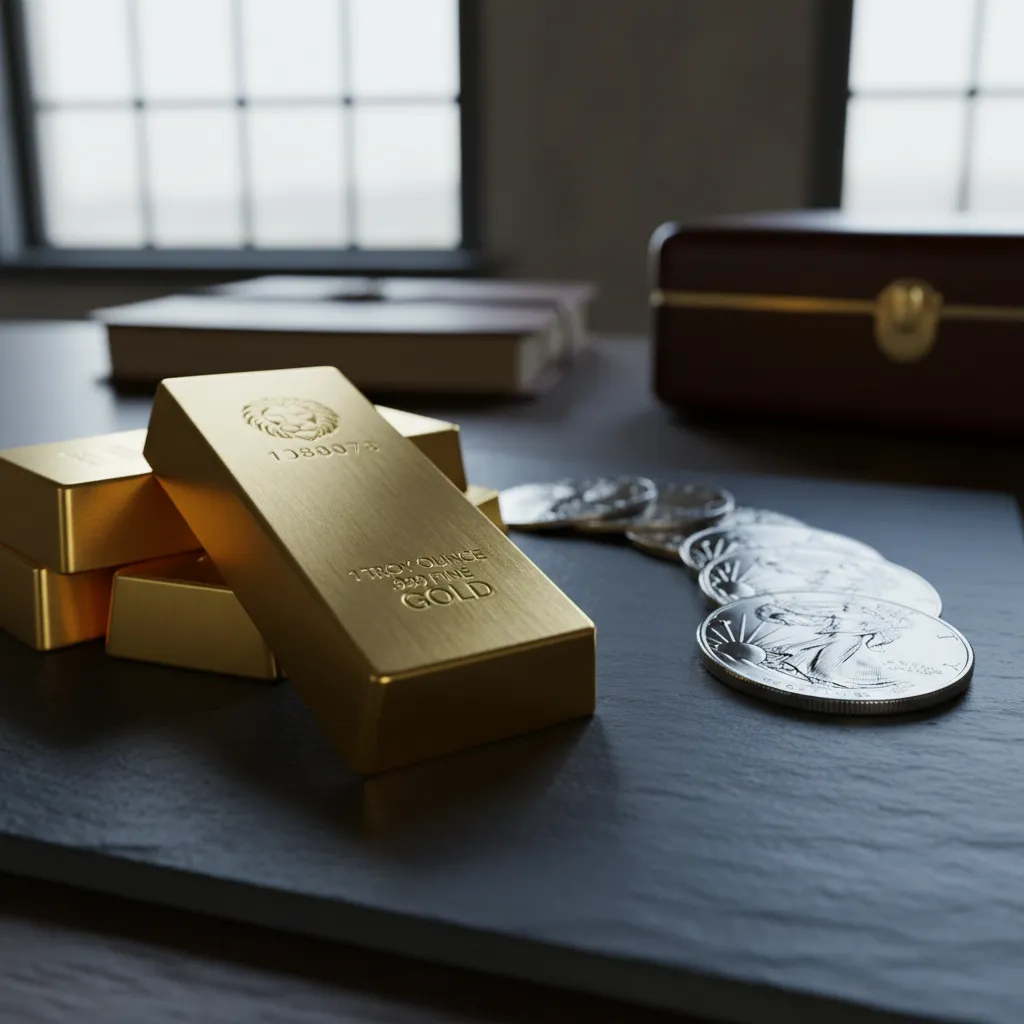
Is bullion worth exactly spot price times weight?
Not quite. Spot times verified weight and purity sets the intrinsic value, but real transactions include dealer spreads, premiums, and discounts driven by brand, mint, product type, and liquidity. Many dealers buy common gold bullion around 95% of spot and some silver around 90%, while sovereign coins can carry premiums over generic bars. A professional appraisal documents these market frictions with dealer and auction evidence rather than assuming a frictionless spot calculation.
How is bullion purity verified during an appraisal?
By precise weighing (grams converted to troy ounces at 31.1 grams each) combined with testing: acid testing, nondestructive X-ray fluorescence (XRF), or fire assay for larger bars. Purity math matters: a 10 gram 18K item contains only 7.5 grams of pure gold, so pricing the full weight overstates value by a third. Non-metal components such as gemstones are weighed out before pricing.
Why doesn’t a bullion coin’s face value matter?
Because bullion is valued by weight and purity, not nominal denomination. A one-ounce gold coin with a $50 face value tracks the current one-ounce gold price. Original purchase price is equally unreliable: spot prices and dealer spreads change daily, so the appraisal uses the valuation date’s spot price and contemporaneous market data.
What does a strong bullion appraisal report include?
The effective valuation date, the standard of value (fair market, orderly liquidation, or insurance replacement), the documented spot price and dealer bid evidence, and comparable sales for the specific products. It also separates intrinsic metal value from any numismatic premium, supporting each component with market evidence. Cursory lump-sum letters are commonly challenged by auditors, courts, and insurers.
When do taxes require a formal bullion appraisal?
Charitable donations of bullion exceeding $5,000 require a qualified appraisal reported on Form 8283 Section B, with the appraisal itself attached for items over $500,000. Estates and gifts report fair market value as of the date of death or gift on Forms 706 and 709, and values near federal thresholds need precise, supportable documentation.