What does an Indiana probate inventory require for personal property?
The personal representative must prepare and file an inventory of the estate's property, tangible personal property included, generally within 60 days of the issuance of letters, using court-approved forms that list and value each asset. Supportable date-specific values keep the filing consistent with later accountings.
Why is the effective date such a big deal in personal property appraisals?
Because the assignment dictates whether value is current, retrospective, or prospective: date of death for estate tax, date of gift for gift tax, date of casualty for loss claims. Misaligning the effective date with the legal or tax event is one of the most frequent errors in appraisals prepared without a clear intended use.
Are insurance appraisals interchangeable with fair market value appraisals?
No. Insurance appraisals develop replacement cost using current retail pricing and little or no depreciation, while fair market value work reflects what a willing buyer would actually pay in the relevant market. The two use different definitions, methods, and data sources, so one cannot stand in for the other on an Indiana estate or tax filing.
Can an Indiana estate use more than one appraiser for a household’s contents?
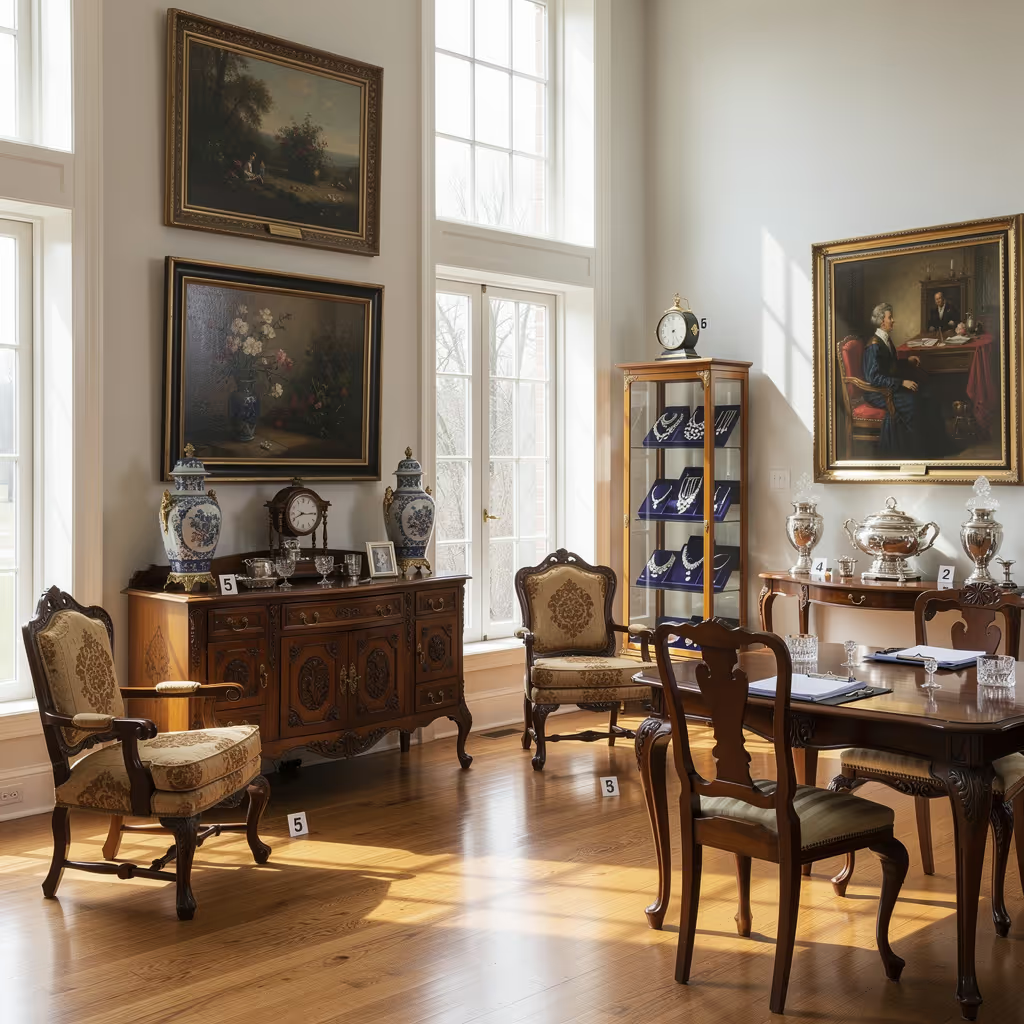
Yes. Indiana Code 29-1-12-1(c) lets the personal representative employ a disinterested appraiser to help establish fair market value as of the date of death for any asset whose value may be subject to reasonable doubt, and expressly allows different people to appraise different kinds of assets. Furniture, jewelry, artwork, and a vehicle can each go to a specialist, and the inventory must list each appraiser’s name and address beside the items they valued.