Which valuation approach fits brewery equipment best?
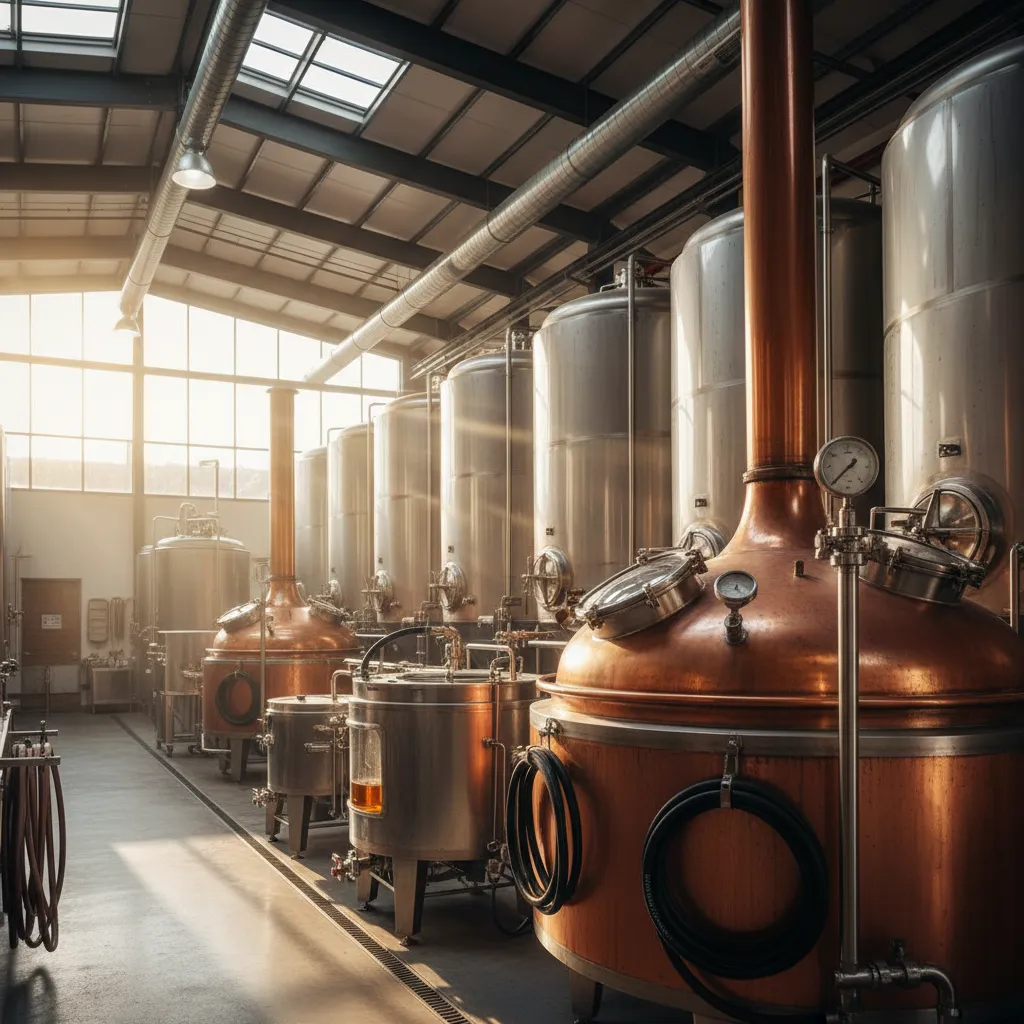
The market approach usually leads, because the used market for brewhouses, tanks, canning lines, and packaging equipment provides robust evidence of actual transaction prices from comparable sales, dealer offerings, and broker interviews. The cost approach serves as a secondary check and must be benchmarked against market data; the income approach is generally hypothetical for machinery embedded in a process line.
Why do lenders want orderly liquidation value for brewery equipment?
Because collateral analysis assumes a constrained sale, not a patient one. Orderly liquidation value, based on a 60 to 90 day marketing window, often runs 30 to 50% below fair market value for specialized brewing equipment, and forced liquidation value in a distress auction may be only 20 to 40% of fair market value. SBA and commercial lenders routinely request these standards alongside or instead of fair market value.
Do per-barrel rules of thumb tell me what my brewing equipment is worth?
No. Heuristics like $100 to $300 per barrel of installed capacity, or 4x to 6x EBITDA for brewery sales, are business-valuation shortcuts that blend goodwill and enterprise value. Applied directly to brewhouses, fermenters, or packaging lines, they can badly misstate what the specific assets would bring, which is why equipment-level market and cost analysis is required.
What should I have ready before a brewery equipment appraisal?
An itemized inventory recording brand, model, year, capacity, and condition for each asset, plus maintenance records. Age, production capacity, efficiency, adaptability, and documented upkeep strongly influence value for fermenters, brewhouses, bottling lines, and ancillary equipment, and thorough records shrink the uncertainty in the conclusion.
What makes a brewery equipment appraisal acceptable to a lender or court?
A written, USPAP-compliant report that states which approaches were considered, which was selected for each major asset category, and the specific market data supporting each conclusion, rather than unsupported lump-sum figures. Reports built this way hold up in SBA lending files, business sales, and litigation.