How is dry cleaning equipment appraised?
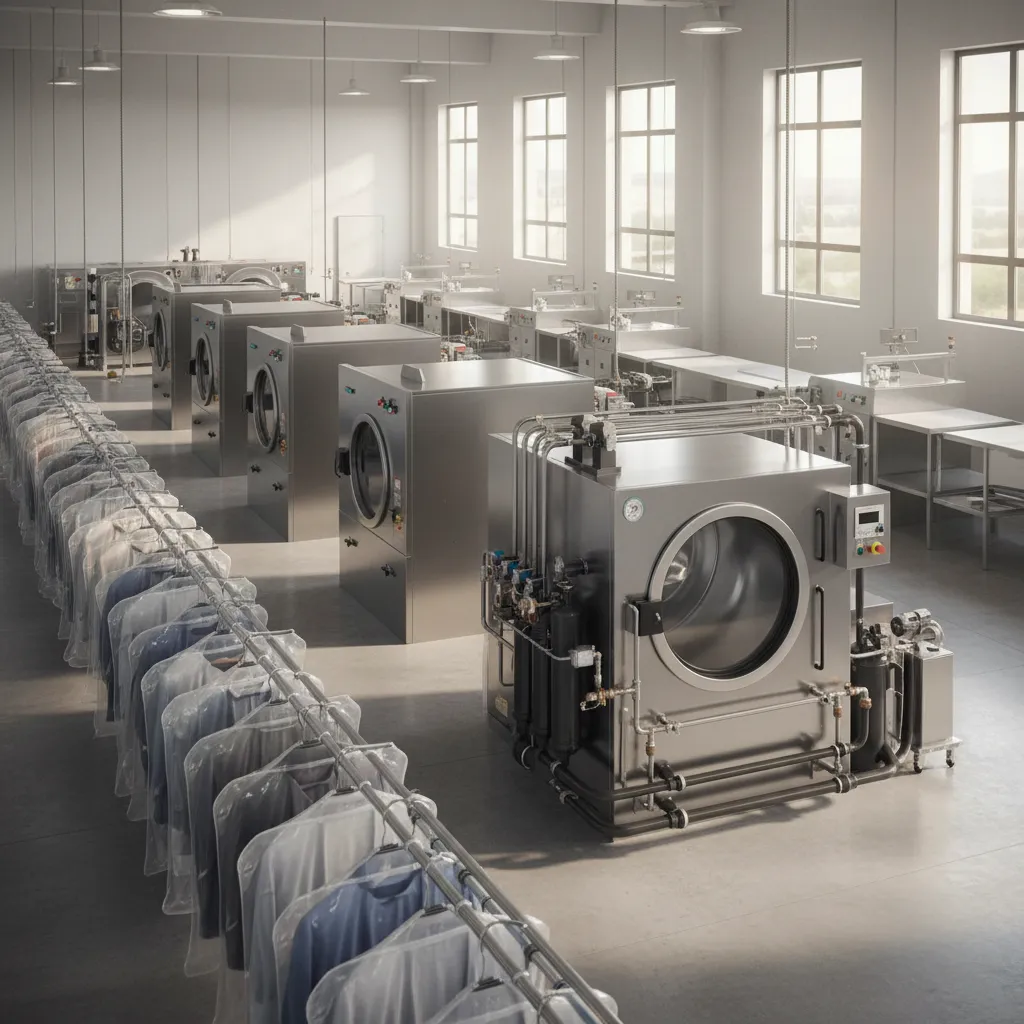
Using the cost, market, and income approaches recognized for machinery and equipment. For plants, presses, washers, dryers, boilers, and finishing equipment, our appraisers draw market evidence from industrial auction records, laundry equipment dealer listings, and used-equipment marketplaces, and develop cost-approach values from current replacement cost new less physical, functional, and economic depreciation. The income approach is reserved for revenue-tied assets such as coin-operated machines.
Can business valuation multiples tell me what my equipment is worth?
No. Rules of thumb like 2.0 to 4.0 times seller’s discretionary earnings, 30 to 50% of revenue, or per-machine heuristics estimate whole-business value including goodwill, customer relationships, and location. Applied to machinery alone, they overstate what the equipment would bring in an asset sale and conflict with equipment-only auction results and lender collateral values.
Which premise of value should a dry cleaning equipment appraisal state?
The one matching the assignment: fair market value in continued use for an operating plant, orderly liquidation value for lender risk analysis, or forced liquidation value for distress scenarios. Each premise yields materially different numbers, and mixing premises within one schedule without labels undermines lender, tax, or transaction reliance on the report.
When do lenders require a dry cleaning equipment appraisal?
Commonly when the machinery is pledged as loan collateral, especially in SBA-backed acquisitions, refinancings, or changes of ownership where equipment is a material portion of the loan. Underwriters expect line-item values with clearly stated premises so they can test loan-to-value ratios and recovery scenarios separately from goodwill and leasehold interests.
How does tax depreciation treat dry cleaning machinery?
Most laundry and dry cleaning machinery is 5-year MACRS property under IRC Section 168, reported through Form 4562, even though its economic useful life is often longer. An appraisal supporting fixed-asset or impairment work must reconcile its remaining-life and cost conclusions with those tax classifications, which is another reason tax book value rarely equals market value.